


Will Management Layoffs Change Alaska Air's (ALK) Narrative
- Alaska Air Group has begun cutting about 200 management roles, including 48 in Hawaii, in response to rising fuel costs, geopolitical pressures and a warning that the business could post a significant loss if current conditions persist.
- The decision to trim management layers signals a sharper focus on overhead and cost discipline, just as Alaska Air Group leans into international capacity growth, new Asia Pacific flying and digital transformation under its newly appointed chief information technology officer.
- Next, the focus is on how Alaska Air Group’s cost cutting and management layoffs could reshape its longer term investment narrative.
Alaska Air Group Investment Narrative Recap
To own Alaska Air Group, you need to believe the airline can turn current losses into steady earnings while shifting toward more international, premium and loyalty driven revenue. The latest guidance points to only modest capacity growth of 1% to 1.5% in Q4 2026, with healthy demand and low double digit RASM growth supporting that thesis.
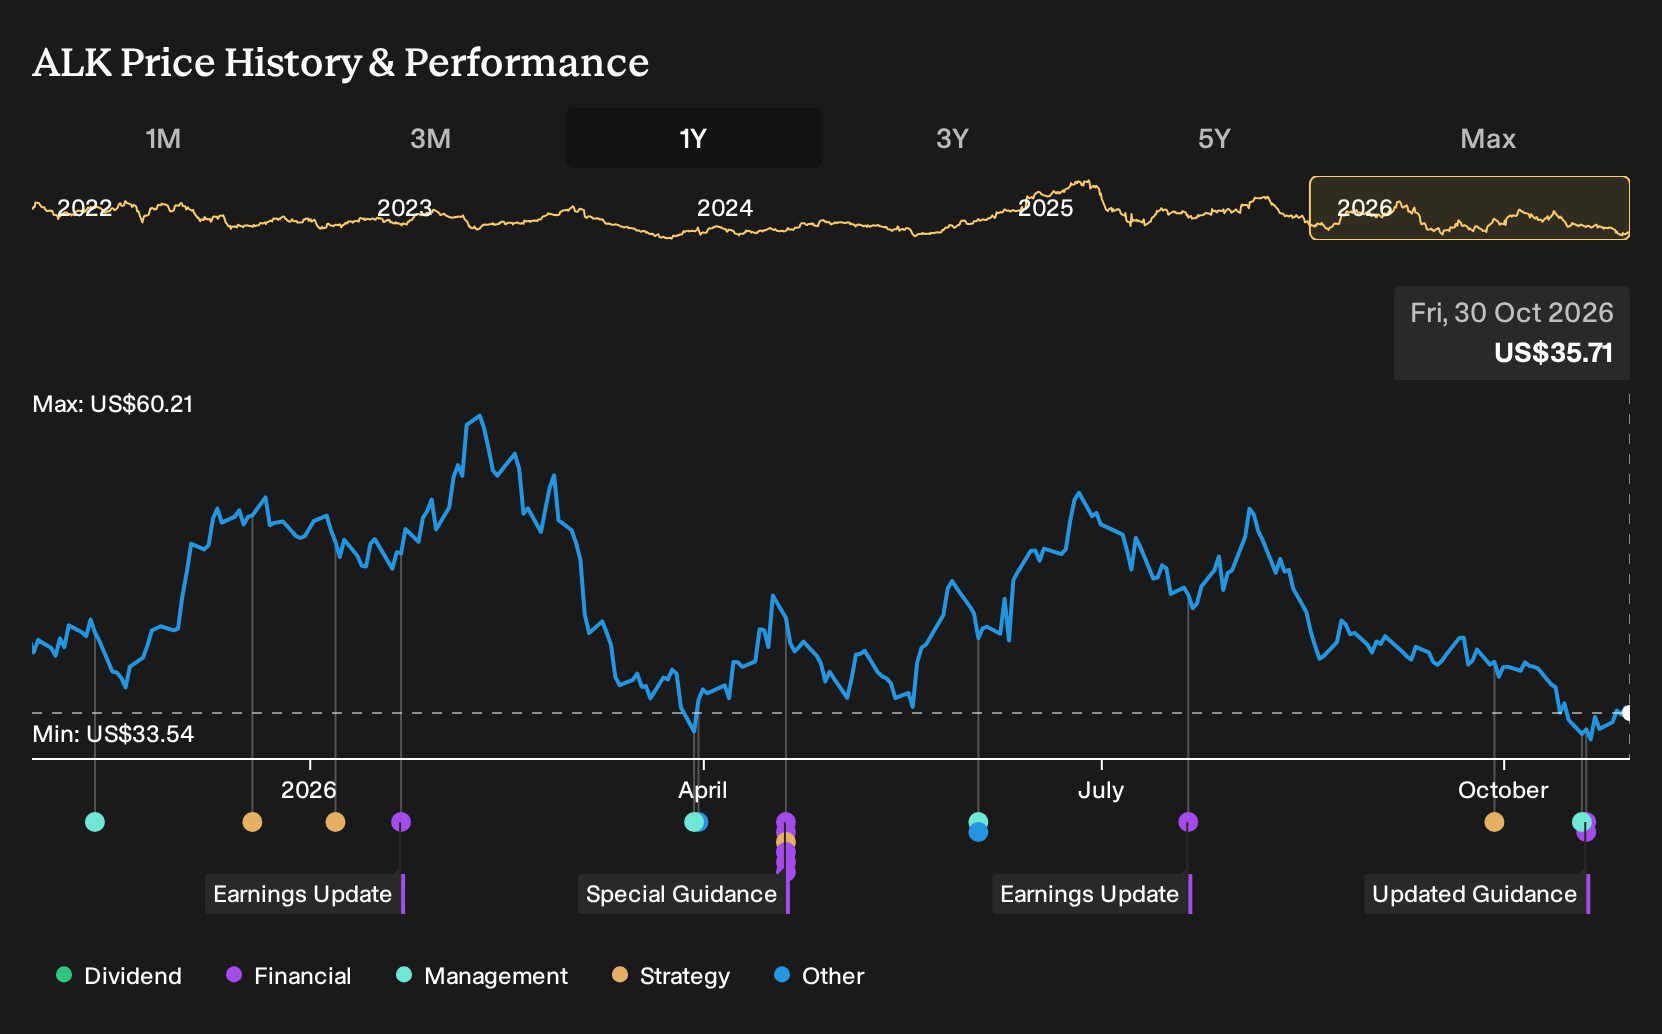
The near term swing factor is whether that strong unit revenue is enough to offset higher costs, with CASMex still expected to rise mid single digits and fuel and labor already pressuring results. The biggest risk remains prolonged cost inflation and leverage, especially after a US$147 million Q3 loss and US$416 million loss year to date.
The Q4 2026 outlook is the most relevant announcement for judging this cost cutting news. Management is signaling that demand and pricing are holding up, with unit revenue expected to climb in the low double digits while capacity edges higher, mostly in international markets such as the new Anchorage to Tokyo route.
For investors, that sets a clear execution test. Alaska Air Group needs the higher revenue per seat and international mix to show through in cash generation, while recent layoffs and digital investments, including the new chief information technology officer role, help keep non fuel unit costs under control and support progress on leverage and Hawaiian integration goals.
Alaska Air Group's narrative projects US$19.2b revenue and US$1.5b earnings by 2029. This assumes 9.1% yearly revenue growth and an earnings increase of about US$1.7b from current earnings, which are a US$175.0m loss.
Discover why Alaska Air Group's fair value indicates a 54% potential upside to its current price. This discount could close sooner than you expect.
Exploring Other Perspectives
One alternate view on Alaska Air Group leans hard into fuel risk. Those more pessimistic analysts were already working with slower 5.2% annual revenue growth assumptions and earnings only reaching about US$2.0b by 2029 before this latest guidance and layoff news. Their caution highlights how sharply opinions can differ, so it pays to explore several narratives before deciding what you think happens next.
Explore 2 other Alaska Air Group fair value estimates, including one that suggests it could be worth just $51.88!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider building your own well-researched view.
- A great starting point for your Alaska Air Group research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Alaska Air Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Alaska Air Group's overall financial health at a glance.
Looking For More Investment Ideas Beyond Alaska Air Group?
If the Alaska Air Group story has you thinking about how cost discipline, balance sheets and earnings power line up, it can help to compare it with a few other listed businesses that share some of those traits but sit in very different corners of the market.
- For investors who want potential upside but still care about financial strength, start with a curated 18 high quality undiscovered gems that pair sturdier fundamentals with less crowded ownership.
- If resilience matters more to you than big swings, narrow your watchlist to companies screened as 30 resilient stocks with low risk scores and see which ones fit your own tolerance for volatility and drawdowns.
- When balance sheet quality is non negotiable, focus on businesses that pass strict debt and liquidity filters through a list of solid balance sheet and fundamentals (25 results) so you can zero in on those that look better equipped for choppy conditions.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com