


Earnings And Buyback Might Change The Case For Investing In CVB Financial Stock (CVBF)
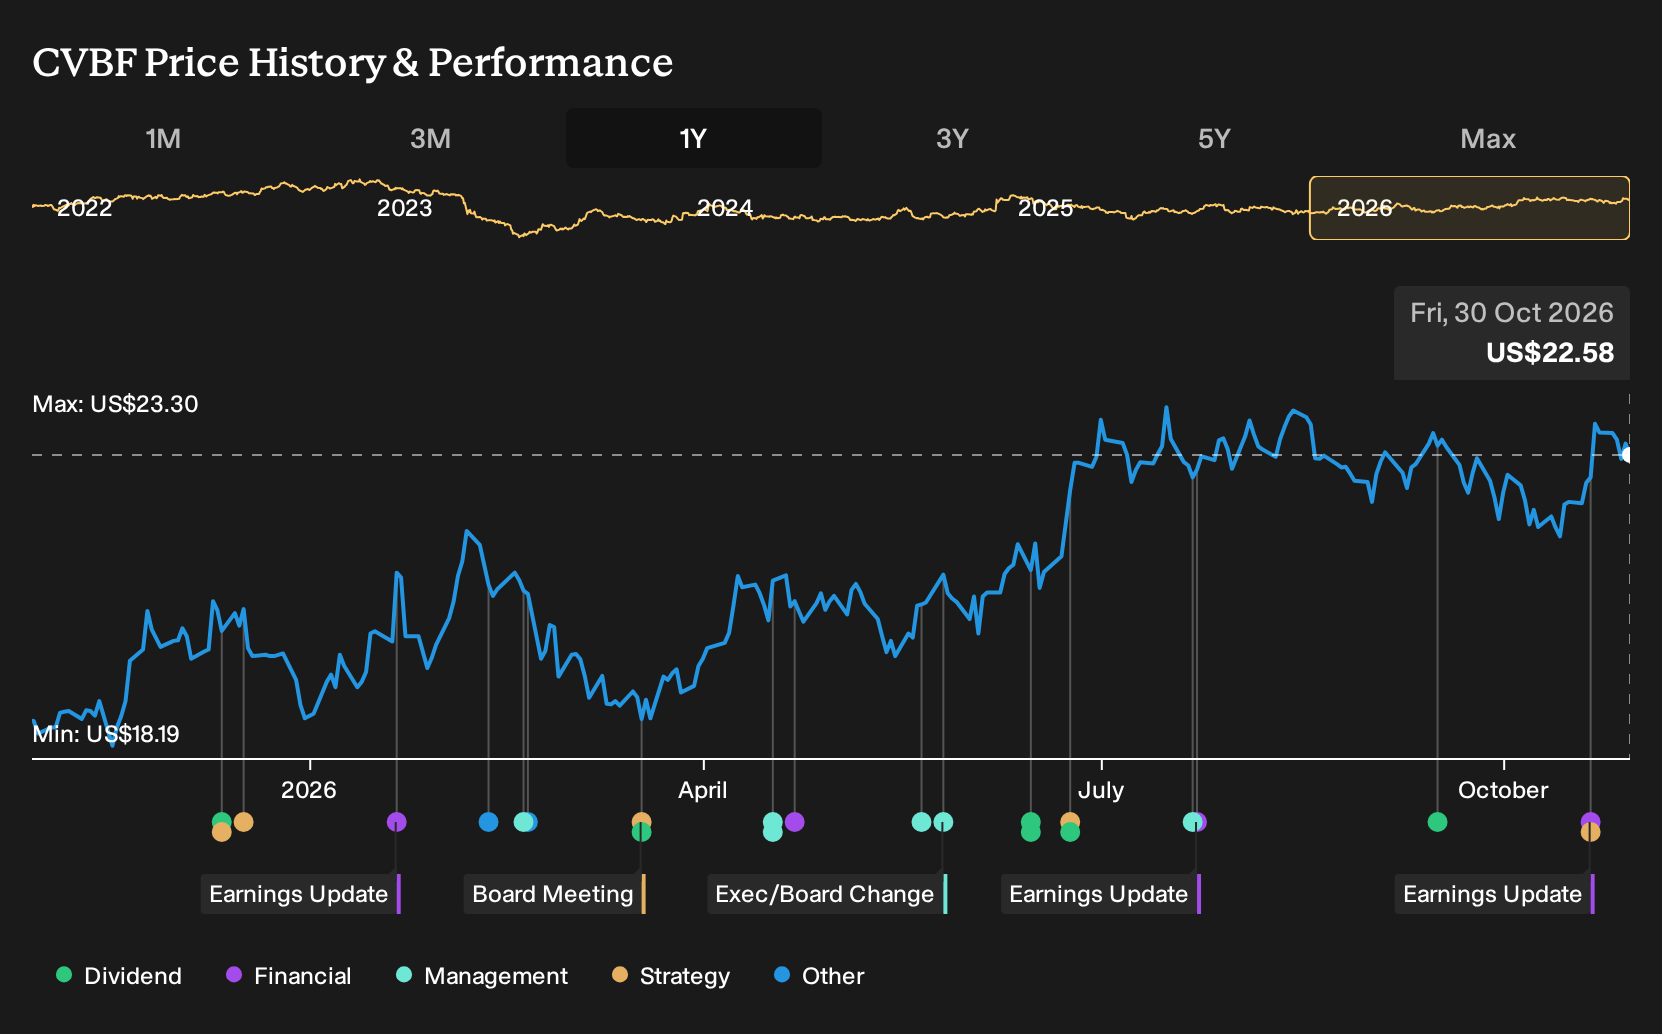
- CVB Financial reported third quarter 2026 net interest income of US$179.07 million and net income of US$78.1 million, alongside the completion of a US$22.58 million share repurchase covering 0.7% of shares outstanding.
- The combination of higher reported net interest income and earnings, together with active buybacks, reflects management’s confidence in the bank’s current earnings power and capital position.
- This article will now examine how CVB Financial’s reported quarterly results may influence its investment narrative and what that could imply for investors.
Look beyond CVB Financial’s latest earnings and buybacks by comparing it with a hand picked group of resilient bank and financial stocks in the 30 resilient stocks with low risk scores.
CVB Financial Investment Narrative Recap
For CVB Financial, the core belief is that a conservative, relationship focused California bank can convert a bigger balance sheet into steadier earnings per share over time. The third quarter showed higher net interest income of US$179.07 million and net income of US$78.1 million, which supports that thesis but does not change it. The near term story still hinges on keeping loan yields healthy while funding costs stay under control.
The biggest swing factor remains execution on integration and organic loan growth across the enlarged franchise. The key risk is that revenue momentum lags the added goodwill and intangibles from recent deals, which could leave return on equity and capital ratios under pressure. The latest quarter does not materially change that risk profile.
The most relevant recent development is the October 21 earnings release. It put clear numbers around how CVB Financial is tracking against its growth ambitions. For the quarter, net interest income was US$179.07 million versus US$115.58 million a year earlier, with net income of US$78.1 million compared with US$52.59 million.
Across the first nine months of 2026, net interest income reached US$459.32 million and net income was US$177.36 million. Earnings per share for that period stayed broadly similar to the prior year, which keeps attention on operational levers rather than financial engineering. That context helps frame the importance of future quarters as investors watch credit quality, including the very small US$20,000 of net charge offs in the third quarter, and the pace of integration benefits.
What CVB Financial’s Forecasts Expect From Here
Analysts are anchoring their view of CVB Financial on a multi year lift in both revenue and profitability. The current earnings base in the consensus model is US$205.6 million. Forecasts point to earnings of US$443.2 million and revenue of US$962.2 million by 2029, built on an assumed 18.9% yearly increase in revenue and a move in profit margins from 35.9% to 46.1% over the next three years.
CVB Financial's narrative projects US$962.2 million revenue and US$443.2 million earnings by 2029. This rests on 18.9% yearly revenue growth and an earnings increase of about US$237.6 million from US$205.6 million today.
Uncover why CVB Financial's fair value indicates a 15% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Community members on Simply Wall St have only two fair value estimates for CVB Financial so far, ranging from US$26 to about US$35.30, which signals a wide spread even in a tiny sample. You see that same gap in views outside the platform as investors weigh fresh buybacks, integration risks, and earnings targets. Use these contrasting perspectives as a prompt to test your own assumptions rather than relying on a single valuation number.
Explore another CVB Financial fair value estimate, including one that suggests there could be as much as 56% upside from the current price.
Decide For Yourself
Don't just follow the ticker, dig into the data and build a conviction that's truly your own.
- A great starting point for your CVB Financial research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for CVB Financial. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate CVB Financial's overall financial health at a glance.
Looking for more CVB Financial style investment ideas?
If CVB Financial has sharpened your sense of what you want from a bank or financial stock, use that same checklist to scan a wider universe of companies with the Simply Wall St Screener.
- For investors who care most about capital strength and staying power, start with a list of solid balance sheet and fundamentals (25 results) that can handle tougher conditions.
- If income is your priority, focus on payout resilience and growth potential through a hand picked set of 5 dividend fortresses designed for yield focused portfolios.
- When you want quality at a sensible entry point, broaden your watchlist with a 18 high quality undiscovered gems that match strong fundamentals with compelling valuations.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com