


Amaero (ASX:3DA) Shares Moved, So What Is Drawing Attention Now?
Amaero (ASX:3DA) has attracted fresh attention after recent trading left the share price at A$0.195. Investors are weighing this move against the company’s mixed share performance over the past year.
The recent 11.43% 1 month share price return contrasts with a year to date share price decline of 32.76%. The 1 year total shareholder return is down 25.00%, which points to some short term momentum in Amaero against a weaker longer record.
See how Amaero compares with other high potential small caps by reviewing our hand picked 15 high quality undiscovered gems before you decide how this momentum could fit in your portfolio.
Amaero’s recent bounce hints at renewed optimism, yet the longer track record tells a different story. Has the real upside already been taken, or does the current A$0.195 level still leave meaningful value on the table?
Most Popular Narrative: 75% Undervalued
The most followed valuation narrative puts Amaero’s fair value at A$0.79 per share against the current A$0.195 price. This is a wide gap that only really makes sense if the business delivers on some very specific growth drivers.
Accelerating reshoring of U.S. defense and industrial supply chains, including mission critical naval, missile and munitions programs, is pushing long duration contracts toward domestic powder and PM HIP capacity. This should support sustained revenue growth and greater visibility on future earnings.
See why 4 investors see Amaero as 75% undervalued.
Result: Fair Value of A$0.79 (UNDERVALUED)
Still, this narrative relies heavily on reshoring demand and a smooth capacity ramp up, so any delay or operational stumble could quickly challenge the current optimism.
Find out about the key risks to this Amaero narrative.
Another View On Amaero’s Valuation
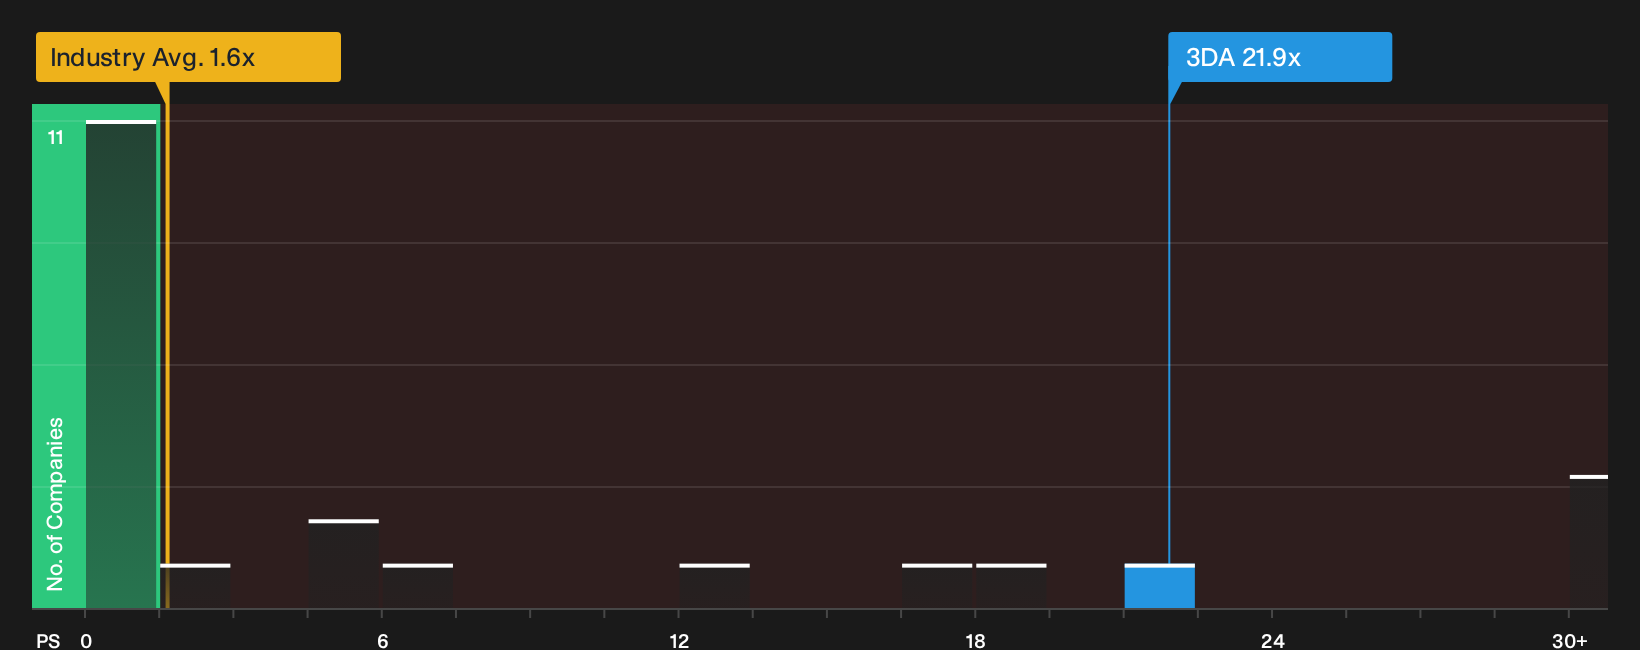
That A$0.79 fair value narrative leans heavily on future earnings. The current P/S ratio tells a very different story. Amaero trades on 18.8x sales, while peers sit near 4.8x and the fair ratio is estimated at 1.7x. That is a big valuation gap. Is the growth story strong enough to justify it?
Before leaning on those rich sales multiples, it is worth stress testing what would need to go right for Amaero to keep trading this far above both peers and the fair ratio. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of optimism and concern around Amaero leaves you on the fence, move quickly and interrogate the data yourself so your view is evidence based. To weigh both sides in one place, start with the 1 key reward and 2 important warning signs.
Looking for more investment ideas beyond Amaero?
If Amaero has sharpened your thinking, do not stop here. Broader opportunities often sit just outside the names already on your radar.
- Target potential value gaps and let the data guide you toward companies that may trade below their fundamentals with our 1 high quality undervalued stocks.
- Prioritise resilience by scanning for businesses with strong finances and healthier balance sheets using the list of solid balance sheet and fundamentals (12 results).
- Spot potential future favourites early by filtering for lesser known opportunities that still show robust fundamentals through the 15 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com