


Cushman & Wakefield (CWK) Just Drew Fresh Attention, What Is The Market Weighing?
Cushman & Wakefield (CWK) just made a targeted hire in data center real estate, bringing back industry veteran Mark Bauer and his specialist team to deepen its digital infrastructure advisory platform.
Recent hiring moves around data centers and regional project leadership have landed while Cushman & Wakefield’s share price trades at US$13.30, with a 7 day share price return of 12.43% and a year to date share price decline of 16.04%.
Scan how Cushman & Wakefield’s data center push compares with other digital infrastructure plays by checking the hand picked 54 AI infrastructure stocks on Simply Wall St.
Cushman & Wakefield now has a deeper story on the business side, from data centers to project services, while the share price is still down year to date. Does that combination add up to value or a value trap?
Most Popular Narrative: 22% Undervalued
The most followed valuation narrative puts Cushman & Wakefield’s fair value at $17, above the recent $13.30 share price, and links that gap to how the business is leaning into higher value services.
The main thing that has to go right is that Cushman & Wakefield continues to grow higher value services such as data center related work and project management while maintaining operating efficiency and balance sheet discipline.
High client retention and recurring services are now complemented by rapid growth in higher value offerings such as data center work. Revenue in this area was up 83% year to date by Q2 2026 and a quarter of the integrated facilities management pipeline is data center related, which together point to a mix shift that can support recurring revenue and cash flow.
See why 2 investors see Cushman & Wakefield as 22% undervalued.
Result: Fair Value of $17 (UNDERVALUED)
Still, Cushman & Wakefield’s reliance on cyclical leasing and capital markets fees, along with ongoing legal exposure around Pinnacle, could easily challenge that undervaluation story.
Find out about the key risks to this Cushman & Wakefield narrative.
Another View: Cushman & Wakefield Through Earnings Multiples
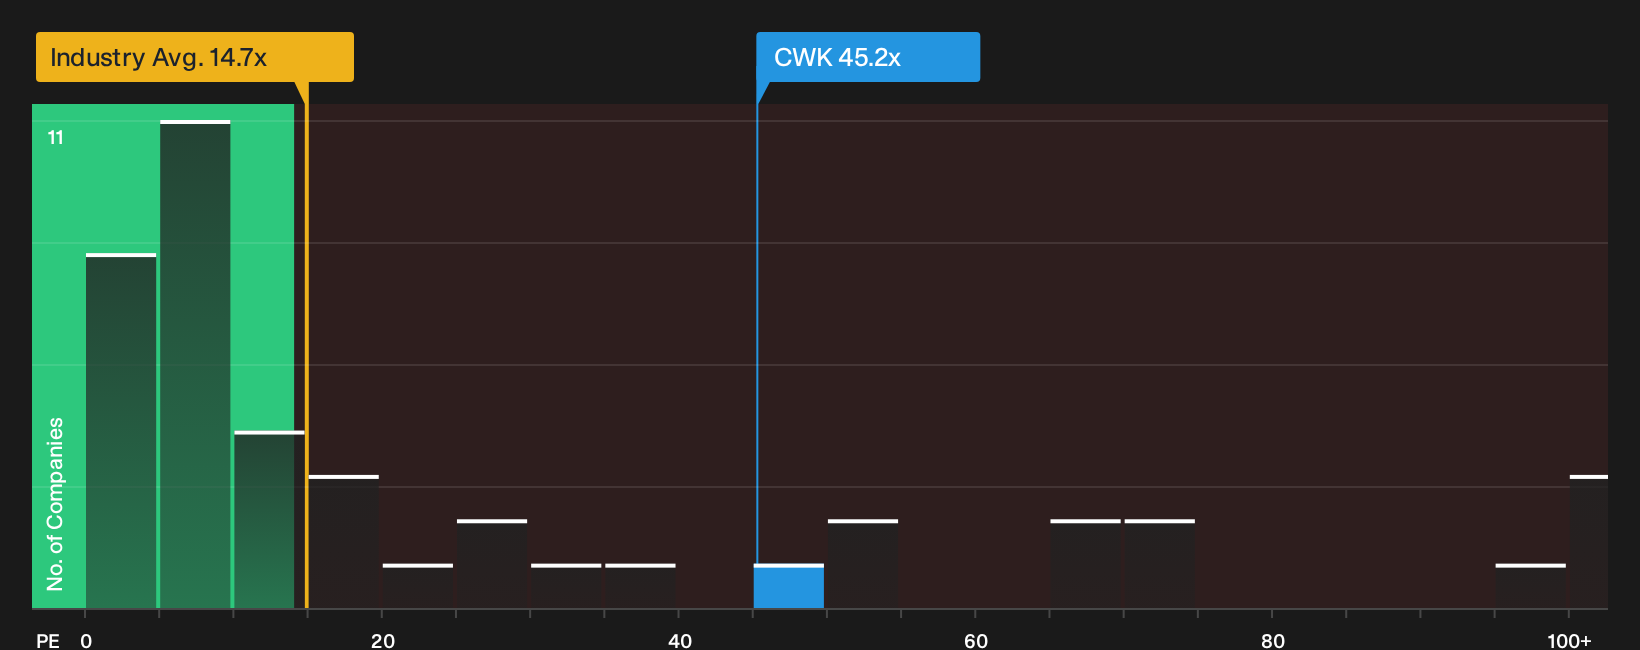
The DCF style fair value of $31.35 presents Cushman & Wakefield as heavily undervalued, yet the current P/E of 45.2x tells a different story when compared with a fair ratio of 31.1x and a US Real Estate industry average of 14.7x. That gap suggests investors are paying up for earnings today. How comfortable are you with that kind of valuation risk if sentiment turns?
To put that earnings based view in context, take a closer look at how the numbers stack up in our valuation breakdown, then compare it with other stocks on similar metrics See what the numbers say about this price — find out in our valuation breakdown.
Use the valuation charts to see where Cushman & Wakefield sits on a simple relative basis versus peers and the wider sector
Next Steps
If this combination of risks and rewards around Cushman & Wakefield appears finely balanced, consider acting while sentiment is still taking shape and weigh the 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Cushman & Wakefield?
Do not stop at Cushman & Wakefield if you want a broader watchlist. Use the screener to uncover fresh ideas that match your risk and income preferences.
- Target quality at a discount by scanning a curated pool of companies judged to be trading below estimated value with the 29 high quality undervalued stocks.
- Build a steadier income stream by focusing on companies with robust payouts and higher yields using the 5 dividend fortresses.
- Dial back portfolio risk by filtering for companies with stronger balance sheets and fundamentals through the list of solid balance sheet and fundamentals (25 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com