


Learn Why The Bull Case For Triumph Financial Stock Could Change Following Stronger Earnings
- Triumph Financial reported third quarter 2026 net interest income of US$103.13 million and net income of US$13.43 million, with basic earnings per share from continuing operations of US$0.53.
- Over the first nine months of 2026, Triumph Financial’s net income reached US$31.15 million while basic earnings per share from continuing operations was US$1.21. This highlights how profit levels compared with the prior year period now shape the company’s operating story.
- We will now assess how Triumph Financial’s stronger third quarter net income influences its investment narrative, which is built around transportation focused financial services.
Triumph Financial Investment Narrative Recap
To own Triumph Financial, you need to believe the transportation focused factoring, payments and intelligence ecosystem can keep gaining relevance relative to its traditional banking arm. The latest quarter shows net interest income and net income that support this thesis, but the short term hinge still looks like freight volumes and invoice values that affect transportation activity.
The biggest near term risk remains exposure to trucking cycles and to a banking segment that has already faced pressure. The strong third quarter does not fully resolve these issues. It does, though, give management a little more room to keep shifting the mix toward higher margin fintech and data offerings.
The key fresh data point for this story is the third quarter 2026 earnings release itself. Triumph Financial reported net interest income of US$103.13 million and net income of US$13.43 million, with basic earnings per share from continuing operations of US$0.53. For an investor, those figures frame how much earnings power currently comes from interest based activities.
Viewed over the first nine months of 2026, net income of US$31.15 million and basic earnings per share from continuing operations of US$1.21 give a clearer picture of year to date profitability. That context matters for catalysts like automation in factoring, payments repricing and the slower Intelligence segment, because execution on those fronts will shape how durable this earnings level proves to be.
Triumph Financial's current analyst narrative points to forecast revenue of US$589.1 million and earnings of US$116.9 million by 2029, based on expectations of 9.0% yearly revenue growth and an earnings increase of roughly US$81.5 million from about US$35.4 million today.
Uncover how Triumph Financial's fair value indicates a 21% potential upside to its current price before the discount to Triumph Financial’s earnings power closes.
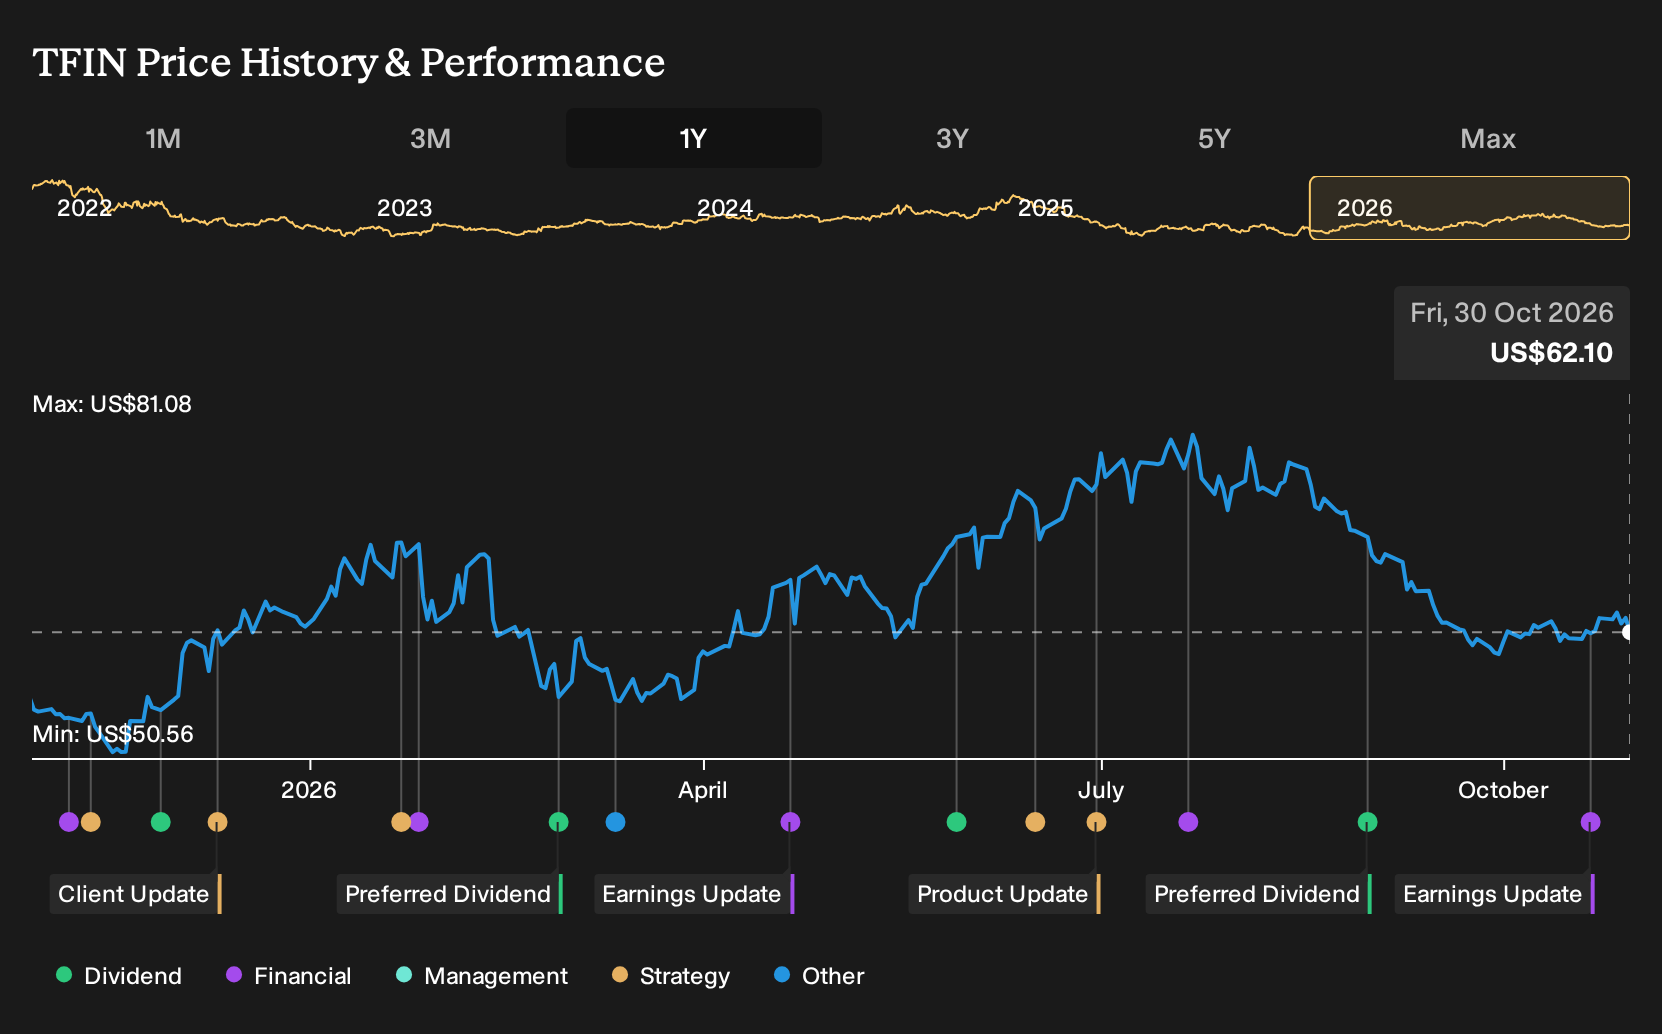
Exploring Other Perspectives
Some of the most optimistic analysts focus on Triumph Financial’s cross sell catalyst. They saw the freight platform reaching about US$611.7 million in revenue and US$149.8 million in earnings by 2029 before this earnings report, far above consensus. That gap shows how sharply opinions can differ and why you may want to compare several narratives as new results arrive.
Explore another Triumph Financial fair value estimate, including one that suggests as much as 21% upside from the current price!
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Triumph Financial research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Triumph Financial. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Triumph Financial's overall financial health at a glance.
Looking For More Investment Ideas Beyond Triumph Financial?
Once you have formed a view on Triumph Financial, it can help to line it up next to other opportunities that fit different goals, whether you care more about value, stability, or future income. The Simply Wall St Screener lets you do that quickly by filtering for specific traits across the wider market.
- If you want potential value with quality fundamentals, compare Triumph Financial against companies in the 29 high quality undervalued stocks that combine stronger cash flows with disciplined balance sheets.
- For readers focused on resilience over excitement, weigh Triumph Financial beside businesses in the 30 resilient stocks with low risk scores that score well on financial strength and risk controls.
- Income oriented investors can set Triumph Financial alongside high yield candidates in the 5 dividend fortresses that target stronger and more consistent cash returns to shareholders.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com