


Teradata (TDC) Pushes AI Sovereignty And Security While Valuation Stays In Focus
Teradata (TDC) has put data sovereignty and AI security at the center of its latest product push, rolling out new deployment options, privacy controls, and cyber resiliency tools aimed at heavily regulated sectors.
Teradata shares have pulled back slightly in the past week, with a 7-day share price return of a 1.8% decline, following a strong 30-day share price return of 18.8% and a year-to-date share price gain of 15.4% that suggests momentum has picked up around these AI and sovereignty launches. Over a longer horizon the picture is mixed, with a 1-year total shareholder return of 64.3% set against 3-year and 5-year total shareholder returns that declined 23.0% and 29.9% respectively, which indicates that recent enthusiasm may be rebuilding confidence after a tougher multi year stretch.
Scan beyond Teradata to identify additional AI infrastructure players that are strengthening security and data sovereignty by running a focused search across 54 AI infrastructure stocks in one place.
Teradata’s sharp recent rebound sits against a much tougher three and five year record, which raises a simple question. Is this re‑rating really about the business, or mostly about sentiment catching up to the AI story?
Most Popular Narrative: 2% Overvalued
Teradata last closed at $34.25 against a narrative fair value of $33.50, which suggests only a small valuation premium while expectations for its AI transition stay tightly constrained by cautious earnings forecasts.
The combination of higher recurring gross margins around 70%, year to date non GAAP operating margins in the mid 20s, and a plan to return around half of adjusted free cash flow through buybacks after becoming debt free, supports a case that Teradata can keep earnings and free cash flow resilient even as it redirects operating expense into AI.
See why 10 investors see Teradata as 2% overvalued.
Result: Fair Value of $33.50 (OVERVALUED)
Still, shrinking consulting revenue and guided declines in near term recurring revenue could chip away at confidence in Teradata’s AI execution story.
Find out about the key risks to this Teradata narrative.
Another View: Teradata Through The Earnings Lens
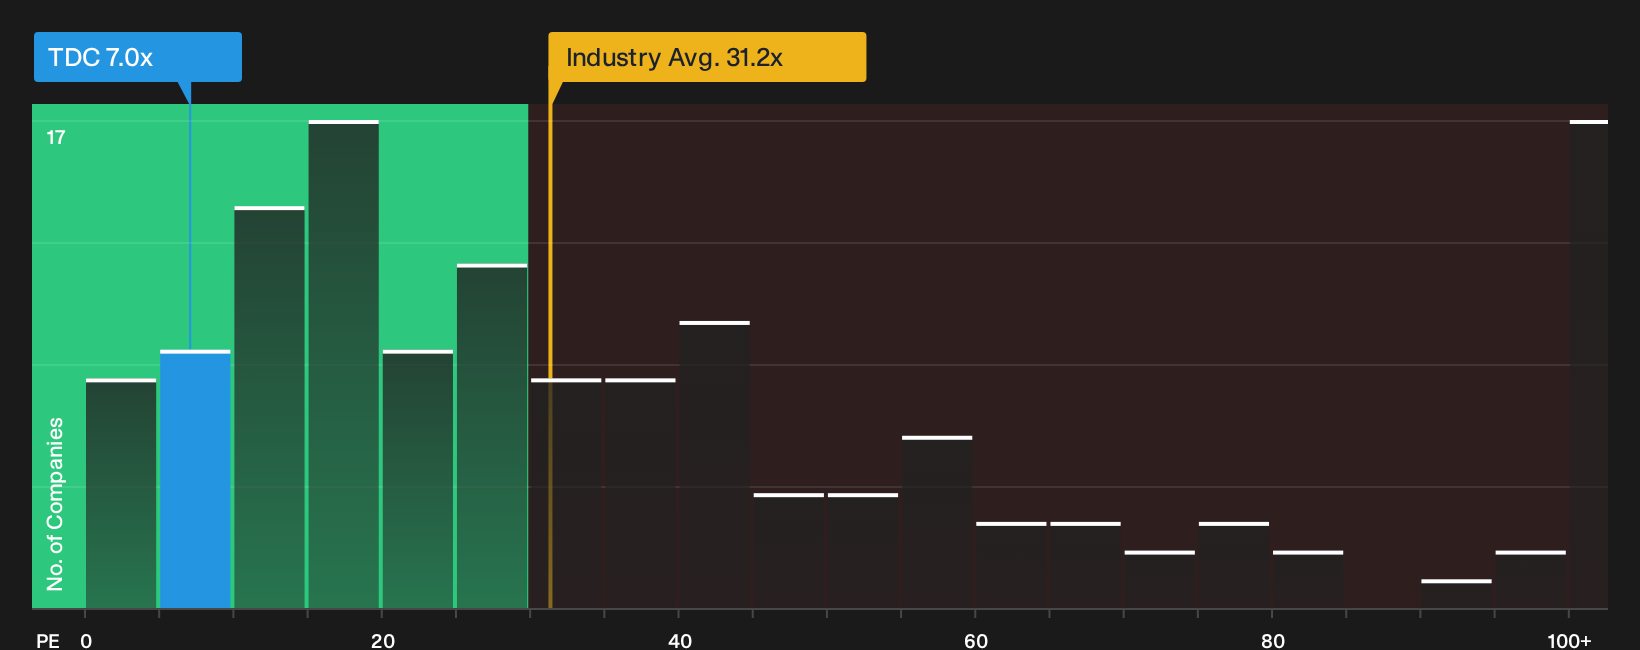
The first take framed Teradata as slightly overvalued versus a $33.50 fair value, based on cautious earnings forecasts. Looking at the current P/E instead tells a very different story. The shares trade at about 7x earnings, compared with roughly 31x for the US software group and a peer average near 27x.
That gap is also wide against an estimated fair ratio of 11.1x, which is where the multiple could drift if sentiment moved closer to the model. For investors, such a discount can either signal a margin of safety if earnings hold up, or a market that still questions how durable those profits really are.
Before leaning on that low multiple either way, it is worth seeing what the detailed valuation breakdown implies for risk and upside in plain numbers, not headlines, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Teradata’s valuation and execution only matter if you use them to sharpen your own judgment. Move quickly and weigh both sides of the story against the 3 key rewards and 2 important warning signs.
Looking For More Ideas Beyond Teradata?
If Teradata has sharpened your thinking, do not stop here. Use focused screeners to quickly surface other opportunities that might better fit your portfolio.
- Target steadier opportunities by reviewing companies with resilient risk profiles through the 30 resilient stocks with low risk scores.
- Hunt for potential bargains by checking companies that appear attractively priced on fundamentals using the 29 high quality undervalued stocks.
- Spot financially grounded businesses by scanning a list of solid balance sheet and fundamentals (25 results) before capital moves to the next idea.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com