


Is SI-BONE (SIBN) Below Fair Value On Its Recall Driven Selloff?
SI-BONE (SIBN) is in focus after a voluntary Class II recall of specific iFuse TORQ Implant System screws, following US FDA findings that packaging seal integrity tests did not meet sterility standards.
The recall news has affected short term sentiment, with the 1 day share price return down 5.09%. However, SI-BONE still shows a 30 day share price return of 13.14% and a 90 day share price return of 19.76%, while the 1 year total shareholder return is 43.43%. This suggests momentum has been building over the past year despite recent volatility.
Scan how investors are reacting to the SI-BONE recall and compare it with other healthcare stocks showing strong price action and balance sheets through the list of solid balance sheet and fundamentals (25 results).
After a sharp run over the past year and a fresh hit from the recall, SI-BONE now sits at an awkward middle ground. Does the current valuation still compensate you for the quality and execution risk on the table?
Most Popular Narrative: 6% Overvalued
Against the last close of $21.27, the most followed narrative anchors SI-BONE’s fair value at $20.00. The recall therefore arrives with a stock already priced slightly above that mark and a lot riding on how efficiently the business turns high gross margins into lasting earnings.
The main factor that needs to work in SI-BONE's favor is converting its high gross margins, expanding active physician base, and broader compromised-bone platform into sustained procedure growth and rising utilization per physician, while avoiding a situation in which ASP pressure and added surgical capacity costs erode profitability.
See why 2 investors see SI-BONE as 6% overvalued.
Result: Fair Value of $20.00 (OVERVALUED)
Still, if SI-BONE keeps gross margins near current levels and active physicians use more of the platform, the bearish fair value anchor could be challenged.
Find out about the key risks to this SI-BONE narrative.
Another View: SIBN Through The SWS DCF Lens
The bearish $20.00 narrative frames SI-BONE as modestly overvalued, yet the SWS DCF model points in a very different direction. At a last close of $21.27, the shares trade about 45.3% below an estimated future cash flow value of $38.89, which implies the cash generation story looks much stronger than the multiple based view. Which lens do you trust more for a recall hit, high gross margin medtech like this?
Look into how the SWS DCF model arrives at its fair value.
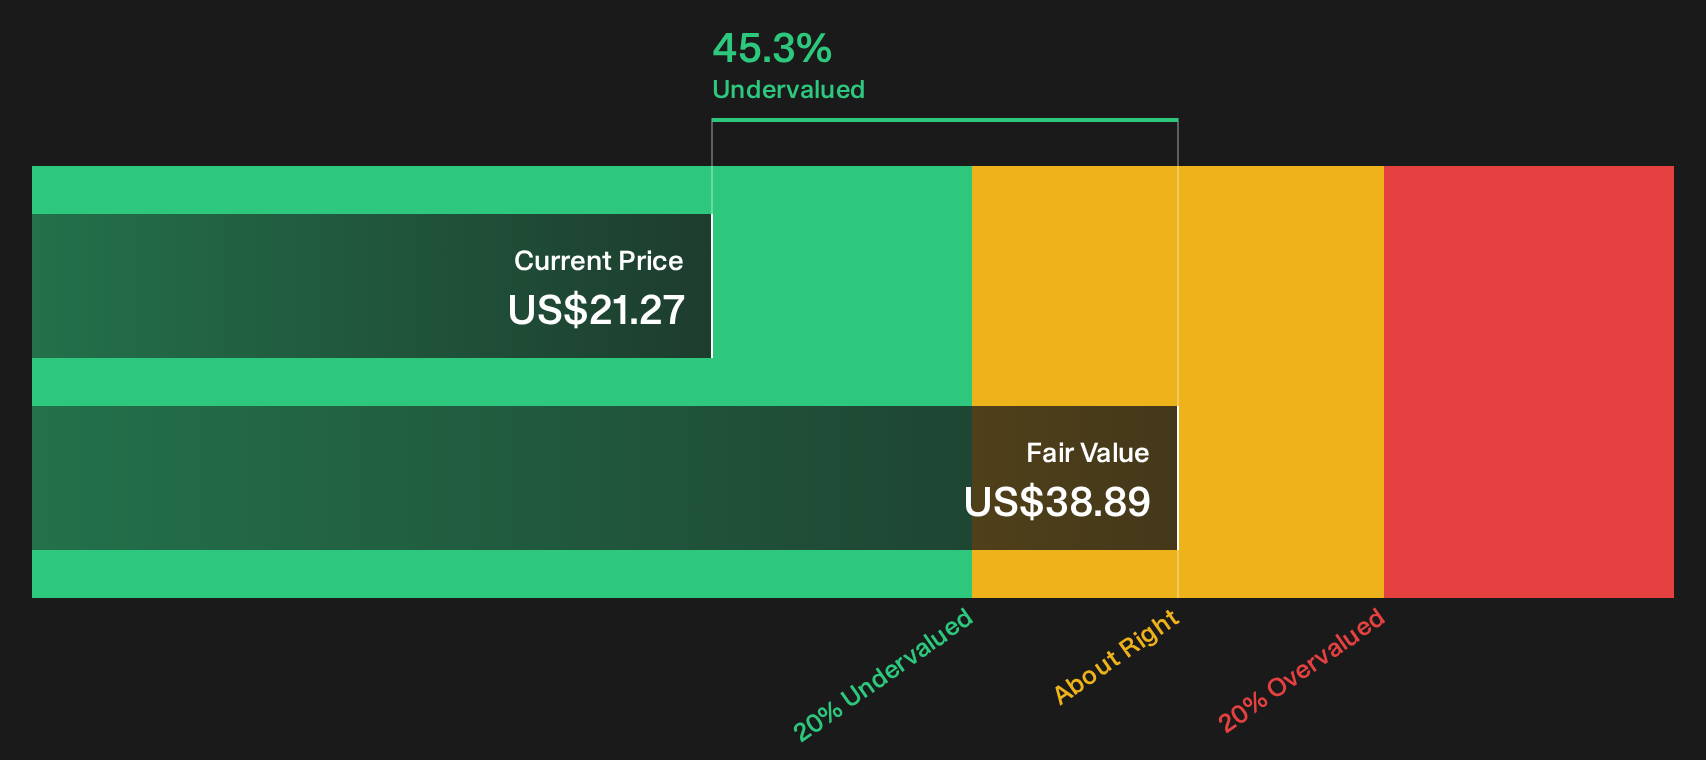
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out SI-BONE for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on SI-BONE so far, right? Consider your options while sentiment is still forming and weigh both sides of the story through the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond SI-BONE?
If SI-BONE has you thinking harder about risk, reward, and timing, use that momentum and pressure test a few fresh ideas before the next headline hits.
- Spot potential bargains early and compare quality across sectors using the 18 high quality undiscovered gems so you are not only chasing what already moved.
- Prioritise resilience by checking companies with stronger financial footing through the 30 resilient stocks with low risk scores and give your portfolio a more stable core.
- Hunt for businesses combining robust balance sheets with solid fundamentals using the list of solid balance sheet and fundamentals (25 results) before the crowd shifts attention their way.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com