


Curbline Properties (CURB) Lifts FFO Outlook, Is A 16% Undervalued View Still Justified?
Curbline Properties (CURB) just raised its full year operating funds from operations guidance, while net income expectations edged lower, putting the focus on cash generation, acquisitions and the leasing pipeline after its latest earnings release.
Recent trading shows that momentum in Curbline Properties has cooled near the latest share price of $28.53, with the stock down over the past week and quarter but still posting a 23.35% year to date share price return and a 27.01% total shareholder return over the last 12 months.
Spot 29 high quality undervalued stocks that, like Curbline Properties, pair active acquisition plans and cash focused metrics with what could be a more conservative market valuation.Curbline Properties has cooled off after a strong run, just as funds from operations guidance moved higher and net income guidance ticked down. Is this the moment to step in, or is it better to wait for a cheaper entry point later on?
Most Popular Narrative: 16% Undervalued
Curbline Properties last closed at $28.53, while the most followed narrative pegs fair value at $33.94. This frames the recent pullback against a higher long term valuation anchor.
Underlevered balance sheet with net debt to EBITDA below 1 times and over $250 million of cash on hand enables Curbline to fund roughly $750 million of annual investments at attractive cap rates, creating meaningful acquisition driven FFO per share growth with limited financing risk.
See why 1 investors see Curbline Properties as 16% undervalued.
Result: Fair Value of $33.94 (UNDERVALUED)
Still, the narrative around Curbline Properties can be shaken if acquisition yields compress, or if shorter leases translate into higher turnover and weaker same property NOI.
Find out about the key risks to this Curbline Properties narrative.
Another View: Rich Multiples For Curbline Properties
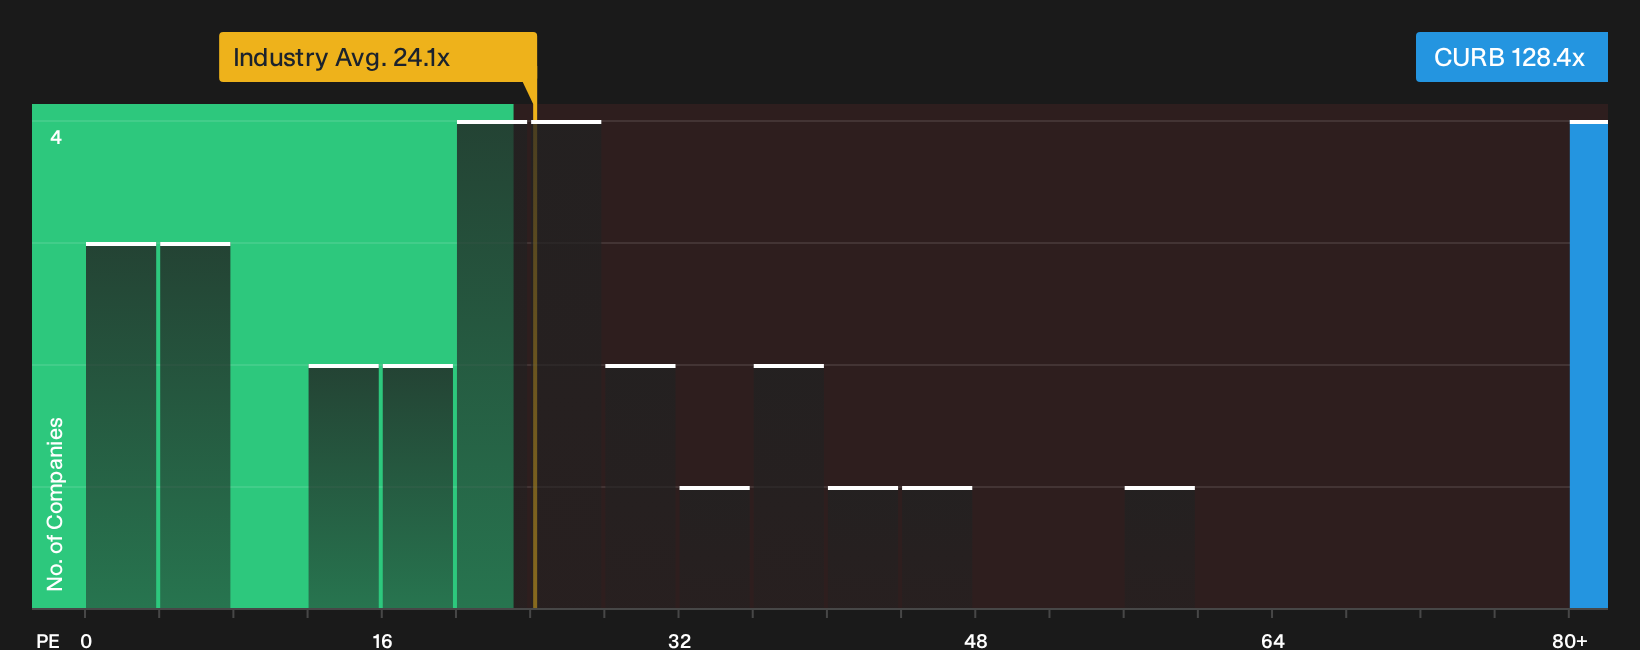
There is a very different message coming from simple market ratios. Curbline Properties trades on a P/E of 128.4x, compared with 25.3x for the US Retail REITs group and 54.5x across closer peers. The fair ratio sits at 43.9x, which points to meaningful valuation risk if sentiment cools.
That gap raises a practical question for investors. Is the current price rewarding future growth too early, or is this simply the cost of owning a high conviction story at this stage of its life cycle, especially when cheaper peers are available?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on valuation and earnings quality can be confusing, so move quickly to review the data, pressure test your own thesis, and then weigh Curbline Properties against the 2 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Curbline Properties?
If Curbline Properties has your attention, do not stop there. Fresh ideas often sit just outside your current watchlist, and skipping them can mean missed opportunities.
- Target resilient income by reviewing stocks that offer reliable yield profiles through the 5 dividend fortresses.
- Hunt for quality at a discount by scanning companies flagged in the 18 high quality undiscovered gems.
- Prioritize capital protection by focusing on businesses highlighted in the 30 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com