


Is Golar LNG (GLNG) Trading At A Premium For Its Earnings?
Golar LNG has delivered a powerful long term share price run, which naturally raises a question for anyone looking at the stock today. Do the company’s earnings still provide enough support for the current valuation after such a strong climb?
- Over the past 5 years the share price has gained about 280.6%, which puts a lot of pressure on the earnings story to justify where the stock now trades.
- The business model leans heavily on converting projects into steady cash generation, so the durability and timing of earnings can be just as important as headline profit growth for how you think about value.
- The analysts covering Golar LNG have run their own numbers. See what analysts think Golar LNG's shares could be worth.
The issue now is whether Golar LNG’s current share price is appropriately supported by the earnings it is generating today.
If you want to test the same earnings question across other companies, run the numbers on 29 high quality undervalued stocks and compare how solid cash generation lines up with current market prices.
Where Does Golar LNG Sit on Earnings?
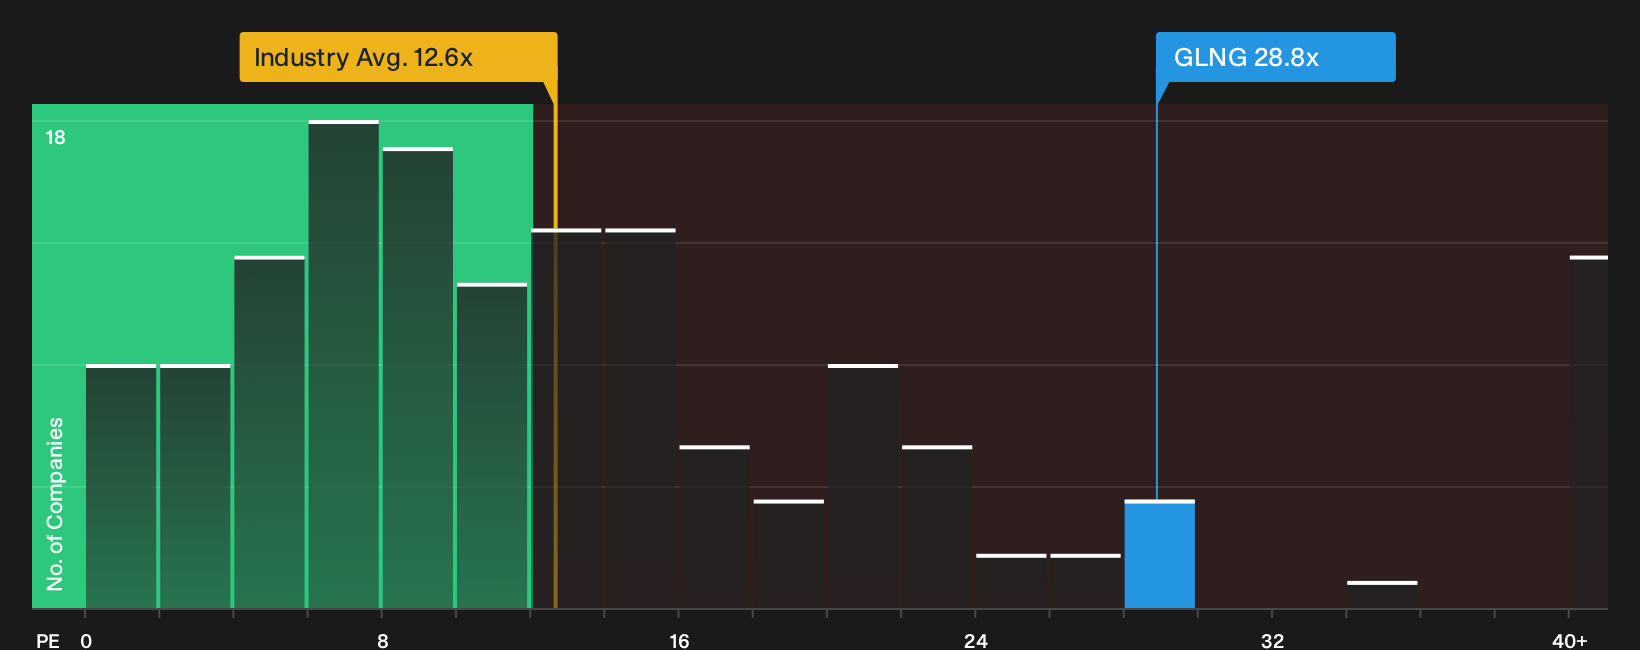
A P/E lens fits Golar LNG because the market is clearly weighing current earnings against a long track record of price gains. The stock trades on a P/E of roughly 28.8x, while the wider Oil and Gas sector averages about 12.6x and close peers cluster around 12.8x. That is a large step up in what investors are paying for each dollar of reported profit.
The fair-value model suggests a P/E level that already assumes Golar LNG deserves a premium to simple sector and peer averages, and the current multiple sits close to that implied range rather than far above it. For a holder, the key question is whether the quality and durability of these earnings justify paying close to this tailored fair mark or whether a lower entry point feels more appropriate for the risk. Explore the numbers behind Golar LNG's P/E valuation.
The Golar LNG Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where this valuation puzzle for Golar LNG leaves off by spelling out which paths for growth, profitability and earnings would need to play out for the shares to look materially higher or lower than today’s price. Each scenario ties its number to a clear view on how Golar LNG's future revenue mix, margins and risk profile might shift, giving you something concrete to revisit as fresh information comes through.
One of the top community narratives on Golar LNG: 30% undervalued
"The current valuation implies investors are pricing Golar LNG below the earnings power suggested by its roughly $17b EBITDA backlog and plans to grow contracted FLNG capacity…"
Discover why this Narrative puts Golar LNG at 30% undervalued.
The Golar LNG share price is only one piece of the decision
Valuation tells you what the market is paying today, but analyst projections for Golar LNG a few years down the line give you a different lens on where expectations already sit. Explore where analysts expect Golar LNG to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com