


Is Knowles (KN) Undervalued After Strong Earnings And 2026 Guidance?
How Knowles Earnings And Guidance Are Shaping Investor Focus
Knowles (KN) put fresh numbers on the table with its third quarter report and new outlook for the rest of 2026. Sales, profits and earnings per share all moved higher year over year, and management is now projecting full year revenue of about US$689 million, which it expects to be 16% above 2025 levels.
The guidance sparked a sharp reaction in the market, with Knowles’ share price falling 6.01% on the day to US$32.87, even though the year to date share price return is up 49.75% and the 3 year total shareholder return is 104.93%. This points to strong long term momentum despite recent volatility.
Spot emerging trends around Knowles by scanning hand-picked peers with strong fundamentals in our 18 high quality undiscovered gems.Bulls point to Knowles' earnings progress and 2026 guidance. Bears see a stock that has already run hard and just dropped 6%. Which side does the current valuation argue for next?
Most Popular Narrative: 25% Undervalued
Knowles is trading at $32.87 against a widely followed fair value estimate of $44, so the central question is whether investors agree that its booked work and product ramps really support that gap.
The ramp of the US$75 million plus energy order on the specialty film line, combined with capacity additions across most Precision Devices product lines that are expected to be fully available in the second half of 2027, should lift factory utilization and support higher gross margins and EBITDA over time.
See why 2 investors see Knowles as 25% undervalued.
Result: Fair Value of $44 (UNDERVALUED)
Still, Knowles investors need to be watching two pressure points closely: execution on the specialty film ramp and any slowdown that crimps utilization on new capacity.
Find out about the key risks to this Knowles narrative.
Another Angle On Knowles Valuation
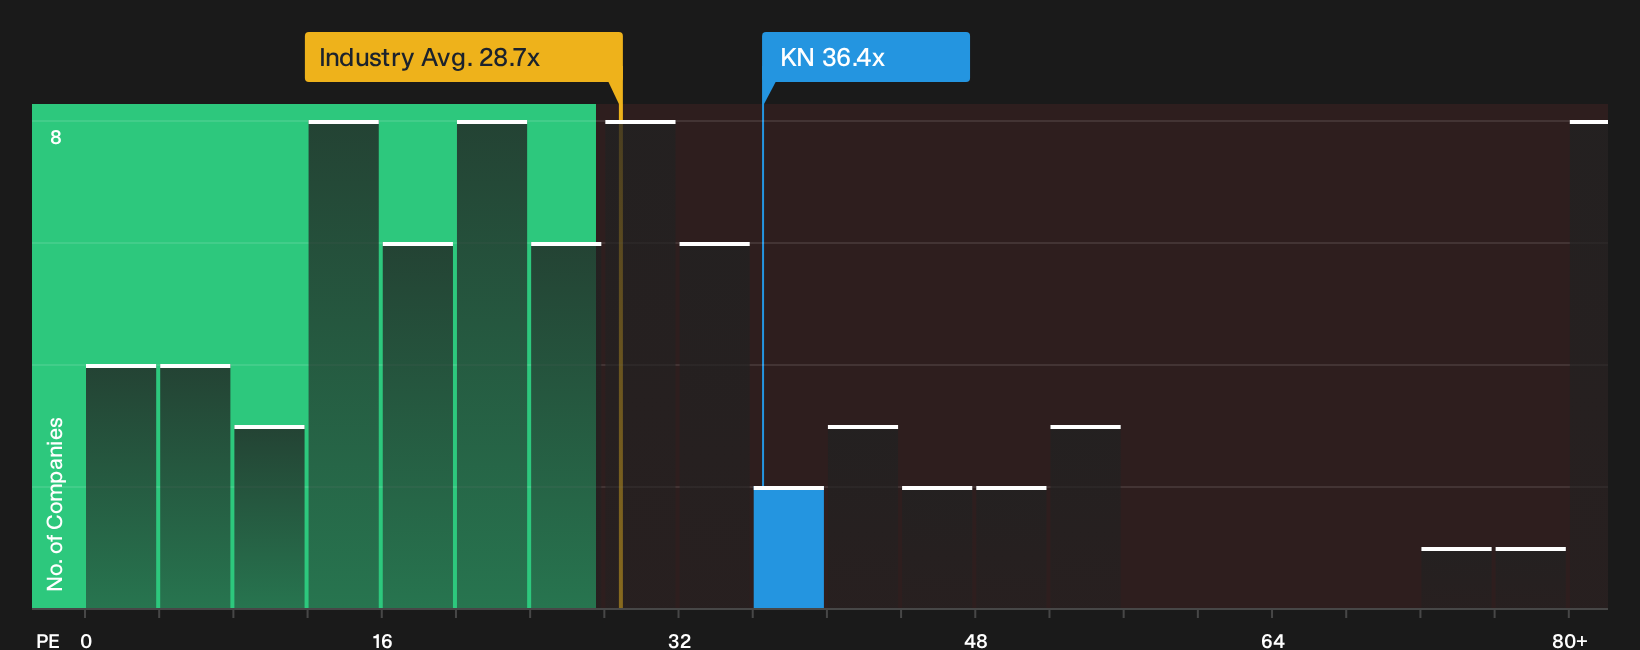
Some analysts view Knowles as trading 25% below their US$44 fair value, while the current P/E of 36.4x sits above both the US Electronic industry at 30.1x and a fair ratio of 26.4x. That gap indicates comparatively higher expectations. Whether the company narrative can continue to justify this premium is a key question for investors.
For a closer look at how those earnings expectations compare with the current price, and how the ratio might change as sentiment shifts, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Knowles is split, so do not wait for consensus before checking the numbers and pressure points yourself and deciding what feels justified for your own risk tolerance. To see what optimistic investors are focusing on, review the 3 key rewards.
Looking For More Investment Ideas Beyond Knowles?
If Knowles has your attention, do not stop there. Broaden your watchlist with other clear setups where quality, price and risk all line up.
- Target potential mispricing by scanning companies that combine solid fundamentals with room for a re‑rating using the 29 high quality undervalued stocks.
- Strengthen your defensive side by reviewing a list of solid balance sheet and fundamentals (25 results) so you are not caught off guard when conditions get tougher.
- Lock in your income watchlist early by tracking a curated pool of 5 dividend fortresses before others crowd into the same ideas.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com