


Loblaw Companies (TSX:L) Opens Buffalo Run Store On A Narrative Of Fair Value
The opening of a new Real Canadian Superstore at Buffalo Run on Tsuut’ina Nation on November 26, 2026 puts Loblaw Companies (TSX:L) back in focus for investors watching community led expansion.
Recent trading points to steady interest in Loblaw Companies, with a 1 month share price return of 11.04% at a current level of CA$69.07. The 1 year total shareholder return of 25.09% and 5 year total shareholder return above 200% indicate that longer term holders have seen substantially stronger gains than short term traders.
Scan beyond Loblaw Companies and this Buffalo Run opening to see how other consumer and retail players with solid balance sheets are lining up in our list of solid balance sheet and fundamentals (6 results)
Loblaw Companies has just logged a strong recent run, so the real tension now is simple. Is this a fair entry point, or does patience for a cheaper price make more sense before committing fresh capital?
Most Popular Narrative: 3% Undervalued
The most followed valuation story pegs Loblaw Companies at a fair value of CA$70.91, a touch above the CA$69.07 last close. This puts today’s move at Buffalo Run into a bigger picture built around discount banners, pharmacy strength and capital discipline.
Loblaw Companies is accelerating new store openings to roughly 75 locations in 2026, with about half in food and mostly hard discount formats and half in Shoppers Drug Mart. This extends its reach into value oriented small boxes and additional pharmacy sites and supports future revenue and earnings growth as these stores mature.
See why 49 investors see Loblaw Companies as 3% undervalued.
Result: Fair Value of CA$70.91 (UNDERVALUED)
Still, the Loblaw Companies story can be knocked off course if political pressure on food pricing tightens margins or if newer pillars such as digital commerce and GLP 1 driven pharmacy profit trail optimistic expectations.
Find out about the key risks to this Loblaw Companies narrative.
Another View: Cash Flows Paint A Tougher Picture
The analyst narrative points to Loblaw Companies trading around fair value on earnings at CA$69.07 against a CA$70.91 target. The SWS DCF model tells a different story. On projected future cash flows, it suggests fair value closer to CA$50.82, which frames the stock as overvalued instead of modestly undervalued.
That kind of gap between an earnings based view and a cash flow based estimate raises a practical question for investors. Which set of assumptions feels more realistic for Loblaw Companies over the next decade: the profit trajectory implied by the analyst target, or the more cautious cash flow path behind the DCF number.
Look into how the SWS DCF model arrives at its fair value.
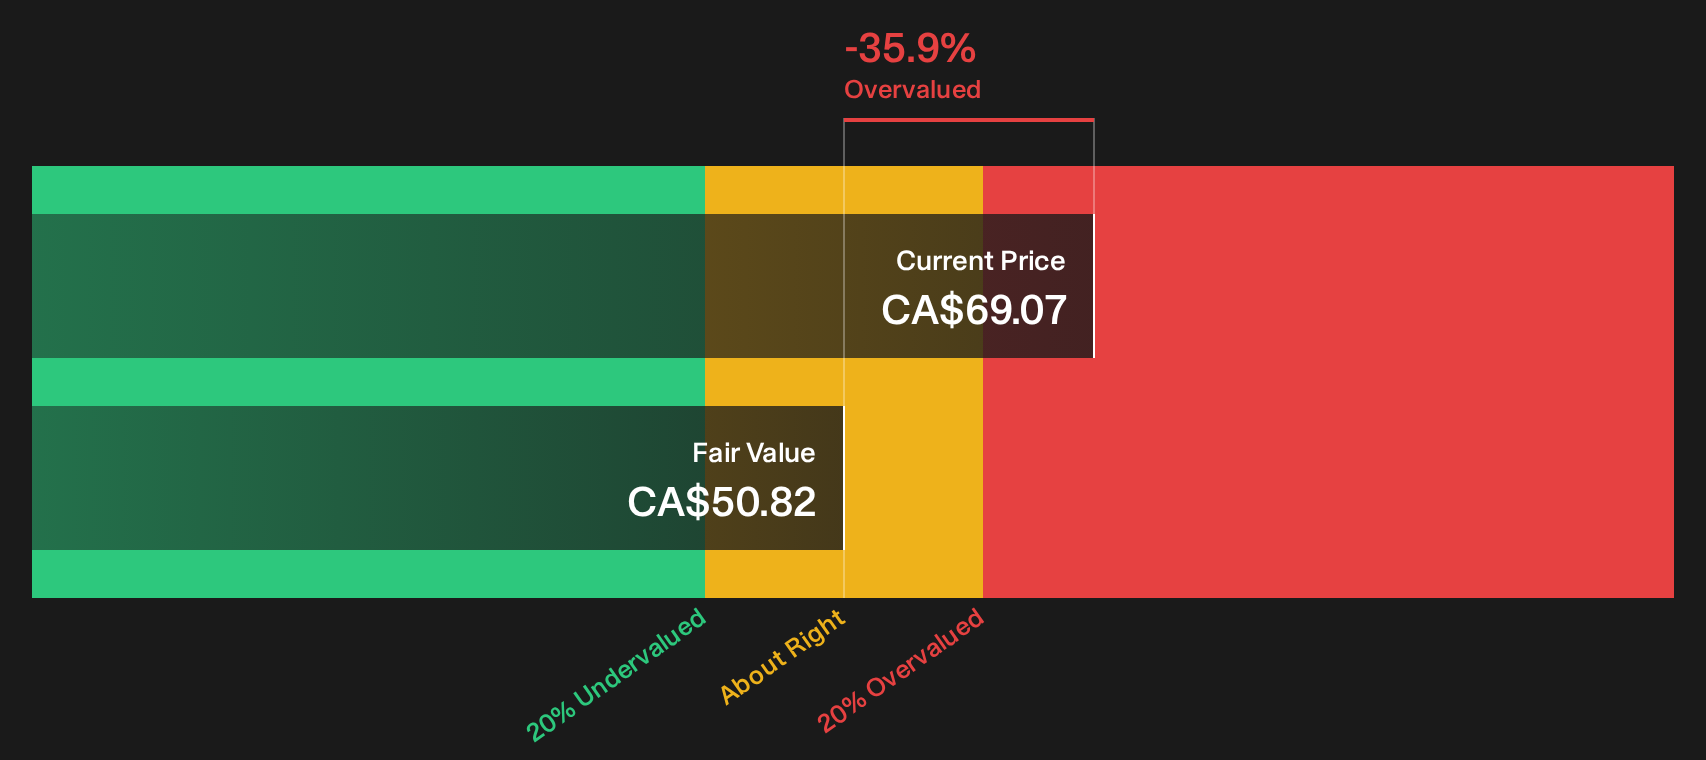
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Loblaw Companies for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 3 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If this mix of optimism and concern around Loblaw Companies feels familiar, do not wait for someone else to settle the argument for you. Weigh the upside against the weak spots and stress test your own thesis with the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Loblaw Companies?
If Loblaw Companies has sharpened your appetite for opportunity, do not stop here. Broaden your watchlist with focused stock ideas built from data driven screeners.
- Target value focused opportunities by reviewing our list of 3 high quality undervalued stocks that pair quality fundamentals with prices that may not fully reflect them yet.
- Strengthen your income stream by scanning 3 dividend fortresses that combine higher yields with business models built around consistent shareholder payouts.
- Dial down portfolio risk by working through 7 resilient stocks with low risk scores that emphasise balance sheet resilience and steadier financial profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com