


What Investors Overlooked Before Axon Enterprise Slid
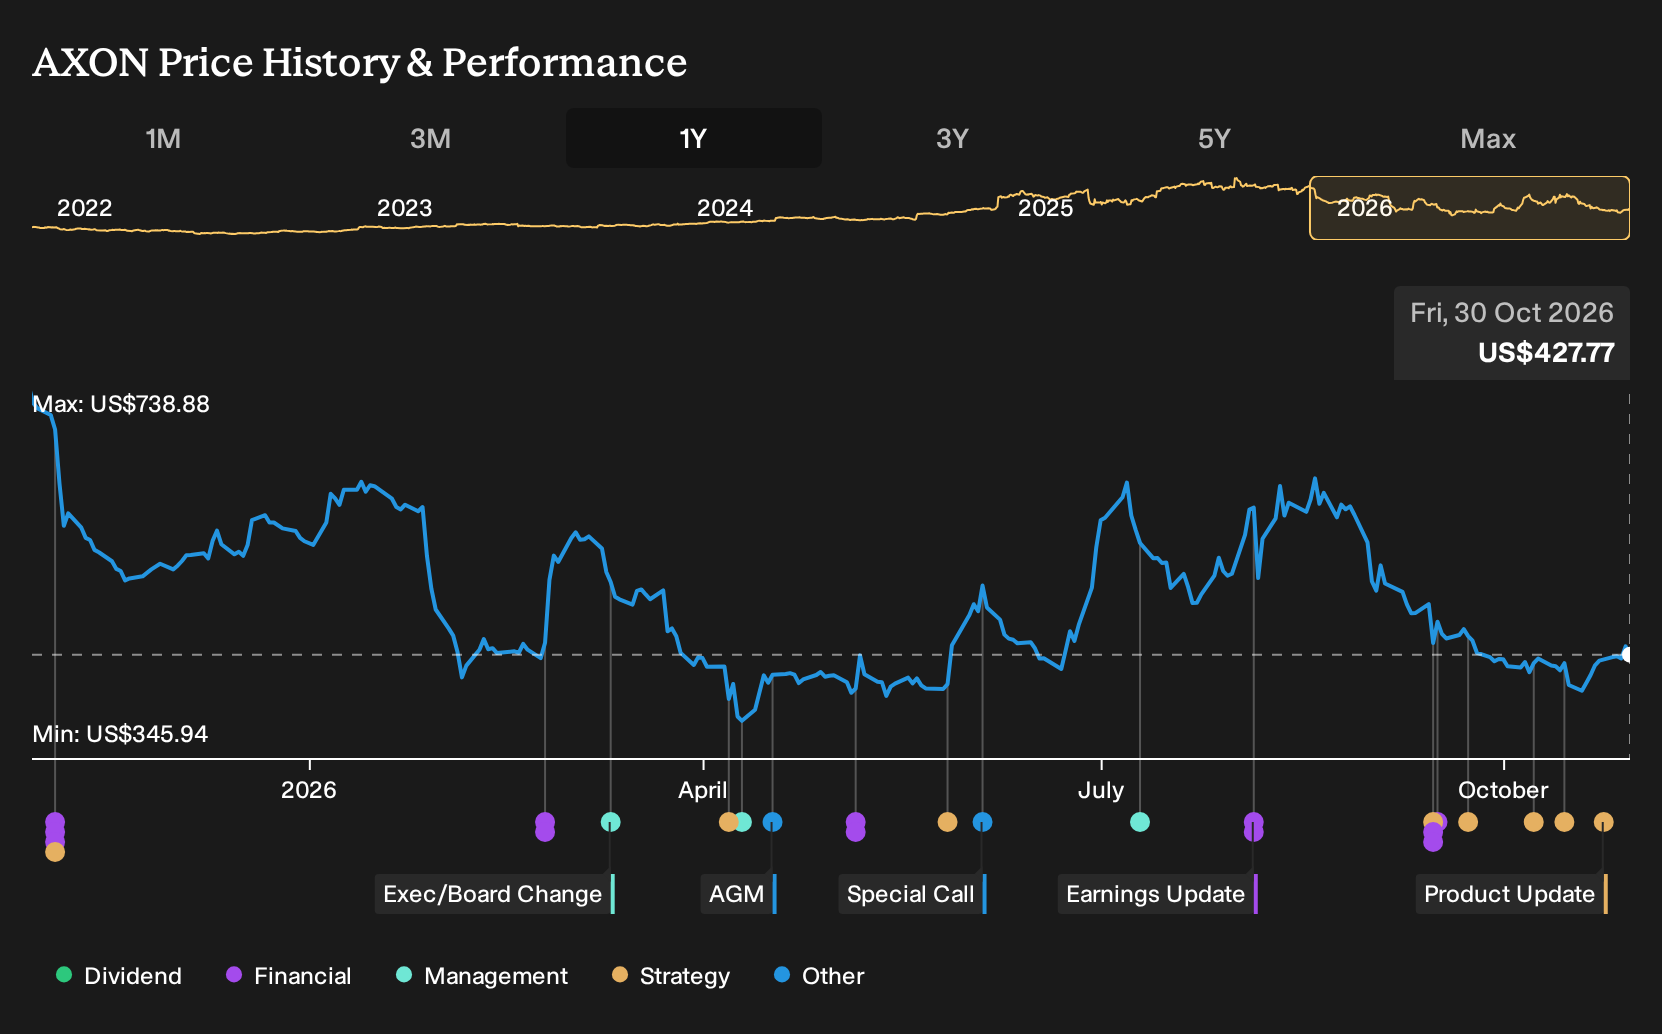
Axon Enterprise has been all over the headlines this year, from record contracts and AI tools to a sharp selloff after fresh guidance and a big convertible notes deal. Holding Axon Enterprise over the past year would have meant a 41.6% loss, including dividends. If you had put money into the stock back on 30 October 2025, what exactly did that rollercoaster reflect, and which expectations now deserve a closer look?
Narratives are how investors here put a case on the record, with explicit assumptions about revenue, margins and the multiple. Those assumptions imply an estimated Fair Value.
The move put Axon Enterprise in the middle of this trade. Scan 37 AI small caps for other companies exposed to it.
The Two Axon Enterprise Stories Investors Had To Weigh
The shares cost US$739 at the start of the period, and Axon Enterprise investors were choosing between two sharply different stories.
The bullish narrative put Fair Value at US$885. This view was built on the idea that AI tools, drones, and premium SaaS bundles could support 24.3% revenue growth and a future P/E assumption of 197.2x over three years.
The bearish case set Fair Value at US$652. This perspective focused on rising regulation, pricing pressure, and a future P/E assumption of 109.2x if revenue rose 21.4% with profit margins at 13.9%.
What The Evidence Did To The Axon Enterprise Argument
The clearest test of both Axon Enterprise narratives came from Q2 2026 results. Revenue reached US$904.4 million compared with US$668.5 million in Q2 2025, which backed the growth story. Net income slipped to US$29.4 million from US$36.1 million and net margin moved from 5.4% to 3.3%, so profitability traction lagged the bullish case. Overall, the evidence cut both ways.
The lesson is simple. When a thesis leans on rising margins as much as rising sales, you track the net margin line each quarter and see whether it actually moves toward the forecast.
What Axon Enterprise’s Lower Price Now Asks You To Believe
Axon Enterprise trades at US$428 today after a 41.6% loss over the past year, while this bullish Narrative’s Fair Value still sits above the current price.
The argument leans on premium SaaS, AI tools, and counter-drone systems turning into richer recurring contracts. A buyer now would need to believe Axon Enterprise can translate that contract base into durable, high margin recurring revenue.
"The ongoing shift by public safety agencies from basic contracts to premium plans and AI enabled bundles is visible in Axon Enterprise’s 39% annual recurring revenue growth to US$1.6b, net revenue retention of 126%, and future contracted bookings of US$15.1b."
One Narrative has put a figure on that disagreement. → See the Narrative with its higher Fair Value, assumptions and all
Go Straight To The Source
The next headline does not have to be where your research begins. Go straight to the companies and see whether a contrarian opportunity could be taking shape.
- Company 1 - 34% below our estimate - turn long term optical and solar contracts into higher margin manufacturing programs.
- Company 2 - 47% below our estimate - channel large-scale AI infrastructure demand into advertising tools and engagement-focused devices.
- Company 3 - 46% below our estimate - expand from trackers into storage and inverters to reshape utility scale project economics.
Those are three of them. See all 29 potentially undervalued companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com