


Del Monte (DMC) Following Q3 Profit And Dividend Return Faces A Valuation Debate
Del Monte (DMC) returned to investor watchlists after third quarter earnings showed a move from loss to profit, and the board approved a new quarterly dividend of $0.30 per share.
Despite Del Monte swinging back to profit and reinstating a quarterly dividend, the share price has drifted lower, with a 7.3% decline over the past week and a year to date share price return down 22.6% at US$27.35. That sits against a 3 year total shareholder return of 32.3%, which suggests that investors are reassessing both earnings quality and risk as the benefits of higher margin products and the new payout policy are weighed against concerns around banana pricing, supply chain health, and cost pressures.
Scan how Del Monte compares with other food and agriculture stocks facing similar pricing and cost pressures by reviewing our hand picked 29 high quality undervalued stocks.
So is Del Monte’s recent slide a signal that the latest profit and dividend do not fully convince investors about the business, or has sentiment simply swung too far and pushed valuation out of line?
Most Popular Narrative: 47% Undervalued
Del Monte's most followed valuation story pins fair value at $52 per share, well above the last close at $27.35. This frames the recent price weakness very differently from the earnings wobble the market has been reacting to.
The current valuation implies the share price does not fully reflect the higher-margin earnings profile that could come from the Del Monte Foods acquisition, premium pineapple replanting, and new value-added product launches.
See why 15 investors see Del Monte as 47% undervalued.
Result: Fair Value of $52 (UNDERVALUED)
Still, the Del Monte story hinges on keeping banana price competition and elevated freight and farming costs in check, or the higher margin plans could quickly lose momentum.
Find out about the key risks to this Del Monte narrative.
Another View: What Del Monte’s Cash Flows Say
The analyst story around Del Monte leans heavily on earnings and a US$52 fair value, yet the Simply Wall St DCF model points to a future cash flow value of US$24.42 per share, below the current US$27.35 price. That suggests less upside on a cash flow basis. Which lens do you trust more for your own work?
To see how this cash flow view is built line by line, Look into how the SWS DCF model arrives at its fair value.
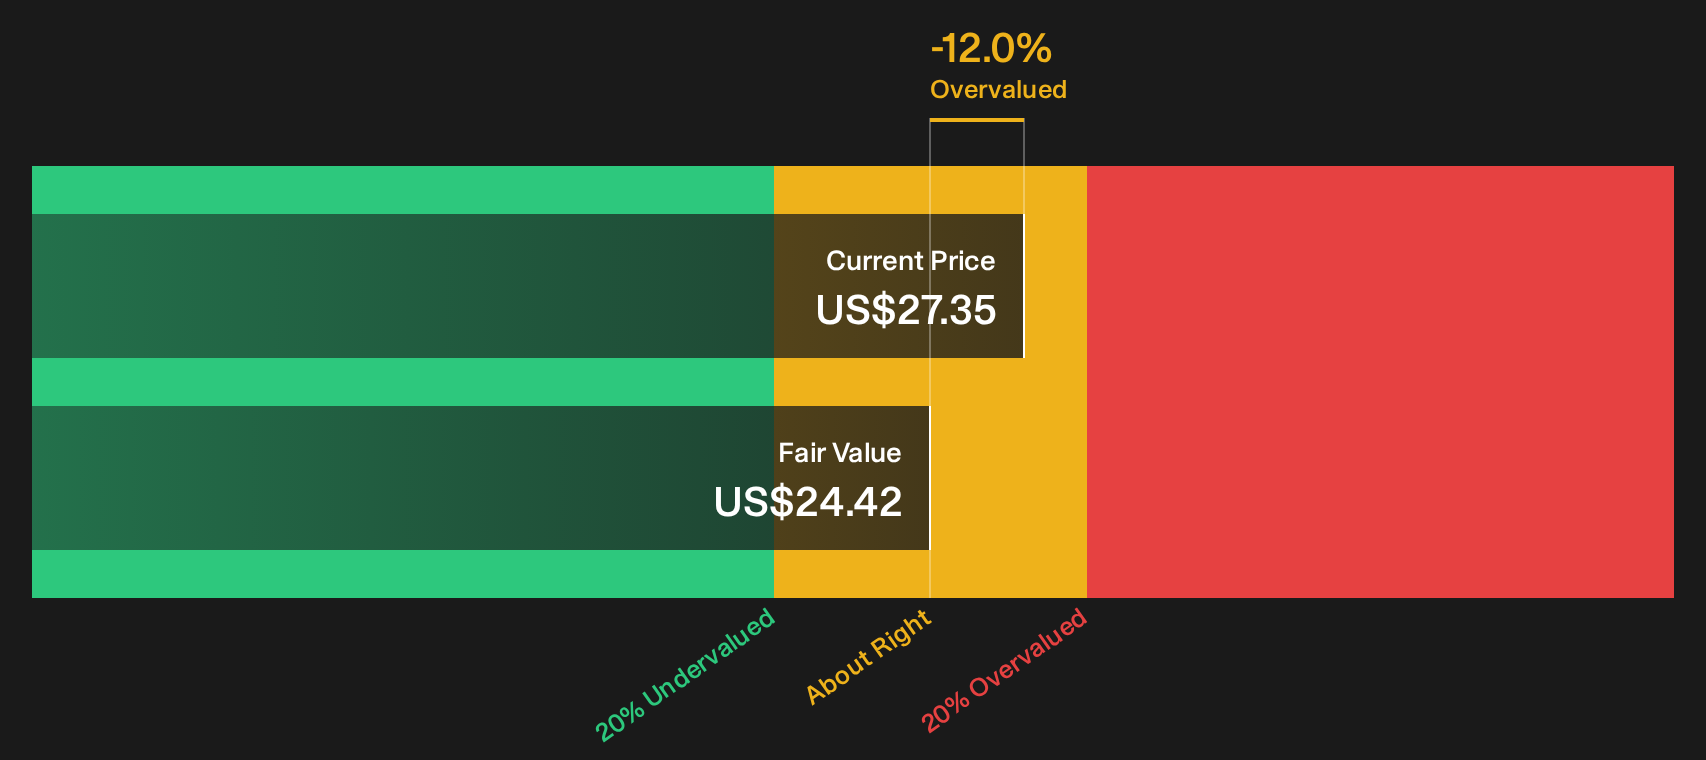
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Del Monte for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment on Del Monte is clearly mixed today, with fresh profits and a dividend on one side and cost and pricing worries on the other. Act quickly, review the full set of trade offs, and judge the balance of risks and upsides for yourself with 4 key rewards and 2 important warning signs.
Looking for more ideas beyond Del Monte?
Do not stop your research with Del Monte. Use focused screeners to surface other opportunities that fit different goals, risk levels, and income needs.
- Target potential income anchors by reviewing companies in our 5 dividend fortresses that may help support a portfolio focused on regular cash payouts.
- Hunt for mispriced opportunities by scanning the 18 high quality undiscovered gems that pair stronger fundamentals with limited market attention.
- Dial down portfolio stress by using the 30 resilient stocks with low risk scores to filter for businesses with more resilient profiles and lower risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com