


NSK (TSE:6471) Nears Earnings Call With Undervalued Narrative Still In Play
The upcoming Q2 2027 earnings call for NSK (TSE:6471) on October 30, 2026, is drawing fresh attention to the bearings and automotive supplier as investors consider its recent share performance.
NSK’s share price has pulled back recently, with a 1-day share price return of 2.72% down and a 30-day share price return of 8.74% lower. However, the 1-year total shareholder return of 32.6% and 5-year total shareholder return of 62.92% indicate that momentum has built over time as investors reassess its risk and growth profile ahead of the Q2 2027 earnings call.
Scan beyond NSK ahead of the earnings call and evaluate other industrial and capital goods stocks that screen as 15 high quality undervalued stocks.
After a strong run over the past year but a softer stretch into the earnings call, NSK now sits at an interesting crossroad. Does the current valuation still skew the risk reward in favour of new buyers?
Most Popular Narrative: 24% Undervalued
NSK last closed at ¥1,002.5, while the most followed valuation narrative anchors fair value at ¥1,316. This frames the current debate around execution on margins and cash generation rather than short term share swings.
NSK is still focusing on expanding its industrial machinery sales mix toward higher margin aftermarket, consumer and precision machinery products. The plan to lift Industrial Machinery operating margin from 3.3% in FY2025 to 10% by FY2028 points to a potential uplift in segment earnings and overall net margins.
NSK’s initiatives in the automotive market around electrification are advancing, with plans to expand products such as heavy vehicle hub units, anticorrosion e axle bearings and ball screws for electric brakes, and to grow capacity in North America and India. This is expected to support operating profit from the Automotive segment even if sales stay broadly flat and thereby support group earnings.
See why 1 investors see NSK as 24% undervalued.
Result: Fair Value of ¥1,316 (UNDERVALUED)
Still, if industrial demand softens again or the margin targets in Industrial Machinery slip, the bullish NSK narrative could quickly lose credibility.
Find out about the key risks to this NSK narrative.
Another View: How NSK Looks On Earnings Ratios
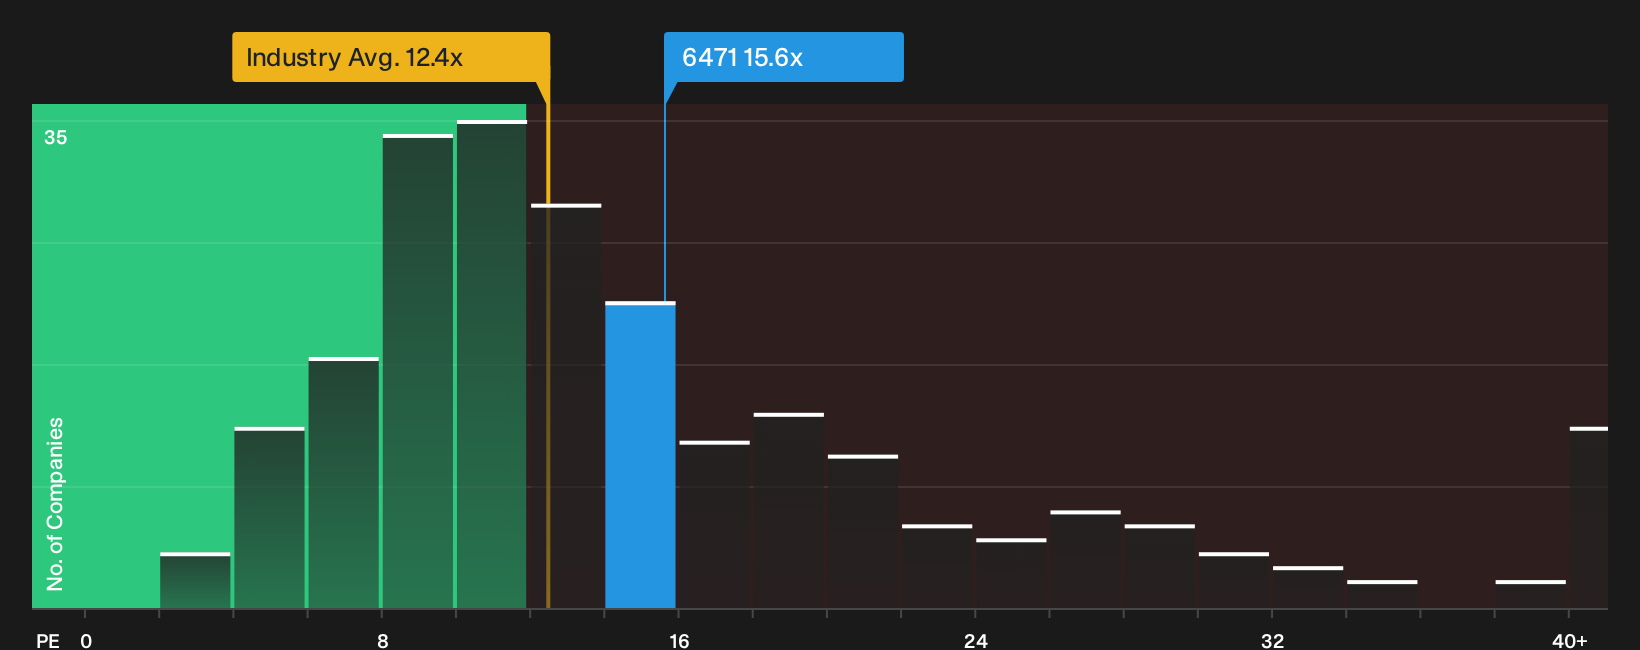
The first narrative frames NSK as undervalued against a ¥1,316 fair value. On earnings multiples, the picture is more mixed. The stock trades on a 15.6x P/E, which is richer than the JP Machinery average at 12.5x but below a 19.8x fair ratio estimate that the market could move toward. Is that a margin of safety or a signal that expectations are already busy?
To weigh that question against your own assumptions, focus on how comfortable you are with paying more than the sector average P/E for a business that still screens as good value versus its fair ratio and peer group. Consider whether that gap feels like valuation risk or opportunity in your playbook. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on NSK so far, right, with some investors focused on risks and others on potential upside. Move quickly, scan the underlying data, then pressure test your own thesis against the 4 key rewards and 1 important warning sign.
Looking for more NSK investment ideas beyond this earnings call
If you only stop at NSK, you could miss other opportunities that fit your style. Put the same scrutiny to work across a wider watchlist.
- Spot potential mispricings early by scanning a curated pool of companies that screen as 15 high quality undervalued stocks.
- Strengthen portfolio resilience by focusing on businesses highlighted in the list of solid balance sheet and fundamentals (22 results).
- Turn steady cash flows into a clear income plan by reviewing companies with the 27 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com