


3 Regional Bank Stocks That Could Benefit If US Interest Rates Rise Again
Rates are back in the spotlight after St. Louis Fed President Musalem hinted that borrowing costs may need to climb again to pin down stubborn inflation, and that kind of signal can quickly reshuffle winners and losers across the market. Investors who ignore it risk missing companies that might quietly gain from higher yields. This article walks through three U.S. financial stocks from our screener that appear closely tied to this rate story and explains why their exposure to the latest Fed messaging may be important for portfolio decisions.
The three stocks highlighted below are a first pass through this rate-sensitive corner of the market, and the full screen surfaced 11 more U.S. banks and insurers with equally compelling rate stories that are not covered here. To identify and analyze potential high-conviction ideas that fit this rising-yield theme, go directly inside the US Financials (Banks and Insurance) Benefiting from Rising Interest Rates screener.
Burke & Herbert Financial Services (BHRB)
Burke & Herbert Financial Services is a long-established community bank headquartered in Alexandria, Virginia. It offers deposit accounts, loans, cash management, and wealth and trust services that are closely tied to Fed rate moves. It generates about $394 million from community banking and has a market value of roughly $1.44b.
Rising policy rates feed directly into Burke & Herbert Financial Services’ lending and deposit spreads. Recent net interest income of $105.02 million for Q3 2026 shows how that theme plays out in practice. Income investors may also notice the 3.12% dividend yield and consider what happens if a single key assumption breaks.
If that assumption feels fragile, go straight to the 3 key rewards and 3 important warning signs (1 is major!) to see what might be quietly reshaping the Burke & Herbert Financial Services story.

HomeTrust Bancshares (HTB)
HomeTrust Bancshares is a regional bank holding company that earns all of its $213 million revenue from U.S. banking, including deposits, loans, and securities that are closely tied to interest rate levels. The stock has a market value of about $741 million.
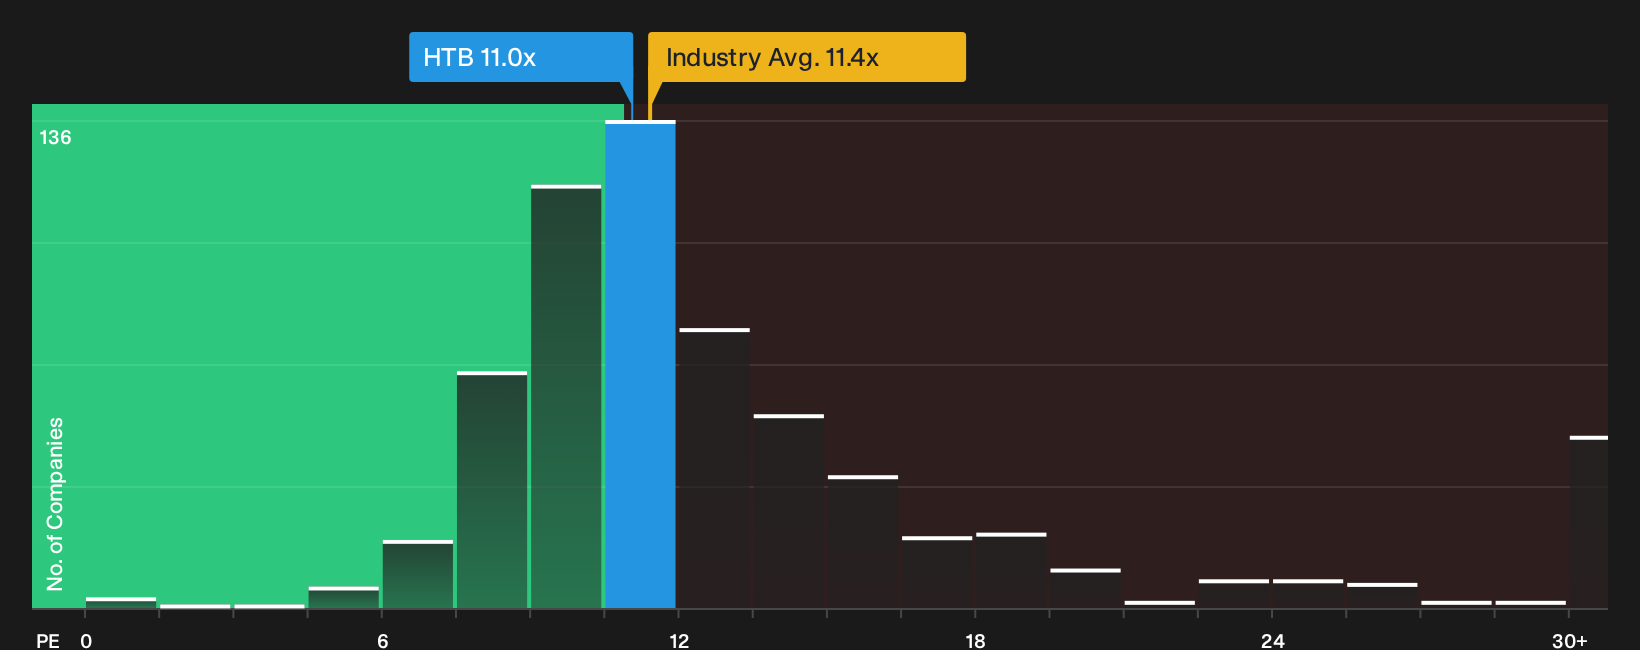
HomeTrust Bancshares sits firmly in the rising-rate story, with earnings anchored in net interest income and a P/E of 11x that is in line with the regional peer group. Strong profit margins and faster forecast earnings growth put more attention on what happens if one unseen pressure on credit costs shifts at the wrong moment.
That hidden pressure point is exactly why the 3 key rewards and 1 important warning sign could be worth your next click, before earnings expectations and credit costs start decoupling.
Farmers National Banc (FMNB)
Farmers National Banc is a Canfield based regional bank holding company tied to the rising rate theme through lending spreads and fee income. It earns about $162 million from its bank segment, $41 million from other revenues, and $16 million from trust services, with a market value near $934 million.
Farmers National Banc links directly into the rising rate story, with net interest income and fee streams that line up with the screener’s criteria and a 4.6% dividend that may appeal to income focused investors. The appeal of that income stream depends on how one unresolved credit and capital question plays out.
That unresolved piece is exactly where the 4 key rewards and 1 important major warning sign could sharpen your view of Farmers National Banc before credit trends and capital needs begin to diverge.

Seeking Fresh Alternatives Before The Crowd
Fresh breakouts and quiet pullbacks rarely stay under the radar for long. Consider using momentum while it is present, before prices move further away, and look for opportunities early.
- Look for early momentum in smaller companies that already generate cash by scanning 39 profitable AI stocks that aren't just burning cash before their stories are fully reflected in market prices.
- Review 30 resilient stocks with low risk scores to find companies with steadier balance sheets that may attract broader attention later.
- Use 5 dividend fortresses to identify payouts that could help stabilize overall returns even when prices fluctuate.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com