


e.l.f. Beauty (ELF) Is Drawing Fresh Attention, What Is Behind It?
e.l.f. Beauty (ELF) is back in focus after two intertwined storylines: stronger earnings estimates and a fresh Zacks Rank #1, alongside Rhode's outperformance and a new $5 million women's health partnership.
At a share price of US$111.69, e.l.f. Beauty has cooled slightly in the very short term, with a 1-day share price return that fell 1.12% and a 7-day share price return down 2.23%. However, momentum over the past few months has been strong, including a 30-day share price return of 10.62%, a 90-day share price return of 34.74% and a year-to-date share price return of 43.54%, while the 1-year total shareholder return declined 8.56% even as the 5-year total shareholder return reached about 2.6x. This suggests that recent Rhode headlines and earnings optimism are influencing near-term sentiment more than long-run holders’ experience.
Compare e.l.f. Beauty's momentum and philanthropy driven story with a curated set of consumer-focused stocks in the 18 high quality undiscovered gems that are also pairing brand strength with solid fundamentals.
That mix of short term cooling and longer term strength raises a simple question: Are recent moves in e.l.f. Beauty mostly sentiment around Rhode and earnings buzz, or a clean read on underlying value?
Most Popular Narrative: 18% Undervalued
Against the last close at $111.69, the most followed narrative anchors e.l.f. Beauty’s fair value at $137.00 and ties that gap to long run category expansion, heavier marketing and Rhode integration, all filtered through a 7.82% discount rate.
Expansion of e.l.f. Beauty’s multi brand, multi category portfolio, with non core cosmetics brands now contributing over 30% of sales and skin care near 25%, creates room for mix shifts toward higher value categories that can influence gross margin and earnings over time.
Growing international reach, with overseas sales at 21% of net sales and supported by wider placement at partners such as Sephora and Boots alongside rhode and Naturium rollouts across 19 European countries, opens the door for a larger share of revenue and more diversified earnings streams.
See why 20 investors see e.l.f. Beauty as 18% undervalued.
Result: Fair Value of $137.00 (UNDERVALUED)
Still, the bullish story around e.l.f. Beauty can unravel if higher marketing and SG&A costs outpace sales, or if recent price cuts fail to support volume.
Find out about the key risks to this e.l.f. Beauty narrative.
Another View: e.l.f. Beauty Through The P/E Lens
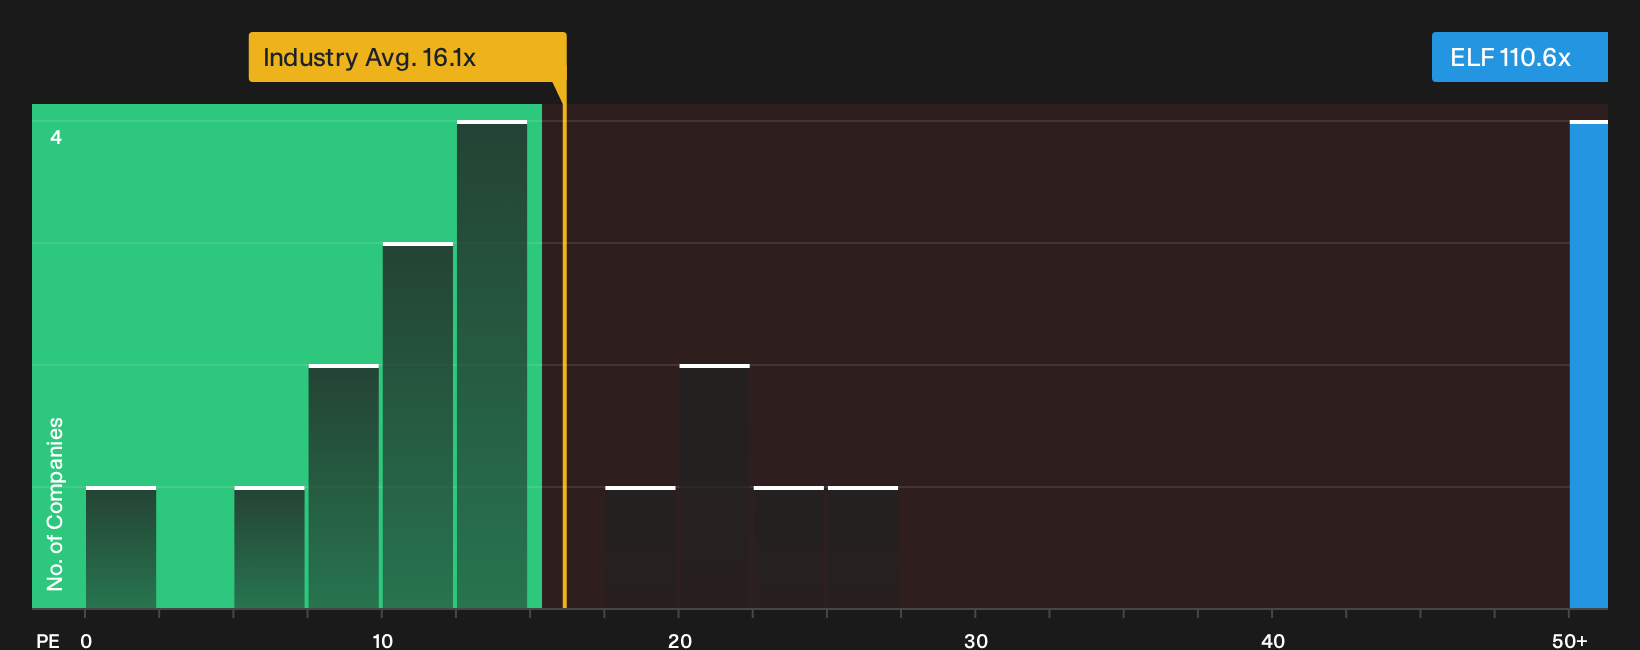
The bullish fair value of $137.00 leans on long term earnings assumptions. A simpler check looks at e.l.f. Beauty’s current P/E of 110.6x against the US Personal Products peer average of 25.7x and a fair ratio of 32.2x, which points to a rich valuation and less margin for error.
For readers weighing how much optimism is already in the price, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around e.l.f. Beauty can feel confusing, so act quickly to review the full picture of its potential upsides and pressure points. Before forming a firm view, weigh the 1 key reward and 3 important warning signs
Want more ideas beyond e.l.f. Beauty?
Do not stop at one story. Put e.l.f. Beauty in context by lining it up against other businesses that match your risk, income, and valuation priorities.
- Target reliable upside potential by scanning a curated pool of companies that score well on quality and value through the 29 high quality undervalued stocks.
- Build a sturdier core for your portfolio by focusing on financially robust businesses via the list of solid balance sheet and fundamentals (25 results).
- Strengthen your income stream and avoid scattered guesses by zeroing in on higher yielding opportunities using the 5 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com