


Where Does Agnico Eagle Mines (AEM) Valuation Stand Following Q3 2026 Results?
Agnico Eagle Mines (NYSE:AEM) has put fresh numbers on the table, with Q3 2026 results showing net income of US$1.35b and earnings per share of US$2.67 from continuing operations.
The fresh Q3 update dropped into a choppy tape for Agnico Eagle Mines, with the share price down 9.76% over the past month and 4.92% over the last week, yet still showing a 13.84% 90 day share price return and a very large 3 year total shareholder return. Together, these factors point to long term momentum even as short term sentiment cools around earnings, production guidance, dividends and the ongoing buyback.
Scan how Agnico Eagle Mines stacks up against other producers by running through the hand picked 34 elite gold producer stocks now that fresh earnings, guidance and buyback activity are in focus.
Agnico Eagle Mines appears to be a solid gold producer with active projects, steady dividends and ongoing buybacks. After the recent share price pullback, is that quality business now available at a fair price?
Most Popular Narrative: 99.9% Undervalued
Agnico Eagle Mines closed at $165.38 while the most followed narrative assigns a fair value of $123,914.00, which frames the story as one of extreme undervaluation and puts regional operating risks and optionality at the center of the debate.
With gold hovering near record highs, a massive structural shift is quietly playing out in the Abitibi greenstone belt that the broader market has completely failed to price in.
If you are holding Agnico Eagle ($AEM) or hunting for the ultimate asymmetric micro-cap play, you need to look at the cold engineering reality currently facing the Canadian Malartic complex, and the tiny junior right next door that holds the key to fixing it: Renforth Resources (CSE: RFR | OTCQB: RFHRF).
See why 34 investors see Agnico Eagle Mines as 100% undervalued.
Result: Fair Value of $123,914.00 (UNDERVALUED)
Still, this narrative relies heavily on a single user valuation model and assumes that Agnico Eagle Mines pursues Renforth’s Parbec deposit on terms that actually materialise.
Find out about the key risks to this Agnico Eagle Mines narrative.
Another View: What The SWS DCF Model Says About Agnico Eagle Mines
The community narrative pegs Agnico Eagle Mines at a fair value of $123,914.00 per share, which implies extreme mispricing. Our DCF model presents a different picture. It points to a future cash flow value of $90.96, which is below the current $165.38 share price and frames the stock as overvalued on this measure. For investors weighing these opposite signals, the central question is which set of assumptions they consider more reliable.
Look into how the SWS DCF model arrives at its fair value.
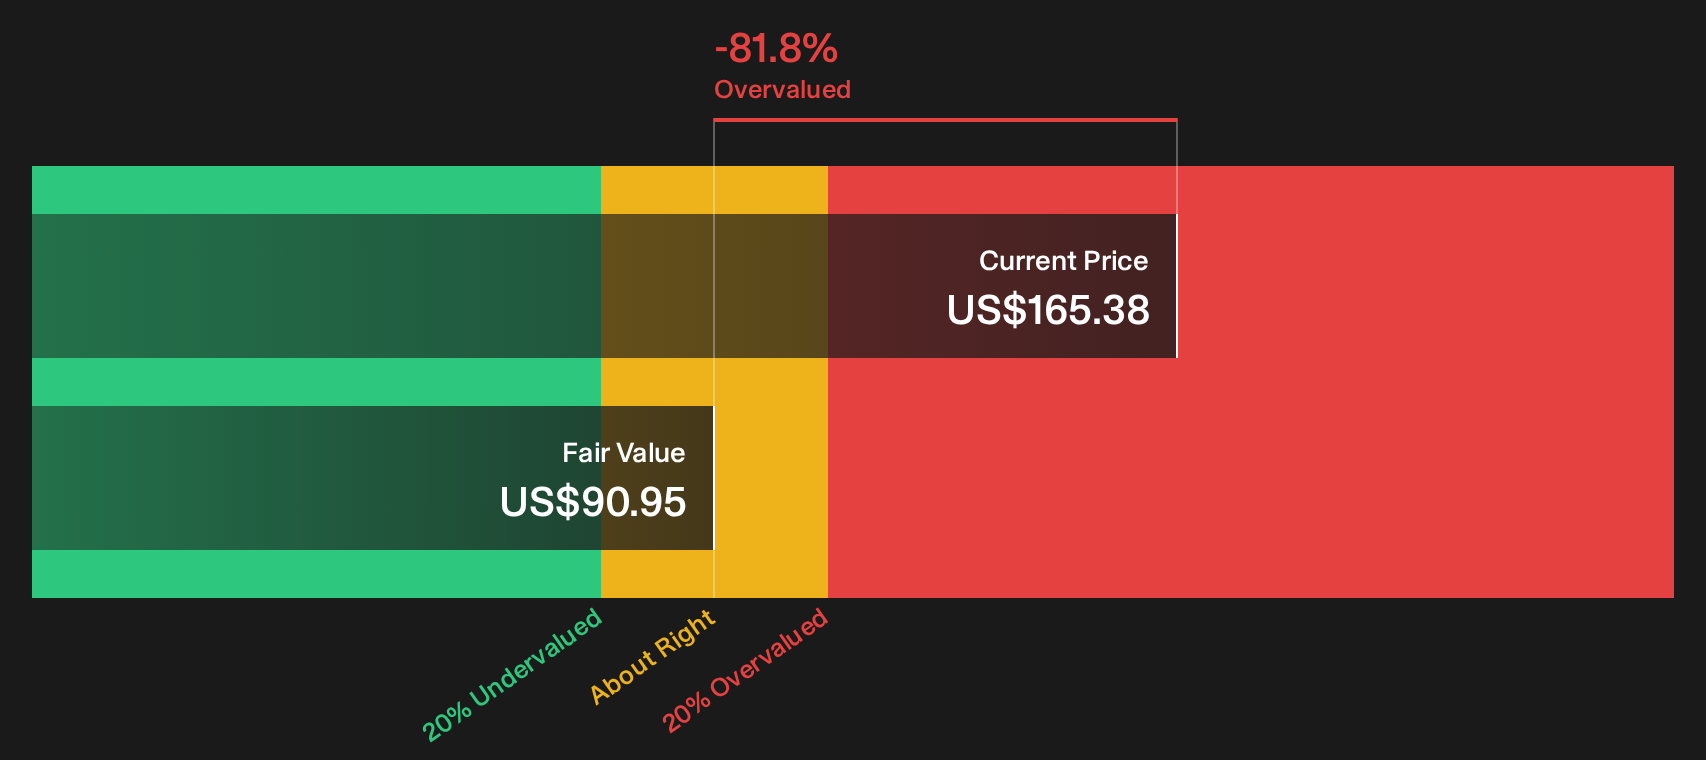
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Agnico Eagle Mines for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Agnico Eagle Mines, with bold community narratives and a more conservative DCF view, make this a moment to move quickly and check the numbers for yourself. To weigh both the concerns and the potential rewards directly, start with the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Agnico Eagle Mines?
If Agnico Eagle Mines has sharpened your focus on quality and price, broaden your watchlist now by lining up a few more targeted ideas from the screener tools.
- Target potential mispricing by lining up companies that pass strict quality and valuation filters through the 29 high quality undervalued stocks.
- Build a steadier income stream by reviewing higher yield payers that also clear fundamental checks using the 5 dividend fortresses.
- Reduce unwanted shocks by filtering for businesses with stronger finances and cleaner balance sheets via the list of solid balance sheet and fundamentals (25 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com