


Has Hut 8 (HUT) Fallen Far Enough To Match Its Sales?
Hut 8 has had a rough month on the market, and the slide is pushing investors to ask whether the current share price lines up with what the business is actually generating in sales. The question is not just where the Hut 8 stock price has moved recently, but whether its revenue base can support that valuation.
- The share price has fallen 31.0% over the past month, which puts fresh focus on whether Hut 8's current market value is still in step with its sales footprint.
- The company's push to convert contracted AI and high performance computing capacity into revenue, with large megawatt deals that are not yet billing, may support higher future sales but also concentrates attention on timing, execution and financing needs.
- There is a second opinion on Hut 8 worth weighing. See what analysts think Hut 8's shares could be worth.
For investors, the debate is whether Hut 8's recent share price level is appropriately anchored to its current sales when judged against the Fair Ratio benchmark.
For additional context on this AI and infrastructure theme beyond Hut 8, it can help to compare other stocks screened for 54 AI infrastructure stocks.
Is Hut 8 Getting Expensive on Sales?
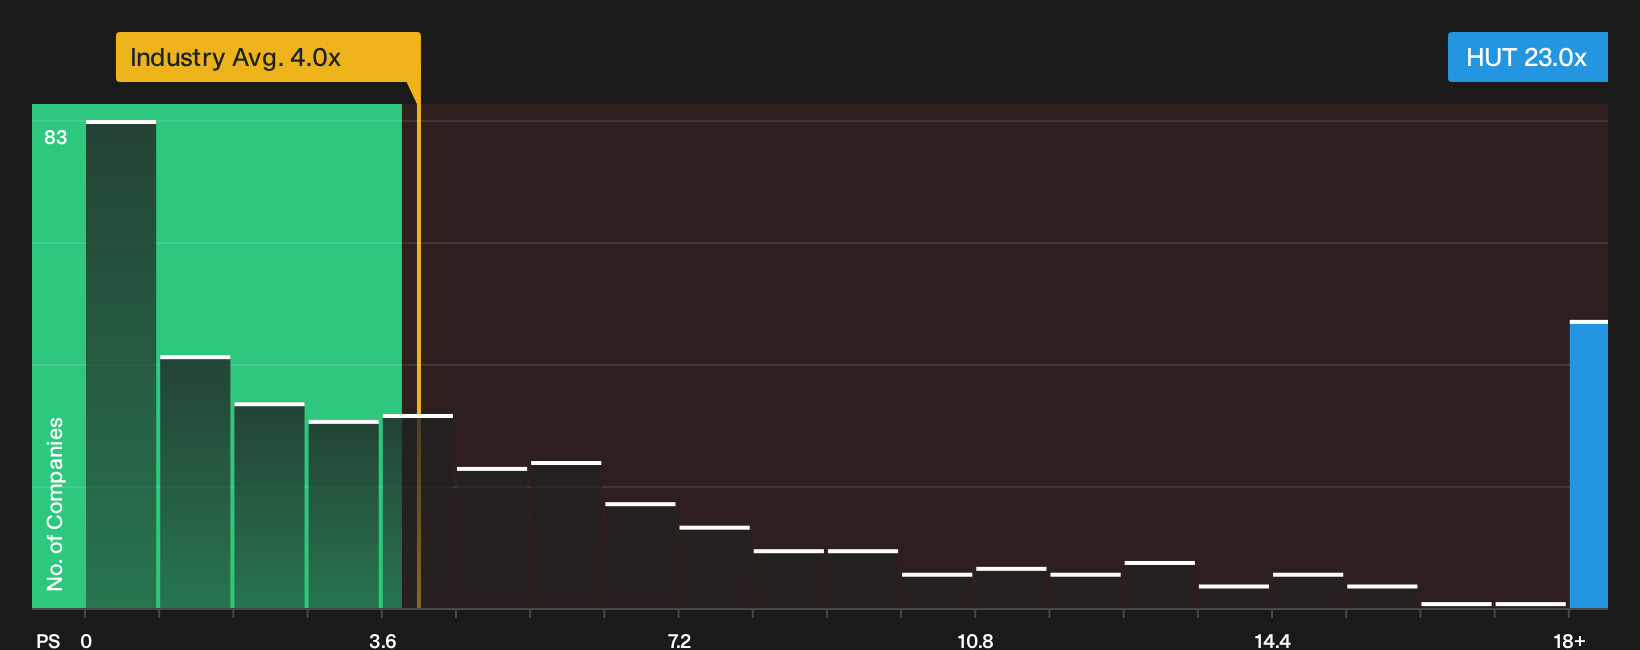
P/S is the cleanest lens for Hut 8 right now because investors are effectively paying for a revenue footprint that is still ramping, not steady earnings. On this metric, the stock trades on a P/S of 23.0x, which is far above the broader software sector on 4.0x and well ahead of direct peers around 1.6x.
The Fair Ratio framework, which adjusts the P/S benchmark for the company’s growth profile, margins, scale and risk, also flags Hut 8 as overvalued on sales. Because the market is already assigning a rich revenue multiple, any delays or changes in converting those large AI and high performance computing contracts into billing capacity could matter more for the share price than for lower rated rivals. The recent scrutiny of Bitcoin miners’ AI bets, including Hut 8’s contracted 949 MW that is not yet producing sales, underlines how much optimism is already embedded in this valuation multiple. Explore the numbers behind Hut 8's P/S valuation.
The Hut 8 Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where Hut 8's rich P/S discussion leaves off by explaining what kind of future path for growth, profitability and earnings would need to occur for the current valuation to look stretched or conservative. Rather than leaving you with a single ratio, Narratives describe the specific future that number relies on so you can watch how Hut 8's actual progress compares with it on the Community page.
One of the top community narratives on Hut 8: 34% undervalued
"The main requirement is that Hut 8 successfully converts its 8.7 GW development pipeline and large contracted AI campuses into long-duration, investment grade cash flows…"
Discover why this Narrative puts Hut 8 at 34% undervalued.
One more Hut 8 piece that could change your view
Valuation only shows part of the Hut 8 story, and the research also flags specific risk checks that deserve a look before you decide how to treat this stock. Take a closer look at 3 warning signs before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com