


Rogers Communications (TSX:RCI.B) On Penalty And Weak Earnings Still Carries An Undervalued Narrative
Rogers Communications (TSX:RCI.B) is back in focus after a $15 million regulatory penalty over its Infinite wireless plan marketing, paired with third quarter results that show modest sales gains but a steep net income drop.
For context, Rogers Communications shares closed at CA$45.48 on 29 October, with a 1-day share price return of 3.39% and a 30-day share price return of 3.79%. However, the 90-day share price return declined 4.17% and the 1-year total shareholder return fell 13.93%, suggesting recent momentum has picked up slightly while longer term performance remains weak as investors weigh the earnings slump, dividend affirmation and the Infinite plan penalty.
Compare this setback at Rogers Communications with other telecoms and utilities that screen well on balance sheet strength and cash generation using our curated list of solid balance sheet and fundamentals (6 results)
Rogers Communications still appears to be a sizeable, diversified telecom and media operator, yet the stock has lagged and recently absorbed a regulatory setback. Given that mix, is the current share price really offering fair value?
Most Popular Narrative: 23% Undervalued
With Rogers Communications closing at CA$45.48 against a widely followed fair value estimate of about CA$58.97, the narrative implies a sizeable valuation gap built on lower capital intensity, sports assets and steady telecom cash generation.
The media portfolio, which on a 2025 pro forma basis generated about $4.1b of revenue and over $400m of adjusted EBITDA and in Q2 2026 recorded 53% year on year revenue growth to $1.2b, provides an additional earnings stream that can diversify consolidated revenue and EBITDA away from slower growing telecom services.
See why 64 investors see Rogers Communications as 23% undervalued.
Result: Fair Value of CA$58.97 (UNDERVALUED)
Still, the narrative can break if regulatory pressure keeps internet and wireless pricing under strain, or if planned sports and media asset sales face delays or weaker valuations.
Find out about the key risks to this Rogers Communications narrative.
Another View: Rogers Communications Looks Expensive On Earnings
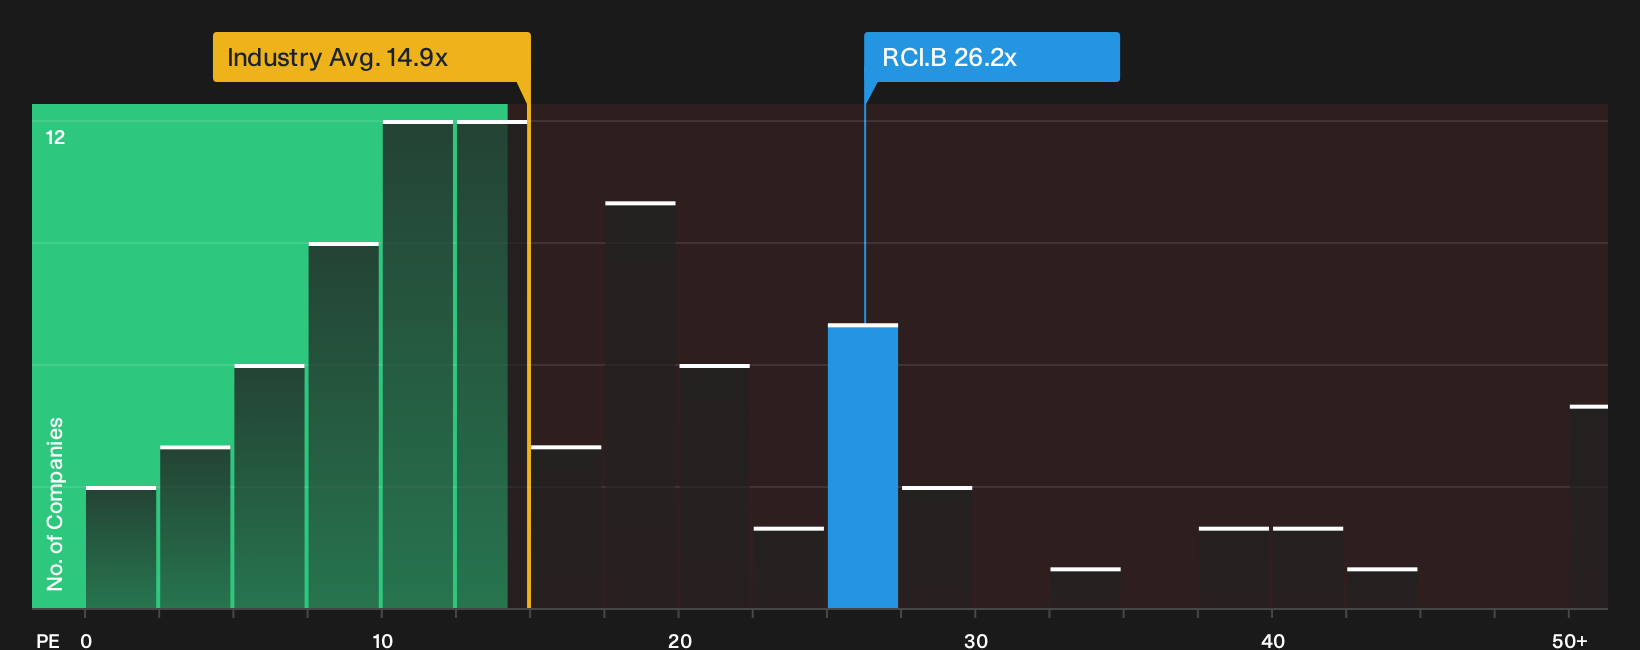
The first narrative leans on a fair value of CA$58.97 and a steep discount, yet the earnings multiple sends a very different message. Rogers Communications trades on a P/E of 26.2x, compared with 14.9x for the global wireless telecom group and 14.5x for peers, while its fair ratio is 11.6x. That gap points to meaningful valuation risk if sentiment shifts back toward more typical earnings multiples. The question is which signal investors should place greater weight on.
See what the numbers say about this price in our valuation breakdown, then consider how closely that earnings based view lines up with your own expectations for Rogers Communications. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Rogers Communications valuation and risk profile can pull you in both directions, so move quickly, look through the numbers yourself and weigh both sides. To see the full context behind the concerns and bright spots, review the 3 key rewards and 4 important warning signs
Looking for more investment ideas beyond Rogers Communications?
Rogers Communications gives useful context, but your portfolio deserves a broader bench of opportunities filtered by quality, value and resilience across the market.
- Target resilient balance sheets and steadier fundamentals by reviewing the list of solid balance sheet and fundamentals (6 results).
- Hunt for potential value opportunities with healthy business profiles using the 7 high quality undiscovered gems.
- Prioritise stability and capital preservation by focusing on companies in the 7 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com