


Bandwidth (BAND) Stock Price Slides After Q3 Earnings Turn Profitable
Bandwidth just delivered Q3 2026 earnings with the kind of profit story many software and communications investors say they want, then the market punished the stock anyway. After the release, the share price fell 10.9% to US$47.34, even as revenue reached US$234.0m and non GAAP earnings per share came in at US$0.50. Sentiment looks locked on the short term price drop while the income statement shows a business that has moved from losses to positive net income.
Interested in how Bandwidth turned losses into profit but uneasy about the sharp share price drop right after earnings? Check out the 30 resilient stocks with low risk scores to compare this story with companies that pair resilient operations with lower risk profiles.
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs Q3 2025): US$234.0m vs. US$191.9m (up about 22%)
- Net Income (Q3 2026 vs Q3 2025): US$5.25m profit vs. US$1.24m loss (moved into positive earnings)
- Basic EPS (Q3 2026 vs Q3 2025): US$0.16 vs. a loss of US$0.04 per share (returned to positive per share results)
- Adjusted EBITDA Margin (Q3 2026 vs Q3 2025): 22% vs. prior year period margin not specified (record margin level on management’s figures)
Prefer clean charts instead of another wall of earnings tables and footnotes? See Bandwidth’s full financial picture with a visual breakdown of its valuation in the company report for Bandwidth.
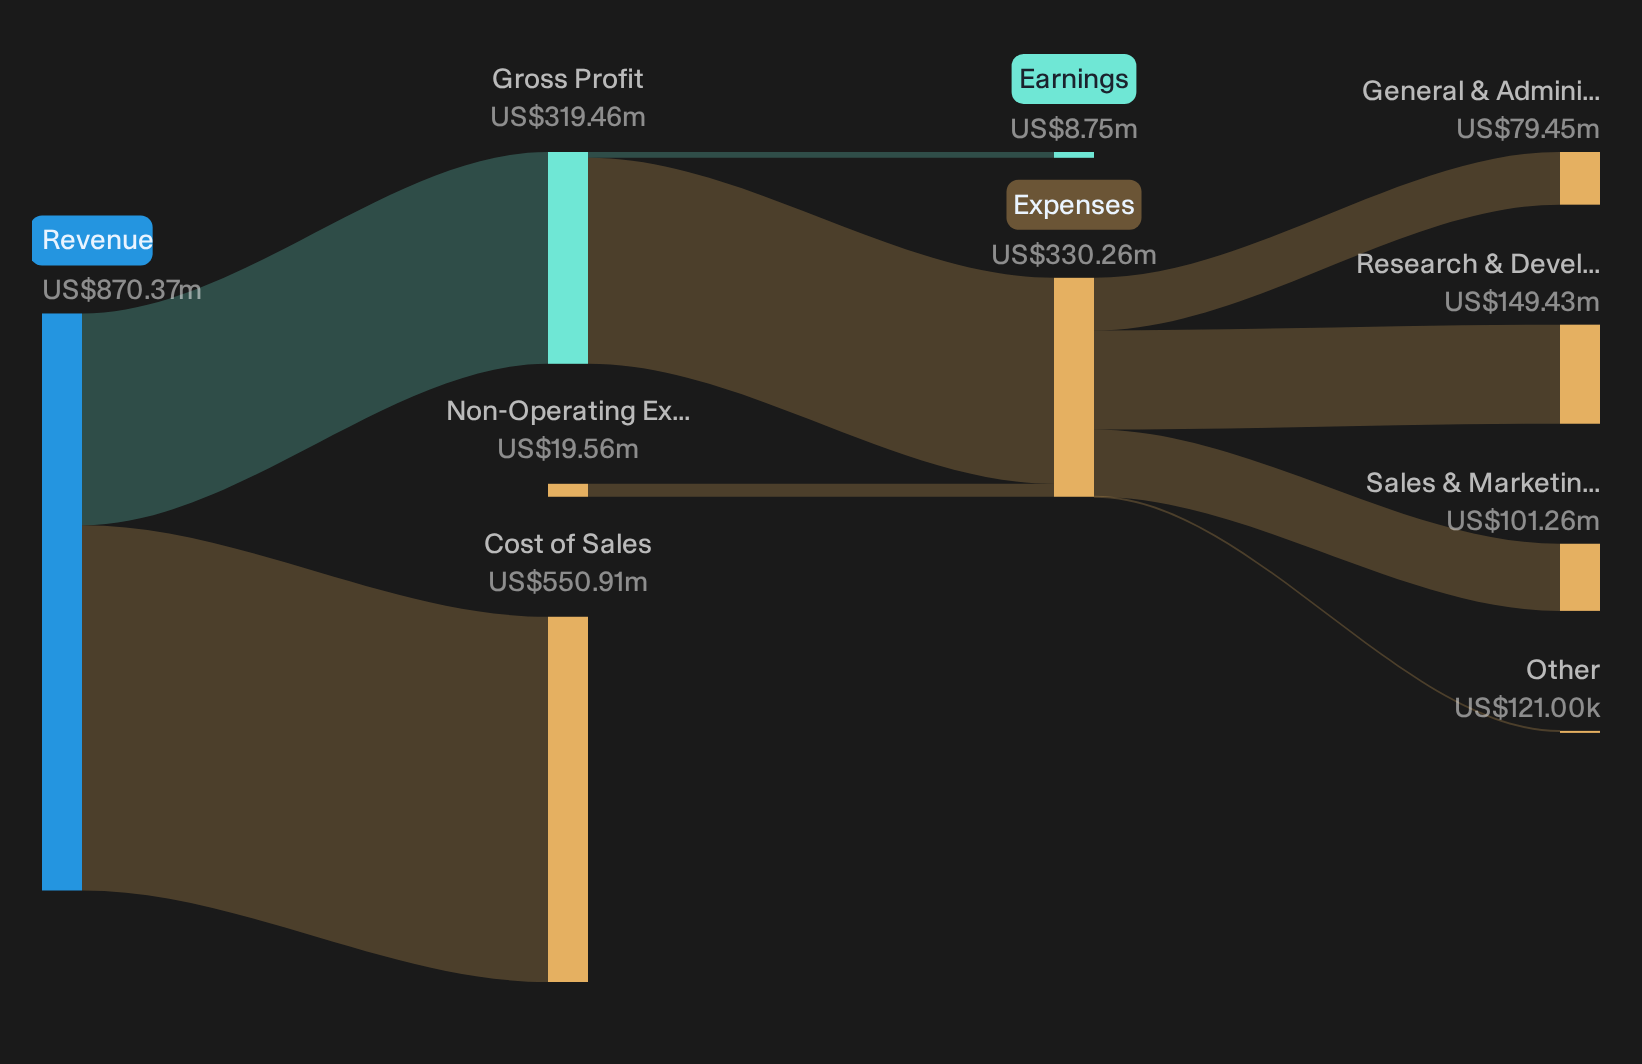
Evaluating Bandwidth’s AI and Software Milestones
The bullish story on Bandwidth hinges on AI driven contracts and richer software layers turning into durable, high margin usage over time.
"The main priority is that Bandwidth continues to convert its growing base of large enterprise and software-attached contracts into durable, high-margin cloud communications and AI services usage despite competitive and regulatory pressures."
Q3 hits several checkpoints. Software services reached US$7m with annual recurring revenue above US$30m, a small but fast growing slice of cloud communications income. Management reported 11 wins above US$1m in annual contract value since early 2026, with 17 since 2025 totaling about US$30m. A record 22% adjusted EBITDA margin and 113% net retention show early traction, even as the share price fell sharply on the print.
The price and this Narrative do not agree. → Uncover what this Narrative says Bandwidth is actually worth.
Bandwidth Bear Case: Contract Quality Versus Dilution Fears
Bearish investors worry that Bandwidth’s revenue base could stay choppy even as AI usage grows. The question is whether Q3 results show that fragility starting to bite.
"Bearish analysts expect Bandwidth to see its revenue base remain vulnerable to shifts by large customers and away from legacy communication APIs, which could keep recurring income unpredictable even as AI driven traffic grows."
The print cuts both ways. Record 113% net retention, over US$30m software ARR and multiple new contracts above US$1m suggest expanding, not shrinking, large customer spend. Yet guidance trims political messaging to US$10m and diluted shares to about 39m keep the dilution and cyclical usage worries alive, despite Q3’s 22% revenue growth and 22% adjusted EBITDA margin.
Hunt For Mispriced Earnings Power
Bandwidth just showed how a strong income statement can still be met with a sharp price reset. The real opportunity is finding stocks that could be undervalued before the market corrects them.
- Company 1 - 47% below our estimate - turns intensive spending on data infrastructure and AI tools into advertising formats that strengthen business customer engagement.
- Company 2 - 48% below our estimate - co-designs specialized hardware for medical, automotive and industrial clients through a sketch-to-scale approach that embeds engineering into long contracts.
- Company 3 - 31% below our estimate - supplies custom chips and connectivity components that support demanding data processing, networking and security workloads for large-scale digital infrastructure.
Three companies from the same screener. Open all 29 potentially undervalued companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com