


Trane Technologies (TT) Following Strong Q3 And Higher Guidance Is The Stock Fully Valued
Why Trane Technologies Stock Is Back in Focus
Trane Technologies (TT) stepped into the spotlight after third quarter results topped analyst forecasts, revenue reached US$6.76b, and management lifted full year guidance while highlighting stronger bookings and a larger backlog.
Despite the earnings beat and higher full year guidance, Trane Technologies’ share price has eased in the short term, with the 7 day share price return down 3.9% and the 30 day move lower by 5.4%. However, the 3 year total shareholder return of 108.5% and 5 year total shareholder return of 153.8% show that long term holders have still seen substantial gains, so recent weakness appears more like a pause in what has been strong multi year momentum.
Scan beyond Trane Technologies and see how other industrial players with strong order books and earnings momentum line up in our curated list of 43 power grid technology and infrastructure stocks.
Bulls point to Trane Technologies’ earnings beat, higher guidance, and large backlog. Bears focus on a rich valuation after years of strong returns. Which case does the current pricing actually support as you weigh the stock’s worth?
Most Popular Narrative: 18% Undervalued
Trane Technologies closed at $431.10 while the most followed narrative estimates fair value at $526.67, leaving a sizeable valuation gap that hinges on how convincingly the backlog, services mix, and AI cooling pipeline convert into future earnings.
Trane Technologies is poised for significant growth in the Commercial HVAC segment, with current record enterprise bookings growth of 37% year over year, a US$12.1b backlog that is up 70% year over year, and sustained strength in Americas commercial and applied bookings supporting potential future revenue and earnings.
See why 38 investors see Trane Technologies as 18% undervalued.
Result: Fair Value of $526.67 (UNDERVALUED)
Still, the Trane Technologies story depends heavily on the US$12.1b Commercial HVAC backlog, as well as on pricing keeping up with cost and regional mix pressure.
Find out about the key risks to this Trane Technologies narrative.
Another View: What Trane Technologies’ P/E Is Telling You
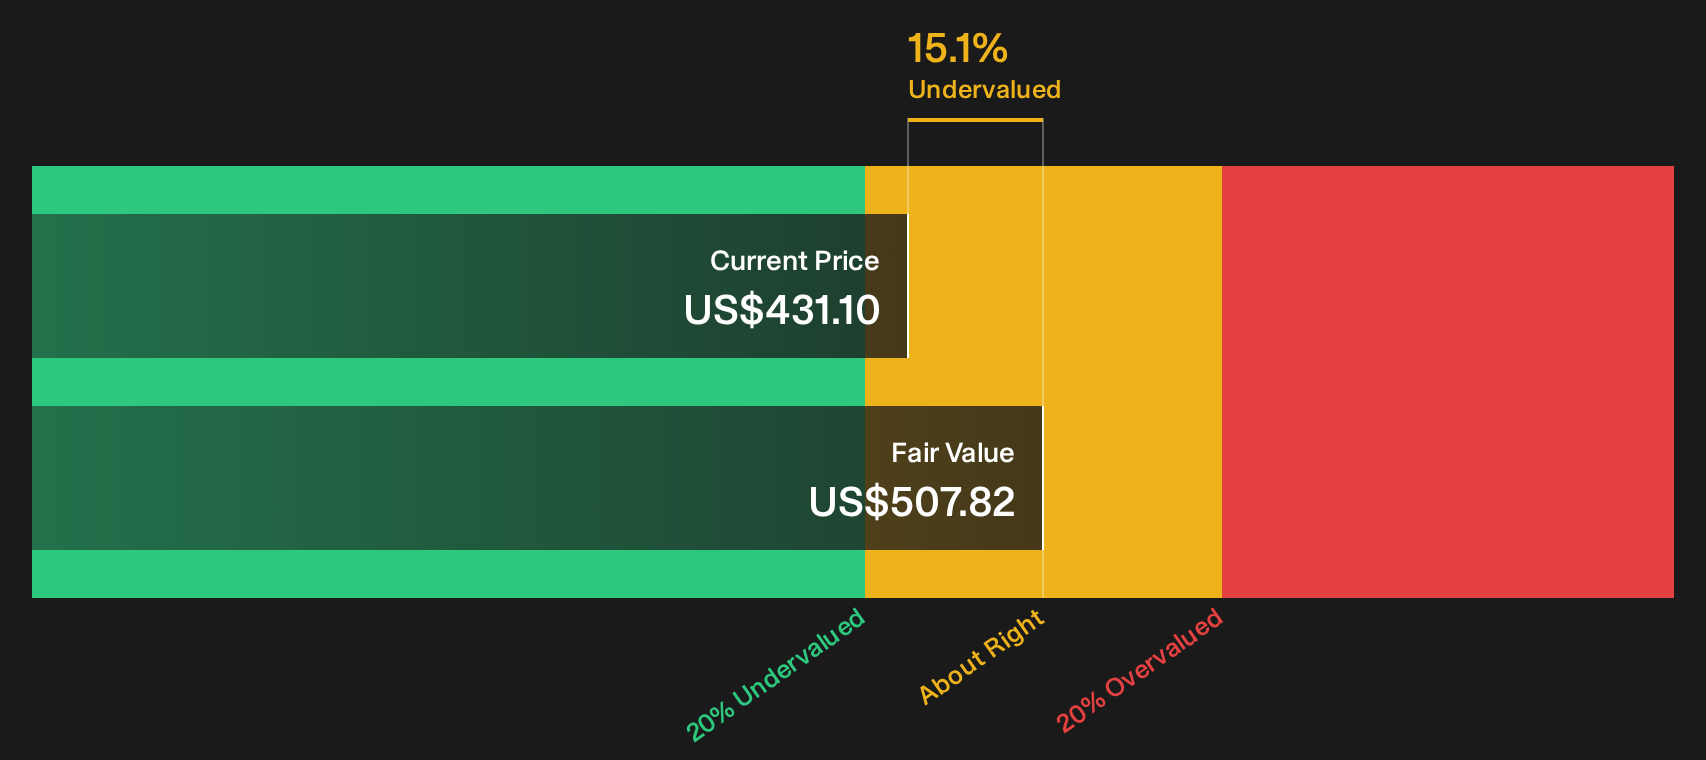
The SWS DCF model points to Trane Technologies trading about 15.1% below an estimated fair value of $507.82, which supports the undervalued narrative. Yet the current P/E of 31.6x sits above the US Building industry at 21.6x and above a fair ratio of 30.2x. Is the market offering a margin of safety, or simply asking you to pay more for quality?
For a closer look at how this cash flow based estimate is built and what is baked into that fair value, Look into how the SWS DCF model arrives at its fair value.
Next Steps
Curious whether the optimism in this Trane Technologies story matches your own read of the numbers and risks? Act quickly and review the potential upside signals in our breakdown of 4 key rewards.
Looking for more investment ideas beyond Trane Technologies?
If the Trane Technologies setup has your attention, do not stop here. Use the same disciplined lens to hunt for fresh opportunities by screening the market intelligently.
- Target potential mispricings by scanning a focused universe of 30 high quality undervalued stocks that pair stronger fundamentals with appealing entry points.
- Anchor your portfolio with sturdier businesses by reviewing a list of solid balance sheet and fundamentals (23 results) that can better withstand shocks when conditions get rough.
- Spot tomorrow's potential standouts early by filtering for 18 high quality undiscovered gems before attention and capital crowd into the obvious trades.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com