


ONEOK (OKE) Stock Looks Below Fair Value On Raised 2026 Guidance
ONEOK has delivered a powerful run over the past few years, and the latest earnings headlines keep attention firmly on the stock. With the share price now well above where it sat five years ago, the live question is whether that valuation is still grounded in what the business earns.
- Over the past 5 years, ONEOK has returned 95.1%, which puts real pressure on the current earnings profile to carry that higher market value.
- Recent earnings outperformance and higher future earnings expectations can support a richer view of what each dollar of profit might be worth, especially as the company leans on scale in natural gas liquids and related volumes.
- The analysts covering ONEOK have run their own numbers. See what analysts think ONEOK's shares could be worth.
The stock's next move may depend on whether ONEOK's current earnings are strong enough to justify today's price tag.
If you are weighing whether ONEOK's earnings still back up this run, it can help to compare the stock with 30 high quality undervalued stocks as another starting point for research.
Is ONEOK Still Cheap on Earnings?
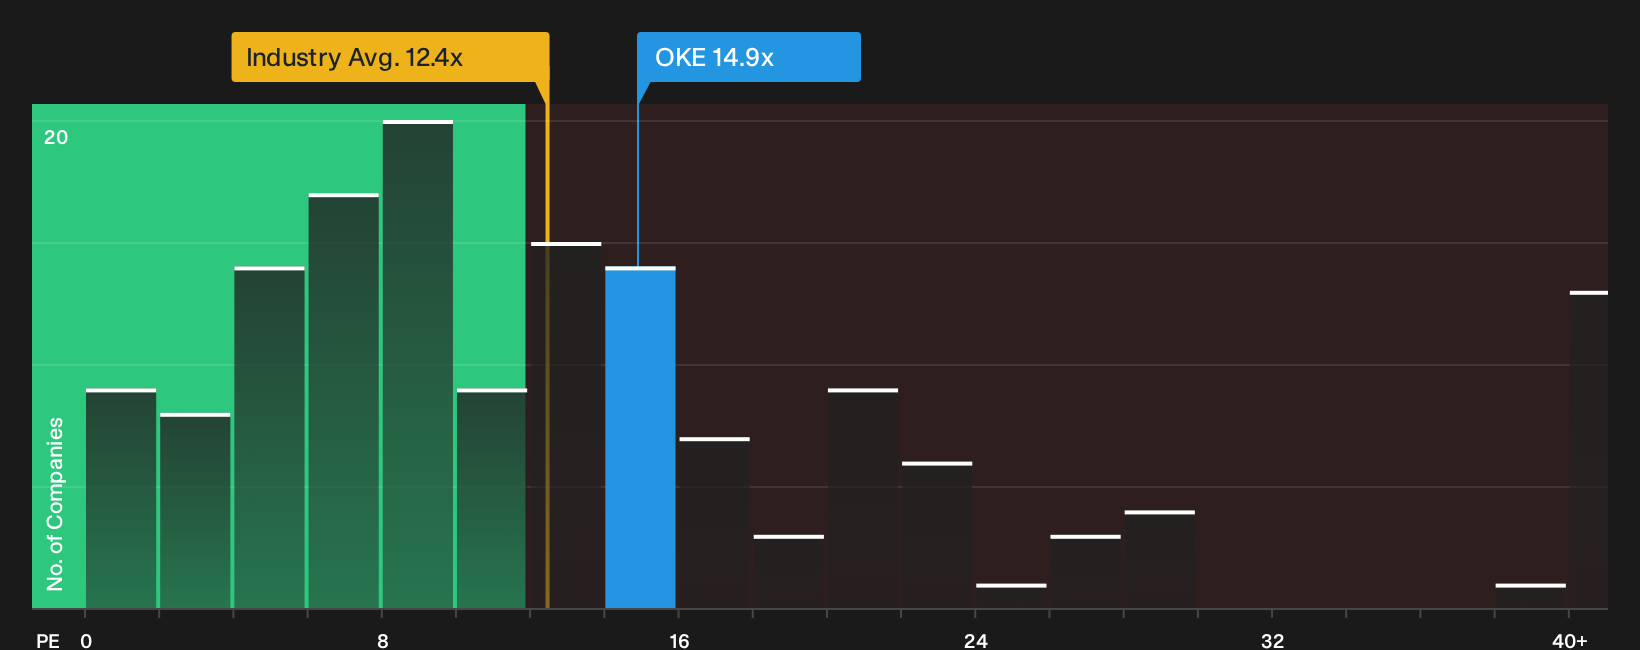
The P/E ratio is a clean way to see what investors pay for each dollar of ONEOK earnings. On this measure, the stock trades on about 14.9x, which is below the oil and gas sector average of roughly 12.4x yet still under the peer group near 19.4x.
That mix of discount to peers but premium to the sector lines up with the tailored fair multiple, which implies ONEOK is undervalued on earnings rather than stretched. Because management recently lifted 2026 earnings guidance after strong Q3 results, the current P/E suggests the market price has not fully chased that improved outlook in line with similar companies. For a holder, the key question is whether the business can keep converting those profits into cash flow at a level that eventually closes the gap implied by this earnings-based valuation. Explore the numbers behind ONEOK's P/E valuation.
The ONEOK Narrative: What Would Justify Today's Price?
ONEOK's valuation question sets up the role of Simply Wall St Narratives. These are short, opposing views on what would need to happen to ONEOK's earnings power, margins and growth profile for the stock to be worth a lot more or a lot less than today. Each narrative treats fair value as a thesis about the business that can be revisited over time, rather than a one off number on a page. They sit on the Community page.
Bullish holders of ONEOK see long term projects and export scale pointing to more value, while cautious investors think a lot is already in the price.
Bull case: 6% undervalued
"Growing exposure to export markets through the Texas City LPG export joint venture, which is being built for 200,000 barrels per day of capacity…"
Discover why this Narrative puts ONEOK at 6% undervalued.
Bear case: 5% overvalued
"Although ONEOK is using its integrated multi-molecule footprint to support capital-efficient volume growth across NGLs, gas, crude and refined products…"
Explore why this Narrative puts ONEOK at 5% overvalued.
Before acting on ONEOK's valuation, remember who is steering the ship
The share price reflects earnings, but the real leverage often sits with the people setting priorities, allocating capital and rewarding themselves for specific outcomes. See who runs ONEOK and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com