


Learn Why The Bull Case For Nova Stock Could Change Following Investor Backing
- Nova Ltd. has been in focus after investor letters and recent coverage pointed to solid fundamentals, including 23.4% annual revenue growth over five years, strong operating margins, and significant earnings per share expansion supported by demand for metrology tools in semiconductor manufacturing.
- An interesting angle is that Nova’s forward P/E of 26.3x is being evaluated alongside analyst estimates of a 55.5% implied return, which highlights how current pricing is weighed against the firm’s metrology role in increasingly complex chip production flows.
- We will examine how Nova’s investment narrative aligns with the renewed focus on its revenue growth and earnings strength within semiconductor demand.
Nova Investment Narrative Recap
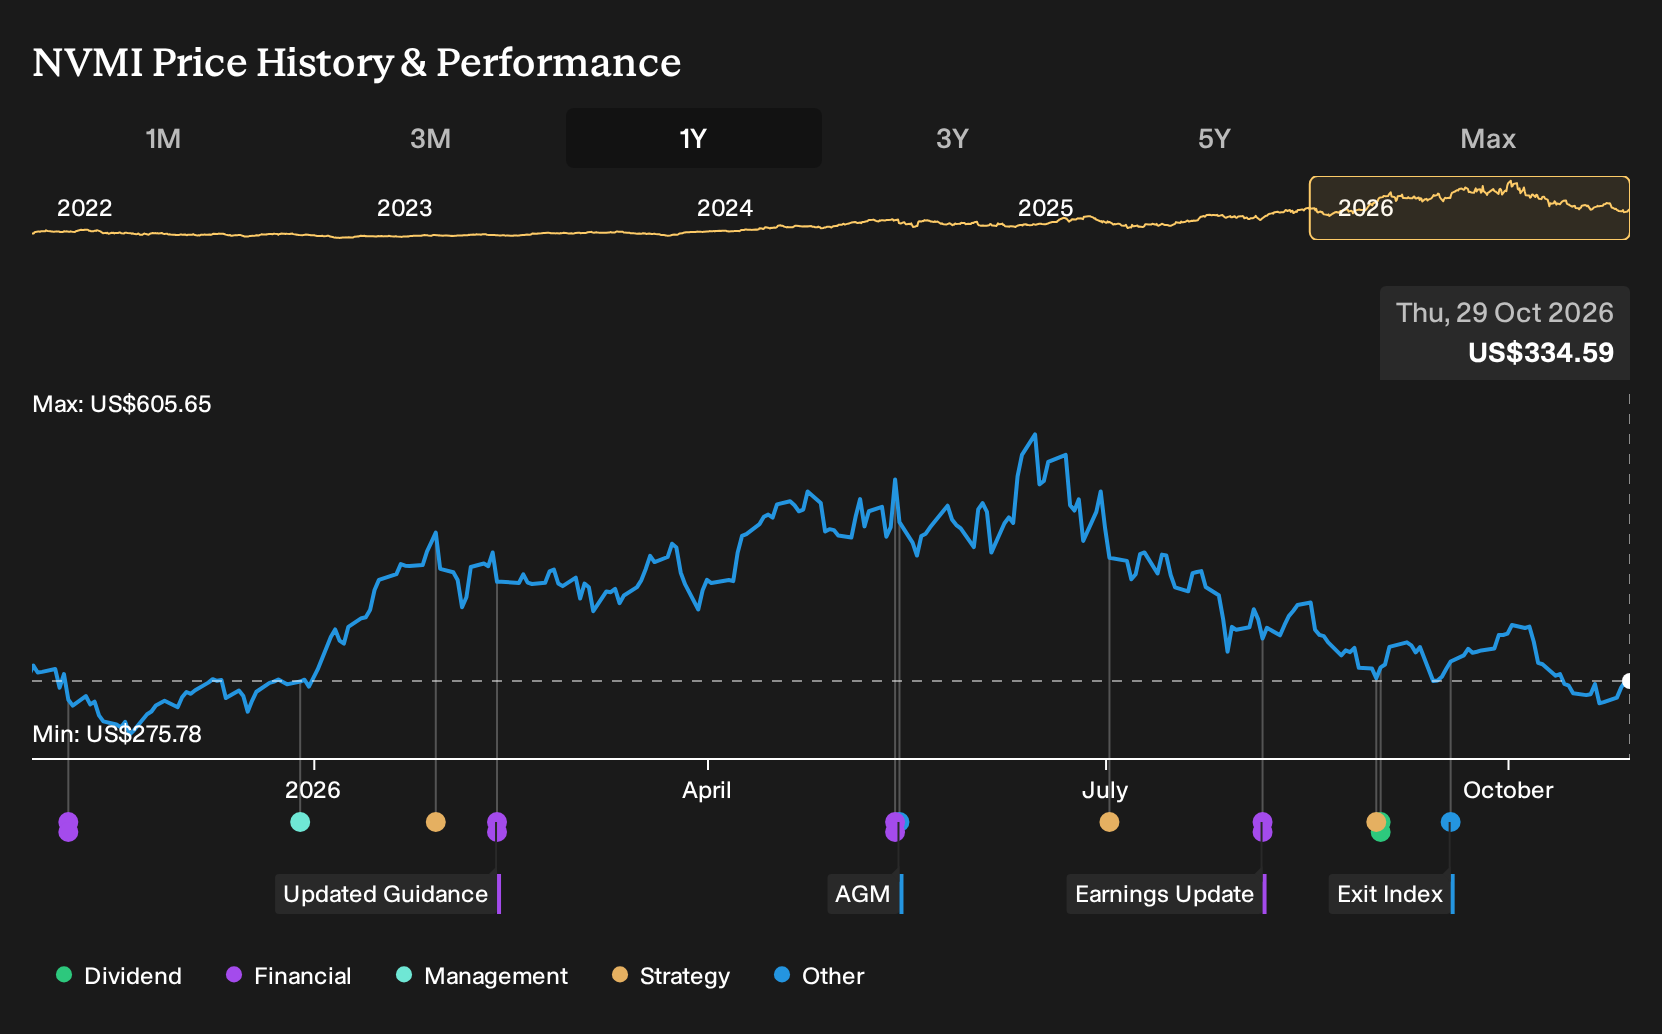
To hold Nova, you need to believe metrology intensity stays central to chip production as nodes shrink and packaging becomes more complex. The short term swing factor is how quickly orders tied to AI infrastructure spending stabilise after the recent sector wide sell off, since that sentiment hit has come despite solid reported execution and profitability.
The biggest operational risk right now is product demand skewed toward DRAM, 3 nm and NAND upgrades that do not fully use Nova tools, along with China exposure near 30% where local competitors are gaining ground. If that mix or share pressure lingers, revenue and margin progress could be harder to sustain.
The most relevant development is the Wasatch Global Investors Q3 2026 letter, which called out Nova as a higher quality AI infrastructure holding even as the stock declined with the broader group. That matters for you because it separates short term sentiment around AI spending from the underlying order book for metrology platforms.
Operationally, the letter reinforces that the key drivers remain metrology demand from advanced logic, memory and packaging customers, plus Nova’s push into software analytics and materials metrology such as XPS, XRF, Elipson and Metrion. The risk is that sector wide multiple compression keeps weighing on the share price even if those catalysts keep playing out inside the business.
Nova's current analyst framework assumes revenue will grow by 22.6% a year and points to earnings today of $270.4 million rising to a consensus of $569.9 million by 2029. This implies earnings a little more than doubling from the current base, supported by a revenue line that is projected to reach $1.7b in the same year.
Discover how Nova's fair value indicates a 54% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One bullish twist on Nova focuses on acquisitions rather than just organic metrology demand. Before this AI infrastructure sell off, the most optimistic analysts were building in about $1.9b in revenue and $587.2 million in earnings by 2029. Those upbeat assumptions may be revisited as this latest news settles in.
Explore 3 other Nova fair value estimates, including one that suggests as much as 54% upside from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Nova research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Nova. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Nova's overall financial health at a glance.
Looking For More Ideas Beyond Nova?
If Nova's metrology and AI infrastructure angle fits your thinking, it can help to compare it with other businesses that share similar financial qualities or income profiles. Use the Simply Wall St Screener to widen your watchlist and see how Nova stacks up against different types of opportunities.
- If resilience and balance sheet strength matter most to you, start with a list of solid balance sheet and fundamentals (23 results) that keep financial risk in check while you focus on the upside story.
- If you want income on top of potential capital gains, scan for 7 dividend fortresses that prioritise reliable payouts and strong cash generation.
- If you are hunting for under-covered opportunities, widen the search to 18 high quality undiscovered gems that pair quality fundamentals with relatively low market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com