


What ResMed (RMD)'s Earnings Beat Means For Shareholders
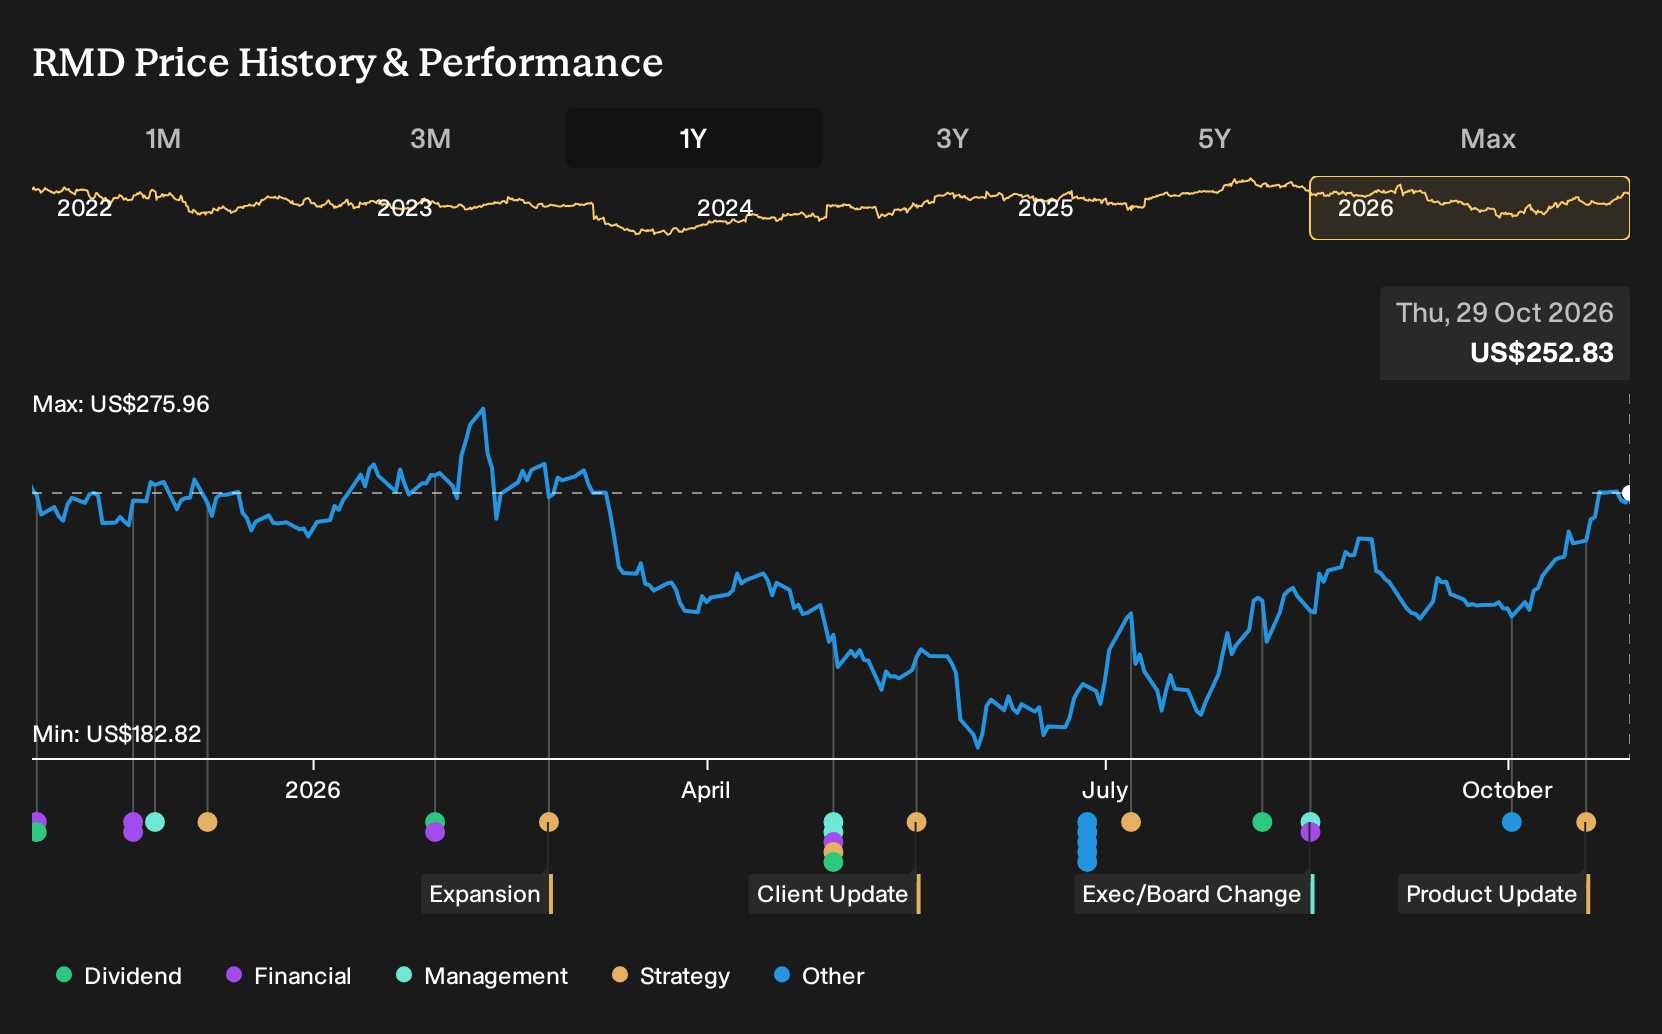
- ResMed reported first quarter 2027 results with sales of US$1,414.81 million, net income of US$418.41 million, and diluted EPS of US$2.92, all higher than the prior year period.
- The launch of the AirTouch F40 fabric CPAP mask, designed for comfort and long term adherence and integrated into ResMed’s connected platform, reinforces how new products and digital tools tie directly into therapy usage and potentially more resilient recurring revenue.
- We will now look at how ResMed’s stronger earnings and the AirTouch F40 launch might influence the broader investment narrative around the stock.
Scan how ResMed’s earnings strength and new product launch compare with other healthcare equipment players by zeroing in on 36 healthcare AI stocks that focus on similar digital therapy themes.
ResMed Investment Narrative Recap
To own ResMed, you need to believe its sleep and breathing health platform can keep pulling more patients into connected therapy and keep them compliant over time. The latest quarter delivered higher sales of US$1,414.81 million and net income of US$418.41 million. This supports that thesis and also gives management more room to fund product and software development.
The near term swing factor still sits in execution on supply chain productivity and cost control, especially with inflation pressure and the Astral corrective action already flagged as a drag for FY2027. The Astral issue remains the biggest operational risk, and the fresh earnings beat does not materially change that.
The AirTouch F40 launch is the clearest operational link between the quarter and future catalysts. It ties directly into ResMed’s goal of improving adherence, with the firm highlighting a 6% uplift in 90 day compliance for fabric cushions versus silicone in its broader portfolio, and fit claims of up to 96% of users.
Because AirTouch F40 plugs into myAir and AirView, it leverages the connected ecosystem that many investors already see as key to recurring revenue from masks and resupply. Execution risk sits in uptake, pricing and any added complexity for providers, but strong early integration into ResMed’s digital tools may help support the sleep and breathing health segment while Astral related headwinds play out.
ResMed's current analyst narrative points to forecast revenues of US$6.6b and projected earnings of US$1.9b by 2029, based on an assumed 5.2% yearly increase in revenue and an earnings uplift of about US$400m from US$1.5b today.
Discover why ResMed's fair value suggests that the valuation is approximately in line with its current price.
Exploring Other Perspectives
Some of the most optimistic analysts see ResMed’s CPAP ecosystem as a much bigger story than the Astral risk. Before this quarter’s AirTouch F40 launch and earnings beat, the bullish camp was already sketching out revenue near US$6.8b and earnings around US$1.8b by 2029. You can compare those assumptions with your own and decide which narrative feels closer to how you see the business, especially now that fresh results may reshape forecasts.
Explore 5 other ResMed fair value estimates, including one that suggests as much as 43% potential upside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your ResMed research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for ResMed. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate ResMed's overall financial health at a glance.
Looking For More Investment Ideas Beyond ResMed?
If ResMed has sharpened your focus on healthcare and recurring revenue, it can help to widen the lens and compare it with other types of opportunities. The Simply Wall St Screener lets you quickly sift through different groups of stocks so you can build a watchlist that fits your own risk and income preferences.
- If capital preservation comes first for you, start with companies that show steadier profiles and check out 30 resilient stocks with low risk scores for a shortlist of candidates that may better suit a cautious approach.
- For investors hunting for quality at a reasonable entry point, focus on businesses that pair solid fundamentals with appealing valuations and review the 30 high quality undervalued stocks as a potential hunting ground.
- Income focused portfolios can benefit from reliable cash distributions, so it may be worth scanning the 7 dividend fortresses if you want stocks that emphasise yield alongside stability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com