


Penske Automotive Group (PAG) Stock Faces A Q3 Results Margin Squeeze
Penske Automotive Group barely flinched on the screen today, with the stock easing just 0.1% after its Q3 2026 release. For a dealer group this size, that kind of muted reaction can lull you into thinking the quarter was forgettable. It was not. Management posted Basic earnings per share of US$3.36 on revenue of US$8.42b, numbers that sit inside an ongoing squeeze in profitability.
In the short term, traders see a flat chart. Over a multi year horizon, long term holders are weighing that profit pressure against a valuation framed by a discounted cash flow model and a mid teens P/E.
Like Penske Automotive Group's scale and earnings power but uneasy about the squeeze in profitability? See how it stacks up against other cash generative operators in our list of solid balance sheet and fundamentals stocks (24 results)
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs. Q3 2025): US$8,415.6m vs. US$7,695.3m (top line increased by about 9.4%)
- Net Income, excl. extra items (Q3 2026 vs. Q3 2025): US$220.8m vs. US$213.0m (profit rose by roughly 3.7%)
- Basic EPS (Q3 2026 vs. Q3 2025): US$3.36 vs. US$3.23 (per share earnings improved by around 4.2%)
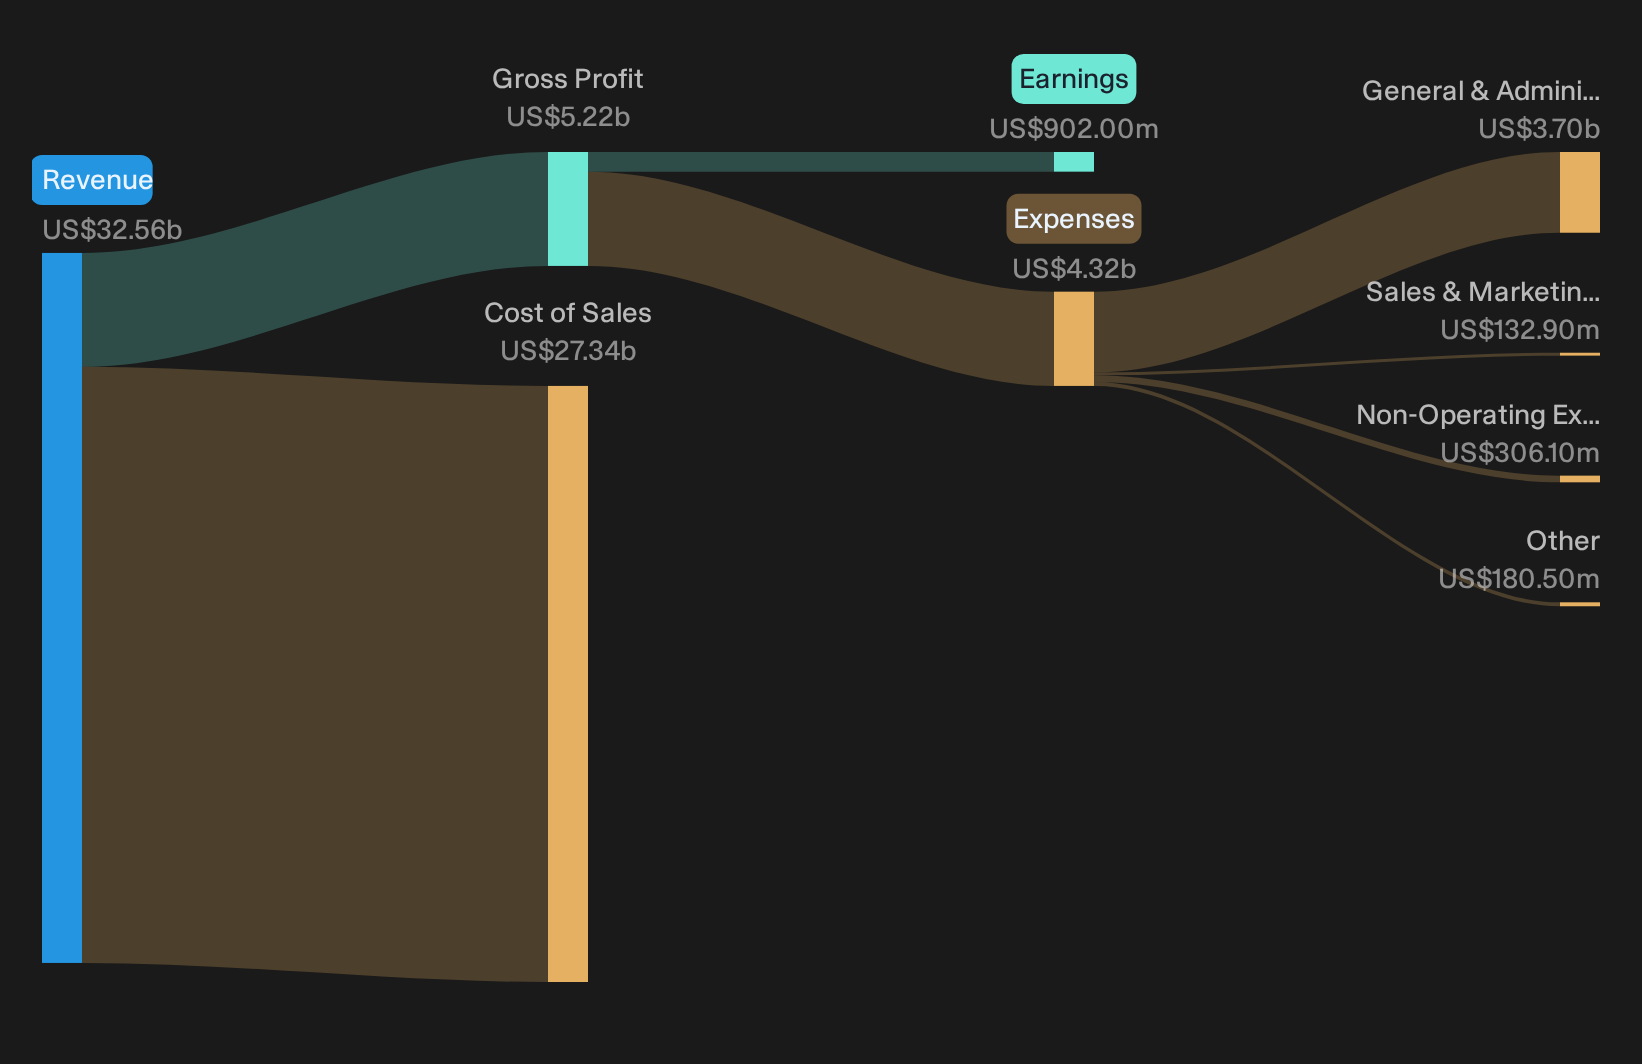
- Trailing 12 month net income, excl. extra items (Q3 2026 vs. Q3 2025 TTM): US$902.0m vs. US$1,023.7m (earnings on a rolling 12 month basis declined about 11.9%)
Earnings tell part of the story, but investors who care about valuation usually want to see what the cash is doing as it moves through Penske Automotive Group's engine room. Looking at Penske Automotive Group's cash flows alone, the stock could be a dramatic 43% undervalued.
Penske Automotive’s Service Ambition Meets Mixed Evidence
The bullish view hinges on Penske Automotive Group steadily tilting toward richer, recurring work rather than one off vehicle sales.
"The main thing that has to go right is continued execution in higher margin service, parts, and long-life maintenance contracts across auto, truck, and energy solutions, while managing pressure in weaker markets and battery electric vehicle demand."
Q3 results show some support for that ambition. Revenue and quarterly net income both rose, and prior quarters highlighted stronger service, parts and truck activity. Yet trailing 12 month earnings moved lower, which suggests that, so far, the shift into higher margin, longer duration contracts has not fully offset broader profitability pressure.
One Narrative has put a figure on that disagreement. → See the Narrative with its higher Fair Value, assumptions and all.
Penske Automotive’s Cost Problem Still In The Frame
Bearish investors argue that Penske Automotive’s fixed cost base is creeping higher even as the business leans harder on services and projects.
"Although Penske Automotive Group has reiterated an ambition to keep SG&A in the low 70s as a percentage of gross profit, the ratio has instead drifted higher year over year, with Q1 2026 at 74.3% and Q2 2026 at 71.8%."
Q3 delivers higher quarterly revenue and net income, yet trailing 12 month earnings slipped from US$1,023.7m to US$902.0m. That gap is hard to square with the cost ambition in the quote. It points to profitability still feeling the strain of that heavier expense load.
Hunt For Quiet Fundamental Shifts
Penske Automotive Group reported a quarter where earnings power and cost pressure are competing. The real opportunity sits in finding stocks that could be undervalued before stronger fundamentals are fully reflected in valuations.
- Company 1 - 23% below our estimate - ties enterprise cloud, workplace software and AI copilots into one integrated stack.
- Company 2 - 25% below our estimate - builds a cardiometabolic drug franchise that depends on scaling manufacturing and payer coverage.
- Company 3 - 38% below our estimate - runs a device recommerce platform that benefits as trade in subsidies steer used phones into formal channels.
Those are three of them. See every one of the 29 undervalued companies on it →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com