


Dassault Systèmes (ENXTPA:DSY) Stock Price Shrugs Off Q2 Earnings Strength
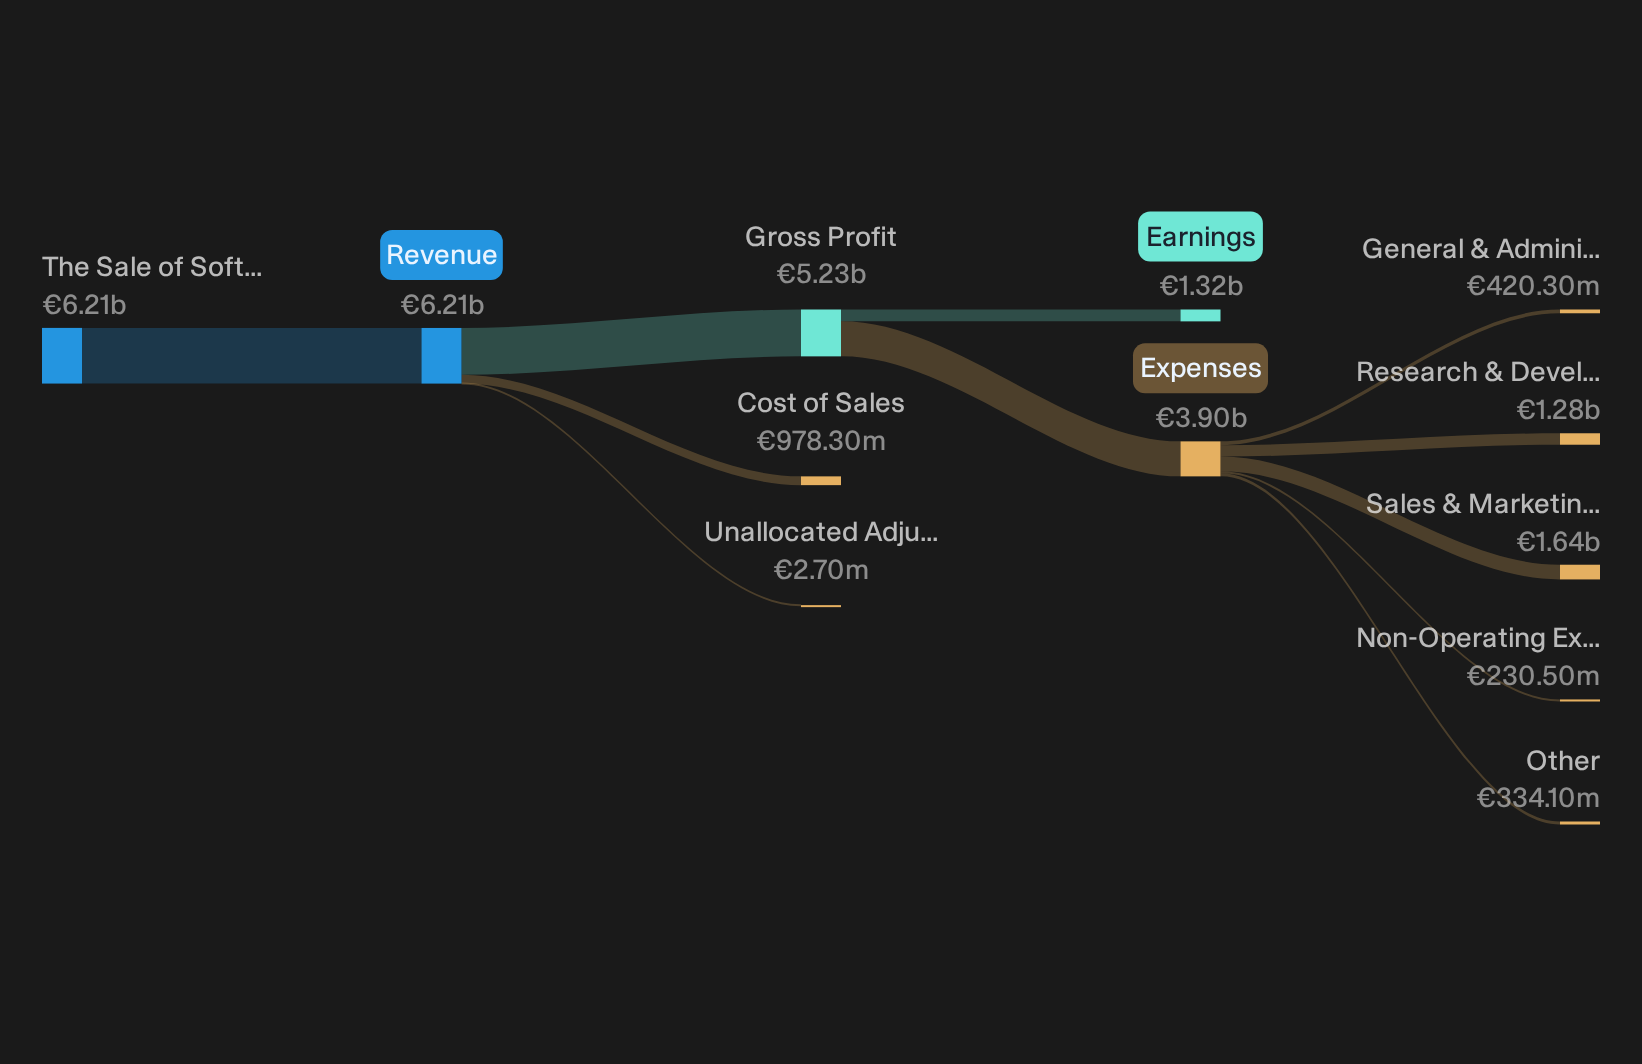
Dassault Systèmes heads into this post earnings window with the stock at €23.58 and a flat 7 day return, even after a steady 90 day gain of about 16.7%. Traders barely flinched, yet the Q2 2026 print landed with solid cash generation and a clearer margin picture.
EPS of €0.24 and net income of €319.3m matter less on their own than what they indicate about the business model. For a software and platforms group built on recurring contracts, the focus is on multi year earnings power and the valuation gap that patient holders are weighing today.
If you appreciate the resilience of Dassault Systèmes’ recurring earnings but want more choices with similar quality and balance sheet strength, compare it with our list of list of solid balance sheet and fundamentals stocks (207 results).
Q2 2026 Earnings Summary
- Total Revenue (Q2 2026 vs Q2 2025): €1,555.8m vs. €1,521.6m (up about 2.2%)
- Net Income (Excl. Extra Items, Q2 2026 vs Q2 2025): €319.3m vs. €223.5m (up about 42.9%)
- Basic EPS (Q2 2026 vs Q2 2025): €0.2418 vs. €0.1714 (up about 41.1%)
- Net Profit Margin (Trailing 12 Months vs Prior Year): 21.3% vs. 18.0% (wider by about 3.3 percentage points)
Earnings tell you how Q2 landed, but cash flow is what many valuation focused investors watch when they want to judge the staying power of those numbers. When you line up Dassault Systèmes' cash flows against the current share price, the stock could be a modest 12% undervalued.
Dassault Systèmes’ AI and Life Sciences Milestones Tested
Supporters argue that Dassault Systèmes is shifting from legacy design tools toward higher value AI and life sciences platforms that can compound recurring revenue.
"Bullish analysts expect Dassault Systèmes to compound high quality recurring revenue as AI-native 3DEXPERIENCE and Medidata Plus usage broadens across engineering and life sciences workflows."
Q3 results provide some concrete reference points. 3DEXPERIENCE revenue rose 25% and cloud activity advanced 14%. ARR increased 6% to €4.505b, and subscription reached about half of recurring ARR. Life sciences performance is mixed. Medidata was flat in Q3 after an earlier Q2 revenue decline, while ArisGlobal’s closing and Medidata’s market recognition indicate tangible but still developing traction in that workflow story.
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for.
Dassault Systèmes: Testing Fears On Life Sciences Drag
Bears argue that Dassault Systèmes’ life sciences arm could cap growth and earnings even as cloud and subscriptions climb.
"Despite Medidata ARR turning positive and the Medidata Plus AI layer showing early adoption, the drag from Medidata revenue down 3% in both Q1 and Q2 2026 and weak prior year bookings signals that life sciences may continue to dilute overall growth and limit near term EPS upside."
Q3 shows that concern is only partly playing out. Medidata is now flat rather than falling, yet not back to growth, so the overhang is not cleared. Group revenue and EPS are rising, with a higher full year outlook, which undercuts the idea that life sciences weakness is still diluting overall earnings momentum this year.
Track Fresh Earnings Dislocations
Dassault Systèmes just reported results that showed a steady performance alongside a muted share reaction. The real opportunity sits in stocks that could be undervalued before the market adjusts.
- Company 1 - 18% below our estimate - sell software-defined routers forming the backbone for satellite links and physical AI fleets needing reliable multi-network access.
- Company 2 - 35% below our estimate - run contract electronics plants handling long dated defense and electrification orders as clients lock in capacity for complex embedded systems.
- Company 3 - 37% below our estimate - build an integrated platform moving mature drug lines to lower cost plants while scaling higher margin formulations for companion and farm animals.
Those are three of them. See every one of the 195 undervalued companies on it →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com