


Service International’s (NYSE:SCI) Q3 2026: beats on revenue but stock drops
Funeral services company Service International (NYSE:SCI) beat Wall Street’s revenue expectations in Q3 2026, with revenue rising 4.6% year on year to $1.11 billion. Its non-GAAP profit of $0.97 per share was 2.1% below analysts’ consensus estimates.
For more on Service International, read our free full research report.
Service International (SCI) Q3 2026 highlights:
- Revenue $1.11 billion vs S&P analysts’ consensus estimates of $1.10 billion (4.6% year-on-year growth, 0.6% beat)
- Adjusted EPS $0.97 vs S&P analysts’ consensus estimates of $0.99 (2.1% miss)
- Adjusted EPS guidance Management lowered its next quarter adjusted EPS guidance to $1.15 at the midpoint
- Operating margin 22.8%, up from 21.4% in the same quarter last year
- Free cash flow margin 26.8%, up from 14.2% in the same quarter last year
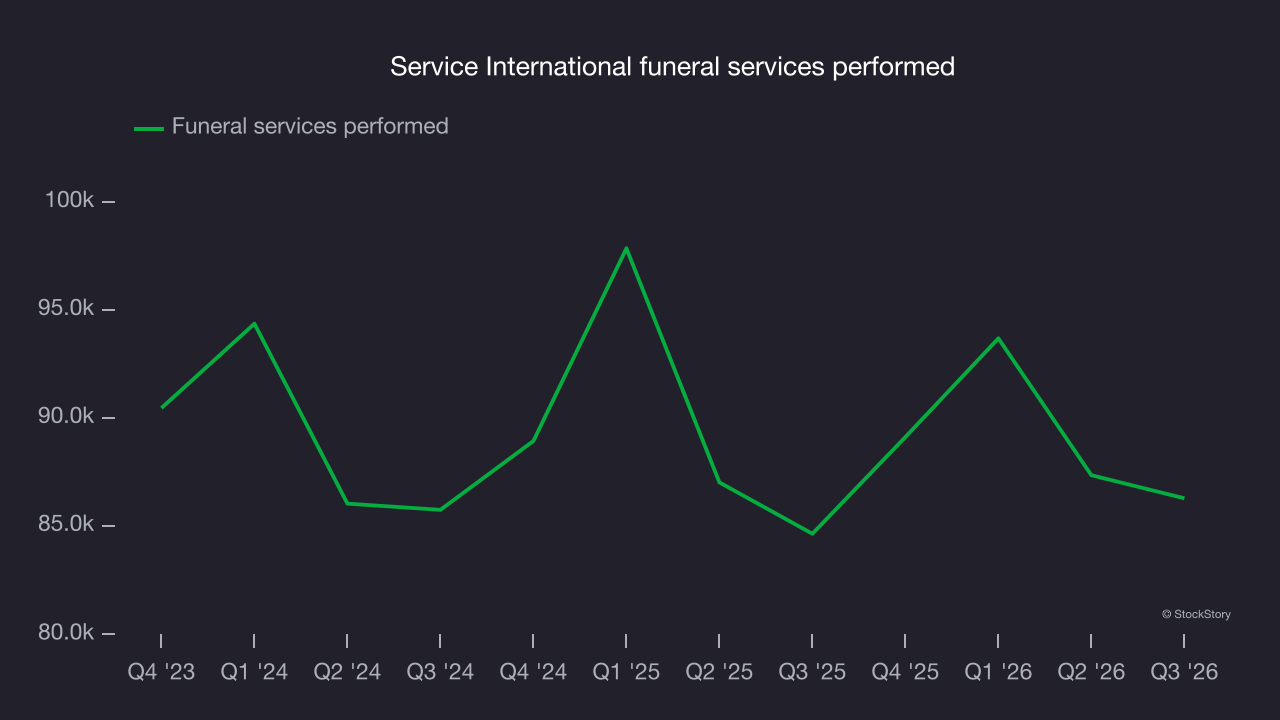
- Funeral services performed increased by 1,642 year on year
- Market capitalization $11.25 billion
Revenue growth
A company’s long-term performance is an indicator of its overall quality. Any business can have short-term success, but a top-tier one grows for years. Service International’s revenue grew at a weak 1.7% annualized rate over the last five years, falling short of our standards.
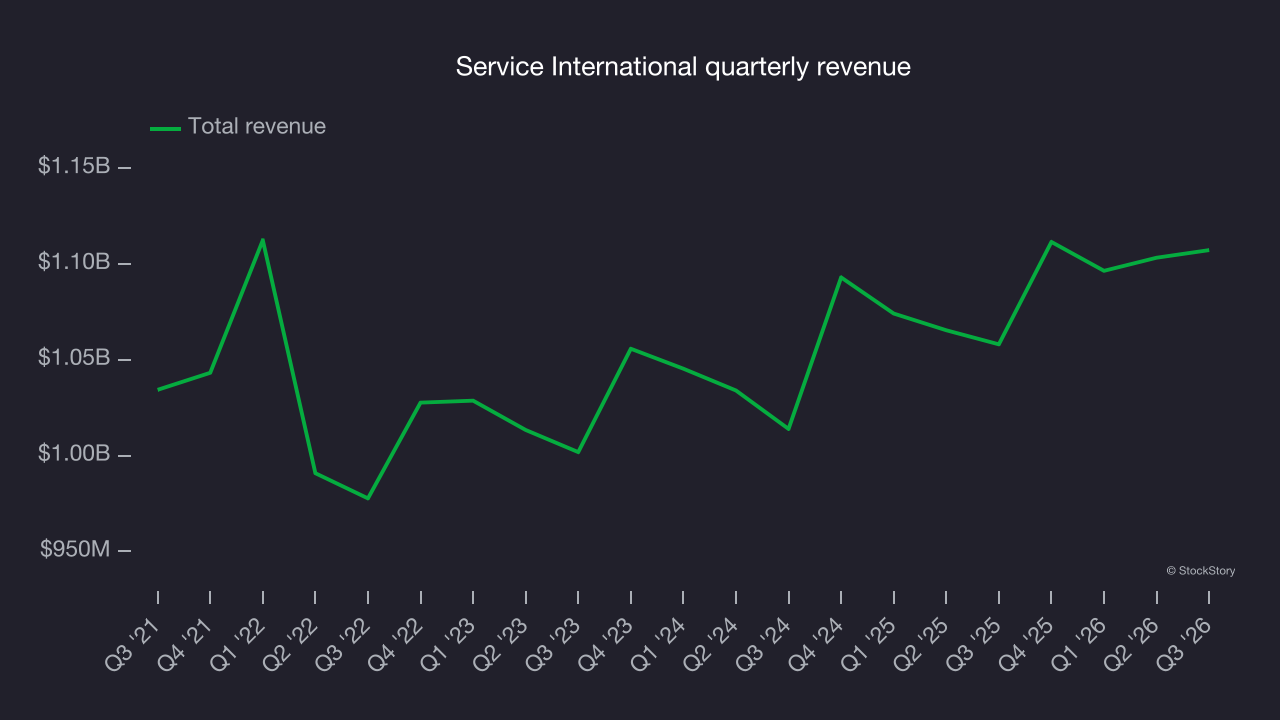
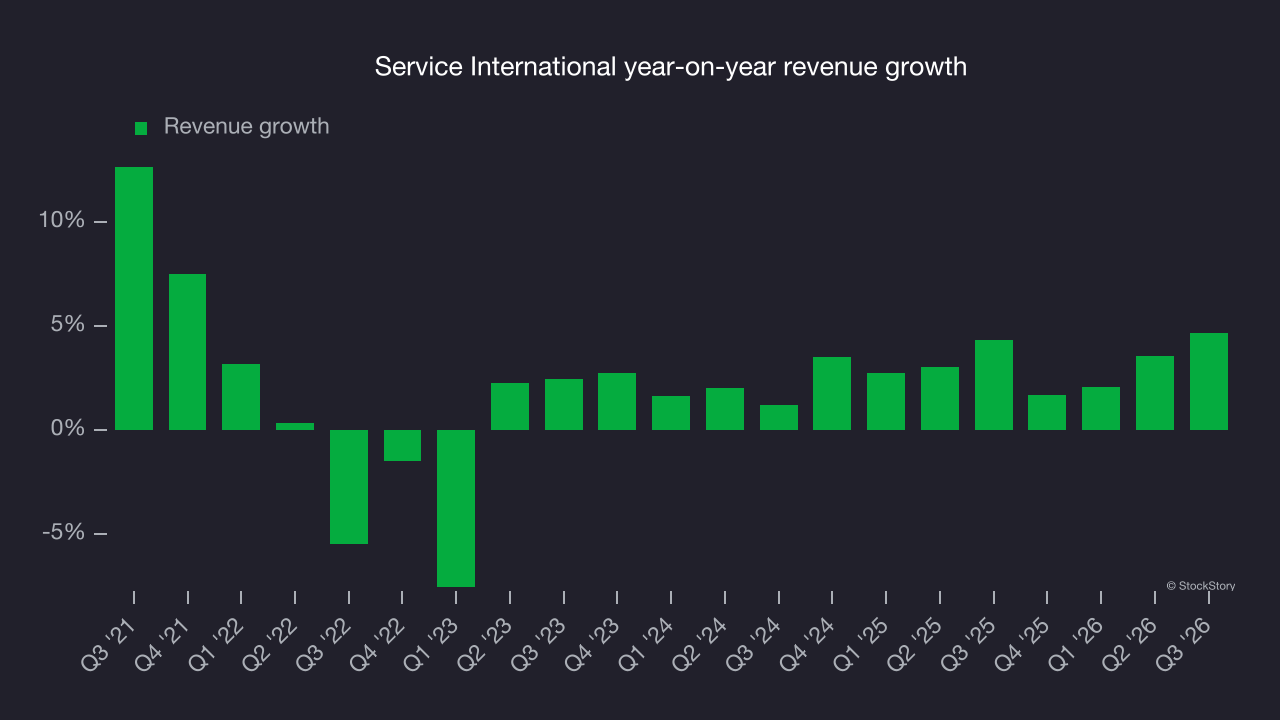
This quarter, Service International reported modest year-on-year revenue growth of 4.6% but beat Wall Street’s consensus estimates by 0.6%.
Looking ahead, sell-side analysts expect revenue to grow 3.9% over the next 12 months, according to S&P, similar to its two-year rate. This projection is underwhelming and suggests its newer products and services will not catalyze better top-line performance yet.
Operating margin
Service International’s operating margin has remained largely unchanged over the last 12 months, and margin increases driven by economies of scale and cost efficiency are generally preferable over time.
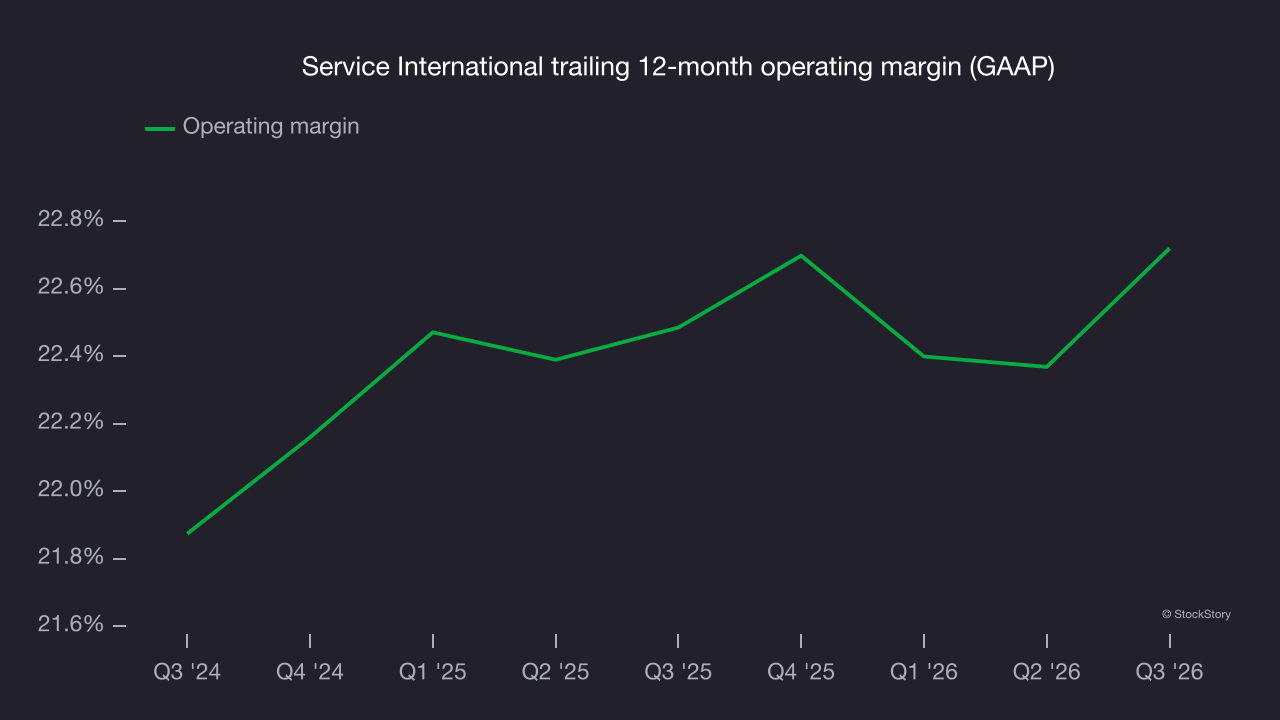
This quarter, Service International generated an operating margin of 22.8%, up 1.4 percentage points year on year. This increase was a positive development and showed improved efficiency.
Earnings per share
We track the long-term change in earnings per share (EPS) for the same reason as long-term revenue growth. Compared to revenue, however, EPS highlights whether a company’s growth is profitable.
Service International’s EPS declined by 2.6% annually over the last five years while its revenue grew by 1.7%. This indicates the company became less profitable on a per-share basis as it expanded due to non-fundamental factors such as interest expenses and taxes.
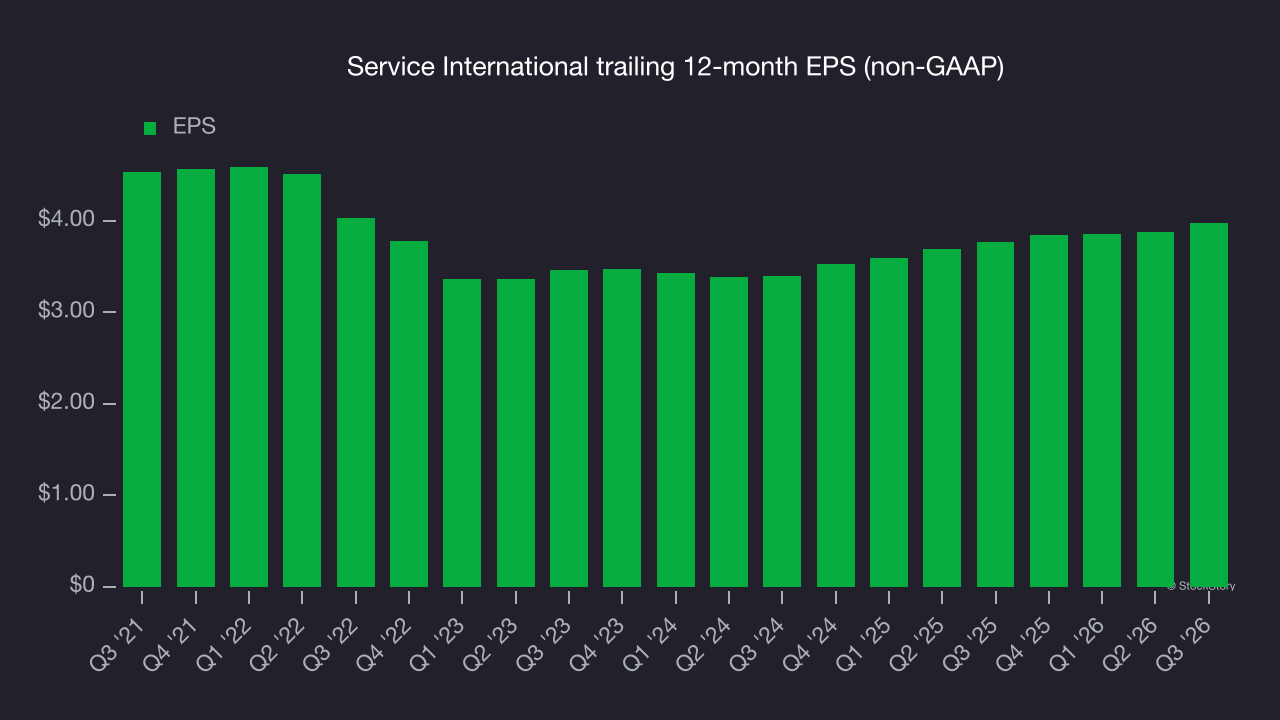
In Q3, Service International reported adjusted EPS of $0.97, up from $0.87 in the same quarter last year. Despite growing year on year, this result missed analysts’ consensus estimates. Over the next 12 months, Wall Street expects Service International’s full-year EPS to grow 13.3% from $3.98 to $4.51, according to S&P.
Key takeaways from Service International’s Q3 results
Service International’s quarter offered few positives: EPS fell short of Wall Street’s consensus estimates, and next quarter EPS guidance also missed expectations. Those shortfalls made for a weaker quarter. Shares tumbled 7.2% to $76.38 immediately after the results.
Service International may have had a tough quarter, but that alone doesn’t determine whether the stock is a buy. The latest quarter matters, but not nearly as much as longer-term fundamentals and valuation when making that decision. For more on these factors, read the full research report here (it’s free).