


CBIZ (CBZ) Stock Looks Reasonable Following Its $5.0B Take Private Deal
CBIZ has put together a steady share price story over the past several years, yet the real question today is how much of that performance is actually supported by its earnings power. With a pending buyout on the table, the stock's current valuation invites closer inspection of what the underlying profits may justify.
- Over the past 5 years, CBIZ has delivered a 45.3% share price gain, which puts real weight on whether the business's earnings profile matches that kind of payoff.
- The agreed all cash acquisition by Grant Thornton, valuing CBIZ at US$5.0b and taking it private, can shape what investors infer about growth expectations and the durability of future profit streams.
- Your read on CBIZ is one view; the desks covering it have another. See what analysts think CBIZ's shares could be worth.
The stock's next move may depend on whether CBIZ's current price can be explained by the earnings it generates today and is expected to produce in the future.
If you are weighing whether CBIZ's buyout price fits its earnings profile, it can help to compare it with a wider field of 29 high quality undervalued stocks.
Where Does CBIZ Sit on Earnings?
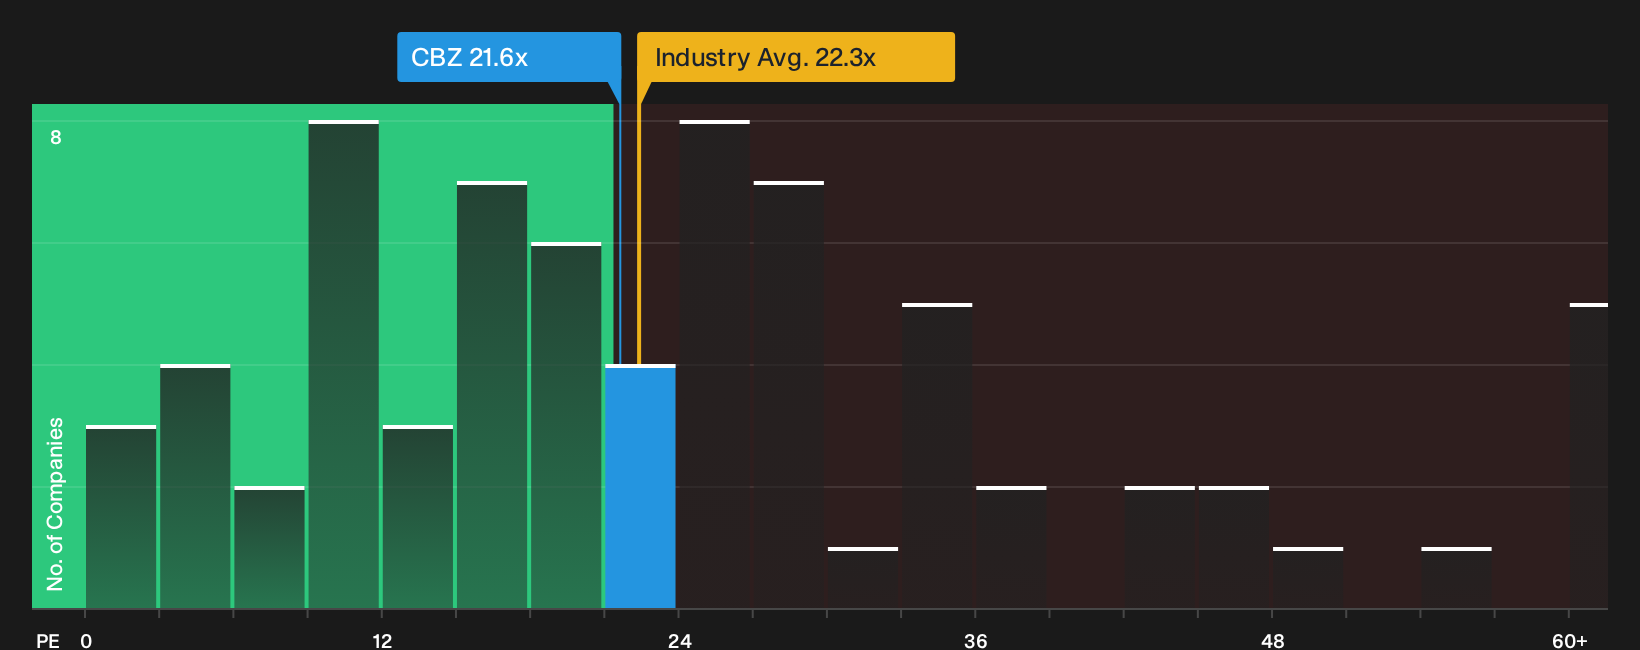
The P/E ratio fits CBIZ because earnings are a key driver for service firms that do not rely heavily on physical assets. CBIZ trades on a P/E of 21.6x, which sits slightly below the Professional Services industry average of 22.3x and under the peer group on about 25.2x. That places the stock on a valuation that does not stretch far above what investors are paying for similar businesses in the sector.
The Fair Ratio model, which adjusts for CBIZ's own growth profile, margins, size and risk, points to a level close to where the shares now trade. As a result, the current 21.6x multiple lands near that line rather than far above or below it. Because the proposed US$5.0b all cash acquisition by Grant Thornton anchors expectations around deal terms, the market P/E signals that investors are not paying a large premium over what comparable Professional Services companies command. Explore the numbers behind CBIZ's P/E valuation.
The CBIZ Narrative: What Would Justify Today's Price?
Narratives pick up where CBIZ's valuation puzzle leaves off by spelling out which assumptions on future growth, profitability and earnings power would need to hold for the business to be worth materially more or less than its current price on Simply Wall St's Community page. Rather than stopping at a single P/E or model snapshot, each scenario lays out the earnings and margin path it assumes so you can track those expectations against CBIZ's actual results over time.
One of the top community narratives on CBIZ: roughly fairly valued
"CBIZ is rolling out AI enabled workflows across attest and other services, including one use case that is already delivering 20% efficiency…"
Discover why this Narrative puts CBIZ at roughly fairly valued.
One more CBIZ check that belongs beside the share price
Numbers only tell part of the story, because the people steering CBIZ and the way their pay is structured can heavily influence the choices that shape future results. See who runs CBIZ and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com