


Hulic (TSE:3003) Stock Could Be A Bargain After Its 95% Run
Hulic has delivered a strong 94.8% share price gain over the past 5 years, and the question now is whether that move still lines up with what its earnings can reasonably support. With the stock recently closing at ¥1,744.5, investors are asking if the current valuation is grounded in the profit engine of the underlying real estate portfolio or leaning too much on sentiment.
- Hulic's 94.8% return over 5 years places real focus on whether today's market value is still anchored to its earnings power.
- The recent US$176m joint acquisition of a 312 unit multifamily property in San Jose may support expectations for more stable rental income and could influence how investors think about the durability of Hulic's earnings stream.
- The analysts covering Hulic have run their own numbers. See what analysts think Hulic's shares could be worth.
The issue now is whether Hulic's current share price is adequately justified by its earnings when set against the Fair Ratio benchmark.
If you are weighing whether Hulic's 94.8% five year return is still supported by its earnings, it can help to compare that question across 16 high quality undervalued stocks.
Is Hulic a Bargain on Earnings?
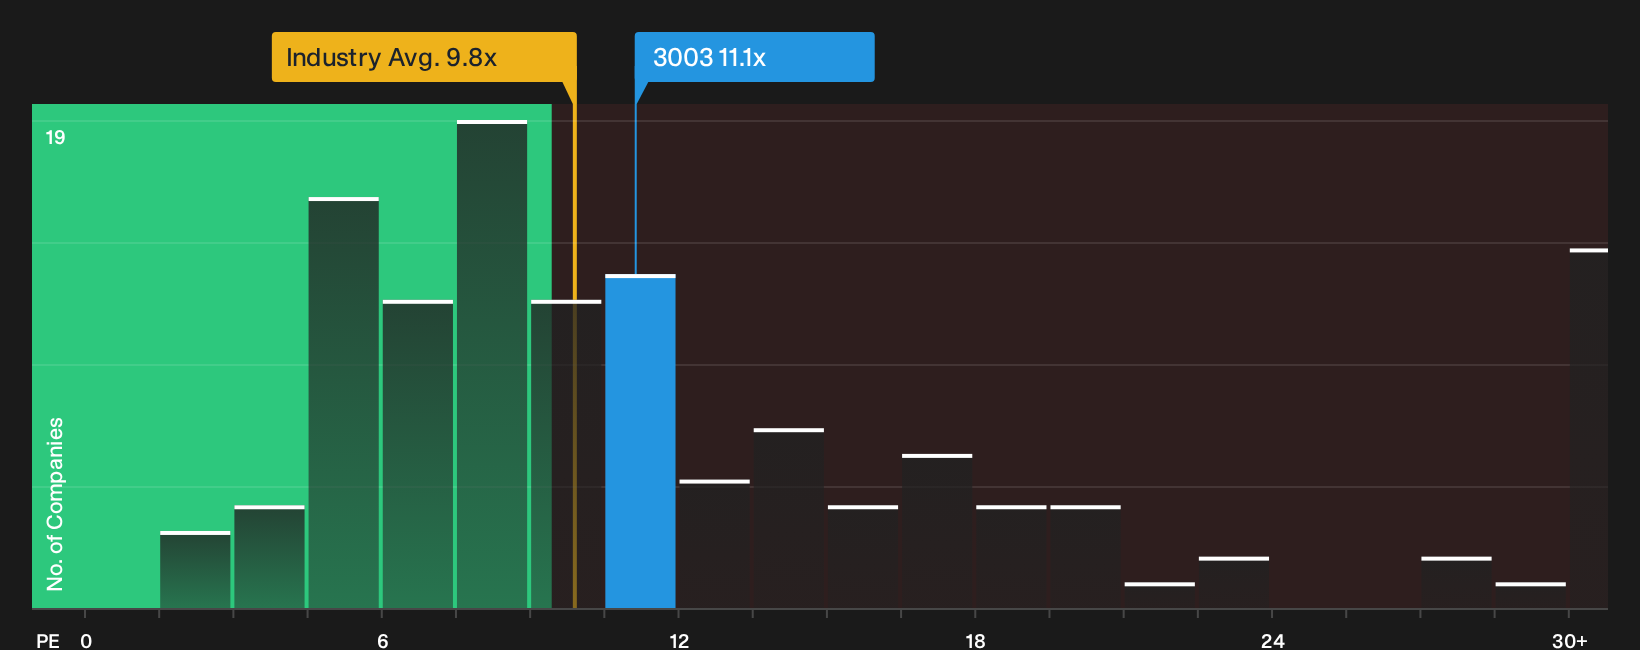
For Hulic, earnings are a central reference point because real estate profits tend to be relatively visible once assets are leased and stabilised. The stock trades on a P/E of about 11.1x, which is above the broader real estate sector average of roughly 9.8x but sits well below the peer group level near 18.3x.
Despite the recent US$176m San Jose multifamily purchase lifting interest in Hulic's income potential, the market is still pricing the shares below the multiple suggested by a tailored Fair Ratio that factors in the firm's scale, margins and risk profile. That Fair Ratio sits above the current 11.1x level. On this framework Hulic screens as undervalued on earnings relative to what similar fundamentals might usually command. Explore the numbers behind Hulic's P/E valuation.
The Hulic Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Hulic pick up where the valuation puzzle leaves off. They spell out what kind of future for growth, margins and earnings would need to play out for the stock to be worth meaningfully more or less than today’s price, all collected on the Community page. Each scenario ties Hulic's potential fair value to a specific mix of catalysts and risks so you can track over time which version of events seems to be taking shape.
A written, number-driven view on Hulic helps you pin down what assumptions you are really making about its earnings power and how the recent US$176m San Jose multifamily acquisition might influence future cash flows. Putting that into a clear narrative gives you a reference point you can revisit as new deals, rental data and reported results either support or challenge the original thesis.
Share your own Narrative for Hulic and set out the assumptions behind your valuation.
One more Hulic angle worth checking before you move on
The people steering Hulic and how they are rewarded can heavily shape risk appetite, capital allocation and discipline, yet that piece of the puzzle has not been unpacked here. See who runs Hulic and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com