


3 Global Growth Companies With High Insider Ownership Expecting 38% Earnings Growth
In the current global market landscape, volatility has been driven by AI investment concerns and rising oil prices, with mixed performances across major indices. Despite these challenges, growth companies with high insider ownership can present compelling opportunities as they align management interests with shareholder value and often demonstrate resilience in uncertain times.
Top 10 Growth Companies With High Insider Ownership Globally
| Name | Insider Ownership | Earnings Growth |
| Suzhou Dongshan Precision Manufacturing (SZSE:002384) | 33.5% | 75.1% |
| SEERS (KOSDAQ:A458870) | 33.6% | 37.8% |
| Meitu (SEHK:1357) | 23.1% | 26.5% |
| Meiko Electronics (TSE:6787) | 19.2% | 34% |
| KCTech (KOSE:A281820) | 20.6% | 31.6% |
| Guangdong Shenling Environmental Systems (SZSE:301018) | 36.7% | 65.4% |
| Great Microwave Technology (SHSE:688270) | 21.1% | 104.2% |
| Gold Circuit Electronics (TWSE:2368) | 29.9% | 46.1% |
| Fulin Precision (SZSE:300432) | 11.7% | 67.4% |
| Biocytogen Pharmaceuticals (Beijing) (SEHK:2315) | 14.1% | 39.2% |
Here's a peek at a few of the choices from the screener.
Shenzhen JPT Opto-Electronics (SHSE:688025)
Simply Wall St Growth Rating: ★★★★★☆
Overview: Shenzhen JPT Opto-Electronics Co., Ltd. focuses on the research, development, production, and sales of lasers for precision testing of integrated circuits and semiconductor optoelectronic devices, with a market cap of CN¥30.08 billion.
Operations: The company's revenue segments include the research, development, production, and sales of lasers for precision testing of integrated circuits and semiconductor optoelectronic devices.
Insider Ownership: 24.2%
Earnings Growth Forecast: 32.5% p.a.
Shenzhen JPT Opto-Electronics demonstrates robust growth potential with earnings forecast to rise 32.5% annually, outpacing the Chinese market's average. Recent reports show sales surged to CNY 2.63 billion for the first nine months of 2026, up from CNY 1.51 billion a year prior, while net income more than doubled to CNY 427.93 million. Despite high volatility in share price, its inclusion in major indices like FTSE All-World underscores investor confidence.
- Click here and access our complete growth analysis report to understand the dynamics of Shenzhen JPT Opto-Electronics.
- Upon reviewing our latest valuation report, Shenzhen JPT Opto-Electronics' share price might be too optimistic.
Kinik (TWSE:1560)
Simply Wall St Growth Rating: ★★★★★☆
Overview: Kinik Company produces and sells various abrasives, cutting tools, and reclaimed wafers in Taiwan and internationally, with a market cap of NT$125.04 billion.
Operations: The company's revenue is derived from two main segments: the Electronics Sector, which contributes NT$4.03 billion, and the Traditional Sectors, accounting for NT$5.02 billion.
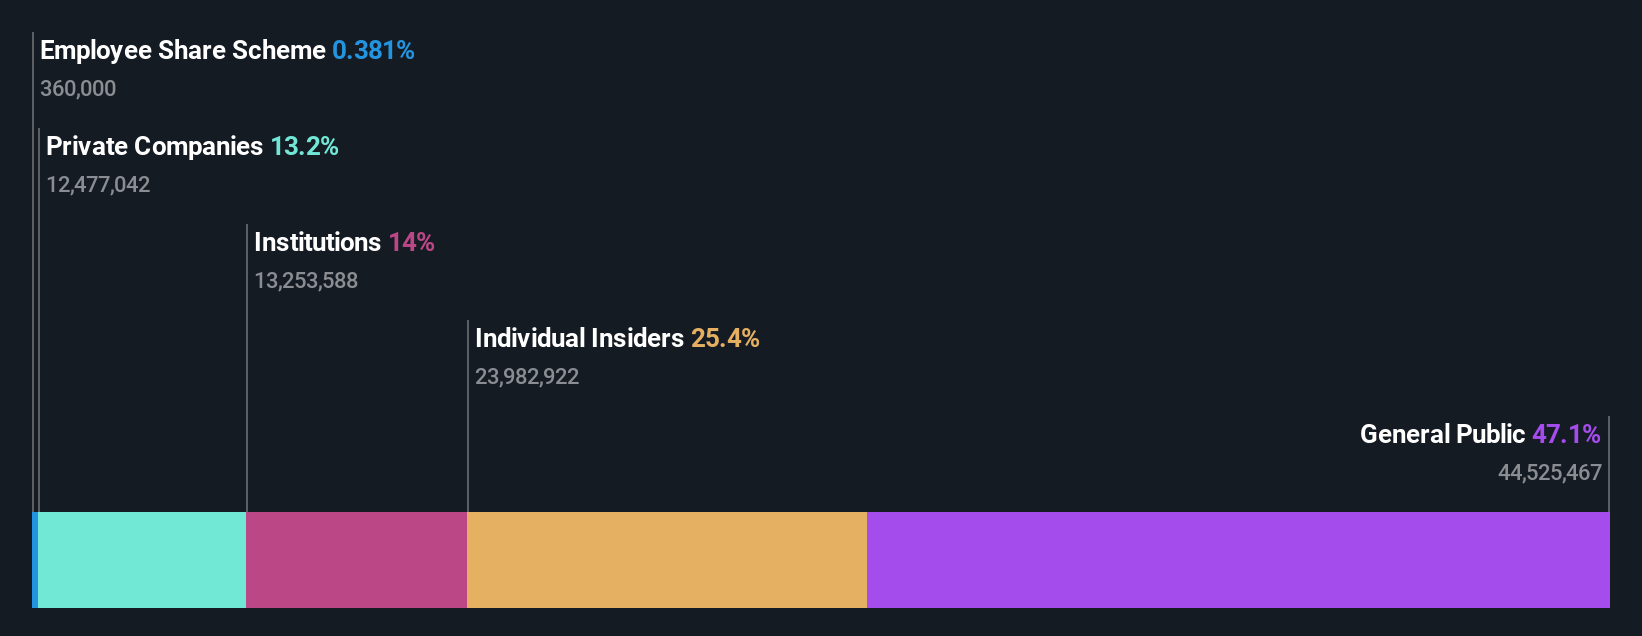
Insider Ownership: 15.6%
Earnings Growth Forecast: 32.2% p.a.
Kinik's earnings are forecast to grow significantly at 32.21% annually, surpassing the TW market's 25.1% average. Recent results show strong performance with Q2 sales reaching TWD 2.49 billion, up from TWD 2.11 billion year-on-year, and net income rising to TWD 523.38 million from TWD 266.37 million previously. Despite high share price volatility, Kinik's robust earnings growth and insider ownership position it well among growth companies in its sector.
- Delve into the full analysis future growth report here for a deeper understanding of Kinik.
- In light of our recent valuation report, it seems possible that Kinik is trading beyond its estimated value.
ASE Technology Holding (TWSE:3711)
Simply Wall St Growth Rating: ★★★★★☆
Overview: ASE Technology Holding Co., Ltd., along with its subsidiaries, offers semiconductor manufacturing services across the United States, Taiwan, Asia, Europe, and other international markets, with a market cap of NT$2.86 trillion.
Operations: The company's revenue segments consist of NT$84.64 billion from Testing, NT$360.08 billion from Packaging, and NT$293.40 billion from Electronic Manufacturing Services (EMS).
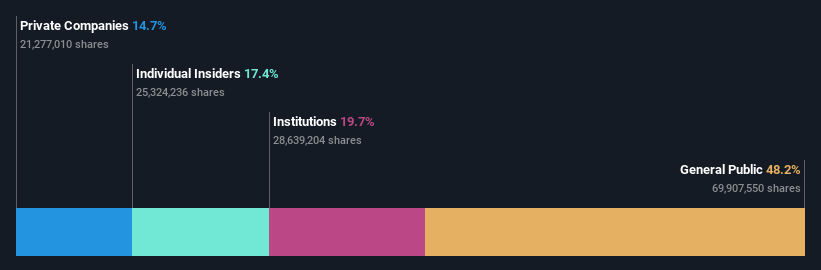
Insider Ownership: 25.8%
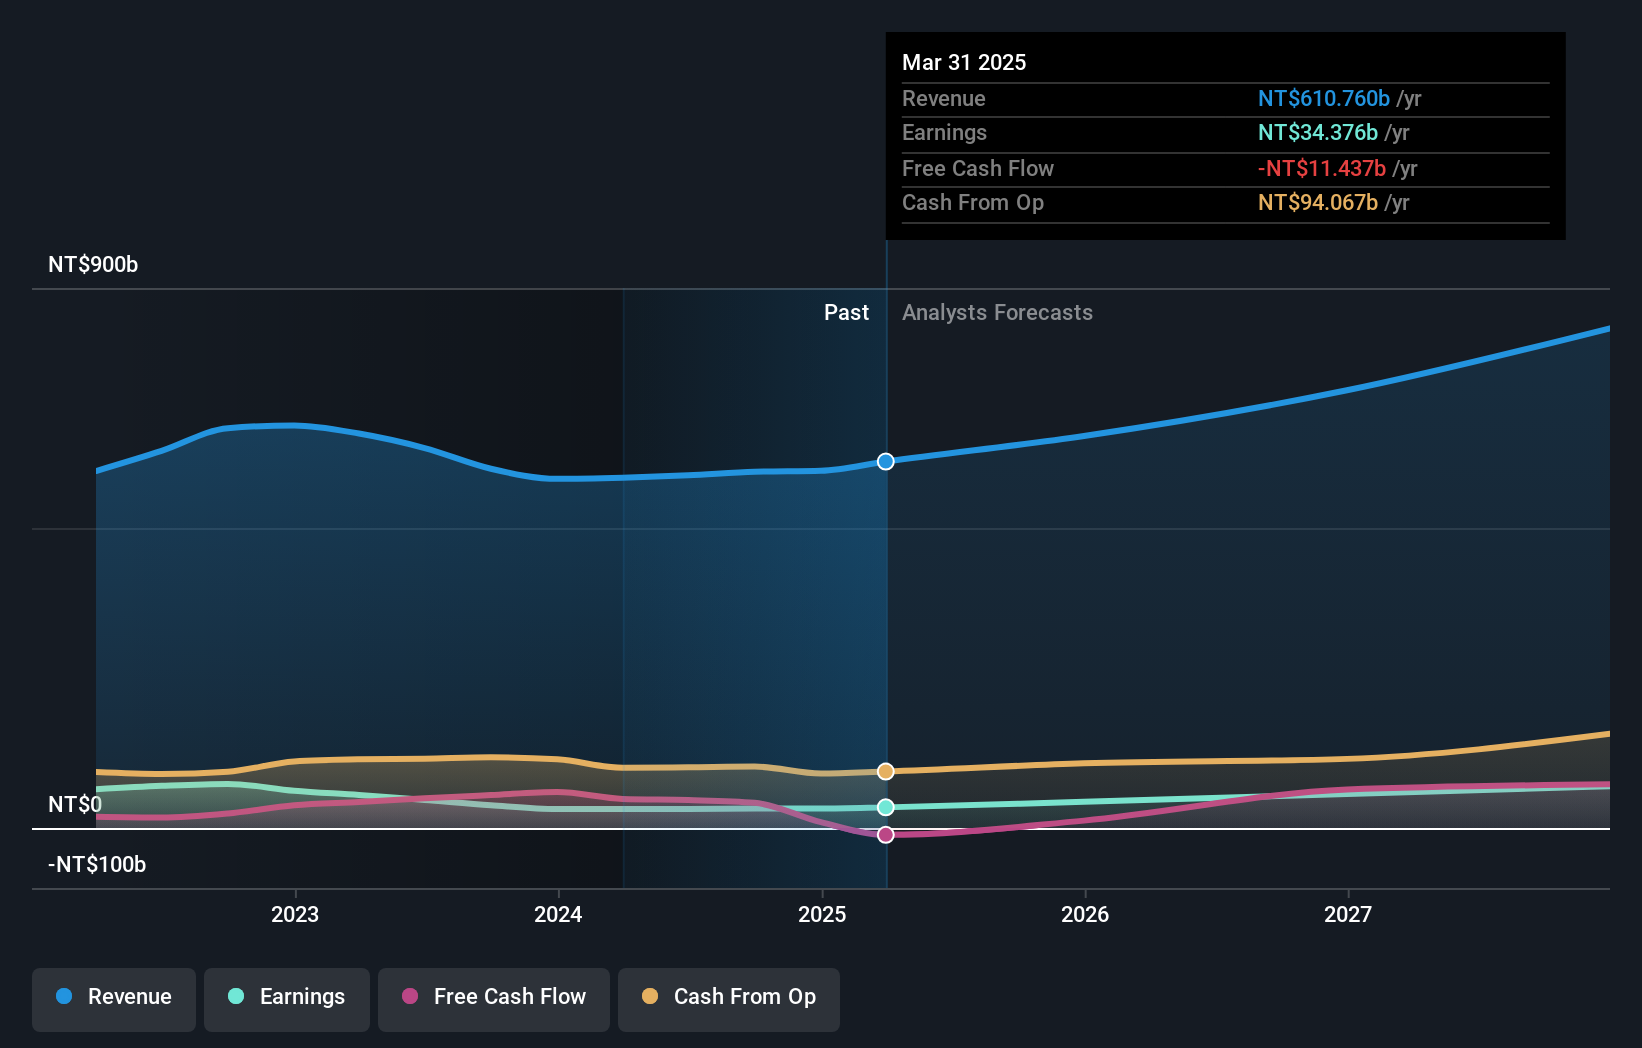
Earnings Growth Forecast: 38% p.a.
ASE Technology Holding's earnings are projected to grow significantly at 38% annually, outpacing the TW market's average. Recent revenue reports show strong growth with Q3 revenues reaching TWD 244.16 billion, up from TWD 168.57 billion year-on-year. Despite high share price volatility and a substantial debt level, insider ownership remains stable with more shares bought than sold recently, positioning ASE Technology favorably among growth-focused companies in its sector.
- Dive into the specifics of ASE Technology Holding here with our thorough growth forecast report.
- Our valuation report unveils the possibility ASE Technology Holding's shares may be trading at a premium.
Where To Now?
- Unlock more gems! Our Fast Growing Global Companies With High Insider Ownership screener has unearthed 726 more companies for you to explore.Click here to unveil our expertly curated list of 729 Fast Growing Global Companies With High Insider Ownership.
- Interested In Other Possibilities? The latest GPUs need a type of rare earth metal called Terbium and there are only 34 companies in the world exploring or producing it. Find the list for free.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.The analysis only considers stock directly held by insiders. It does not include indirectly owned stock through other vehicles such as corporate and/or trust entities. All forecast revenue and earnings growth rates quoted are in terms of annualised (per annum) growth rates over 1-3 years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com