


American Assets Trust (AAT) Could Be 11% Undervalued After Third Quarter Earnings
American Assets Trust (AAT) just released third quarter 2026 earnings, reporting sales of US$107.84 million and revenue of US$114.28 million, alongside net income of US$7.73 million and earnings per share of US$0.13.
At a share price of US$21.22, American Assets Trust has seen its 90 day share price return fall 10.54%, even though the year to date share price return is up 12.99% and the 3 year total shareholder return has reached 43.81%. This suggests that longer term holders have seen stronger momentum than recent traders.
See how American Assets Trust compares with other real estate companies by reviewing a hand picked set of list of solid balance sheet and fundamentals (24 results)
The recent pullback in American Assets Trust after a strong multi year run presents a straightforward decision point. Do you lean into this reset now, or wait for a deeper markdown before committing fresh capital?
Most Popular Narrative: 10% Undervalued
On Simply Wall St’s most followed narrative, American Assets Trust screens as undervalued, with a fair value estimate of $23.50 against the latest close at $21.22. This puts the current pullback in a different light for anyone weighing fresh exposure.
Embedded earnings growth from leasing up La Jolla Commons Tower 3, One Beach Street and suburban Bellevue, with management quantifying about $0.29 per share of potential incremental FFO and about half tied to already signed leases that are scheduled to commence through 2027, could support higher future earnings and dividend coverage as this rent flows through the income statement.
See why 2 investors see American Assets Trust as 10% undervalued.
Result: Fair Value of $23.50 (UNDERVALUED)
Still, the American Assets Trust story comes with pressure points, including elevated net debt to EBITDA around 6.7x to 6.9x and a payout ratio near the upper 90% range, which leaves limited room if leasing or NOI timing disappoints.
Find out about the key risks to this American Assets Trust narrative.
Another View: What Multiples Say About American Assets Trust
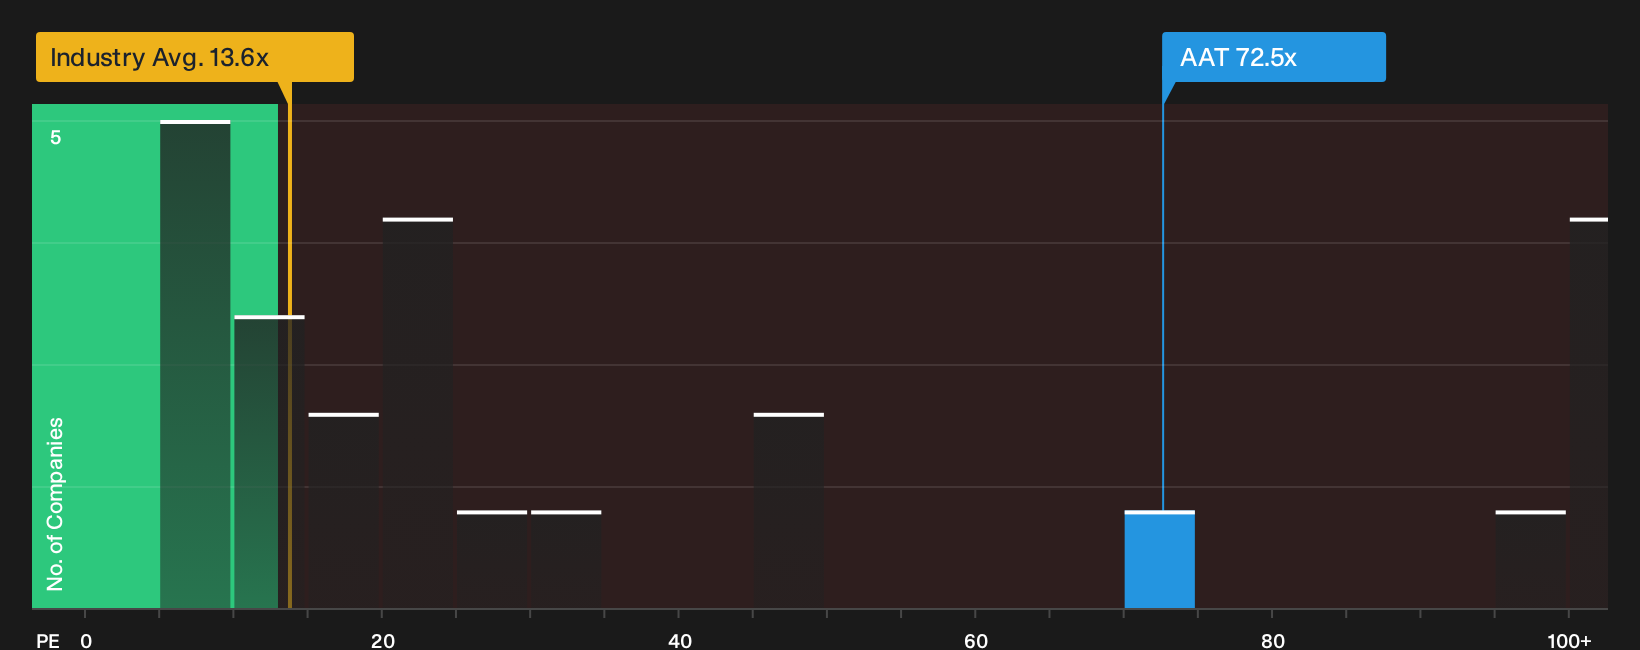
Pull away from fair value estimates and the picture shifts. American Assets Trust currently trades on a P/E of 72.5x, which is richer than the Global REITs average of 13.7x and above its own fair ratio of 40.6x. That gap points to valuation risk if sentiment cools or earnings lag what is implied here.
For a closer look at how today's valuation stacks up against peers and where the fair ratio suggests pricing could drift over time, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of optimism and concern around American Assets Trust feels familiar, consider taking action while the details are fresh and test the data against your own expectations using the 2 key rewards and 3 important warning signs.
Looking For More Investment Ideas Beyond American Assets Trust?
If American Assets Trust has sharpened your thinking, do not stop here. Broaden your watchlist now so you are not reacting after the best ideas move.
- Spot potential mispricings early by scanning 29 high quality undervalued stocks that pair solid fundamentals with prices that lag underlying business strength.
- Build a steadier portfolio by reviewing 30 resilient stocks with low risk scores that aim for resilient balance sheets and fewer unpleasant surprises.
- Get ahead of the crowd by checking 21 high quality undiscovered gems that have strong numbers but limited current attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com