


Is NEXTDC (ASX:NXT) A Bargain As Guidance Is Cut And Leadership Changes Unfold?
NEXTDC (ASX:NXT) has been thrown into the spotlight after cutting its FY2027 earnings guidance and confirming chairman Douglas Flynn’s planned retirement, alongside the CEO agreeing to forgo 2027 bonuses following shareholder backlash.
NEXTDC’s recent guidance cut and M3 delays have coincided with heavy selling, with the 30 day share price return down 48.71% and the year to date share price return down 54.15%, while the 1 year total shareholder return has fallen 63.94% from a last close of A$5.75.
Contrast NEXTDC’s sharp selloff with other infrastructure heavyweights by scanning a curated group of 55 AI infrastructure stocks that could benefit from long-term demand for data capacity and AI-ready facilities.
Investors know NEXTDC runs critical data centre infrastructure. The question now is whether a stock that has dropped this far fairly reflects those fundamentals or still embeds too much optimism.
Most Popular Narrative: 67% Undervalued
On the most followed view of NEXTDC, a fair value of A$17.28 sits well above the last close of A$5.75, which frames the recent selloff as a valuation gap rather than a settled verdict.
The analysts have a consensus price target of A$17.27 for NEXTDC based on their expectations of its future earnings growth, profit margins and other risk factors.
However, there is a degree of disagreement amongst analysts, with the most bullish reporting a price target of A$34.45, and the most bearish reporting a price target of just A$9.0.
See why 22 investors see NEXTDC as 67% undervalued.
The narrative uses an 11.41% discount rate, which is relatively demanding for an infrastructure heavy operator, and still lands on a fair value that is roughly three times the current share price. That reflects expectations for strong top line expansion, with revenue growth assumptions near 49.5% a year over the next few years even as forecast earnings trends look weaker.
At the same time, the story is not a simple growth at any price pitch. Forecast net profit margins in the narrative ease back toward 4.2%, which is the Australian IT industry average used in the model, from 16.5% today. The implied future P/E of 315.8x on A$70.4 million of 2029 earnings is also materially above the current sector P/E of 36.2x, so investors relying on this view would be assuming the market is willing to value NEXTDC on a much richer multiple than the broader IT group.
Those high multiples sit alongside clear execution and funding risks flagged in the same storyline, from large capex programs and project timing to concentrated hyperscale customers and exposure to changing credit markets. For anyone weighing the recent share price fall, the key question is whether that combination of elevated growth assumptions, thinner margins and a higher discount rate is realistic, or whether it asks too much of NEXTDC’s future cash generation to close the gap between price and narrative fair value.
Result: Fair Value of A$17.28 (UNDERVALUED)
Still, the narrative wobbles if power delays like M3 drag out revenue activation, or if large cloud and AI customers slow deployments or renegotiate terms.
Find out about the key risks to this NEXTDC narrative.
Another View: NEXTDC On Simple Market Ratios
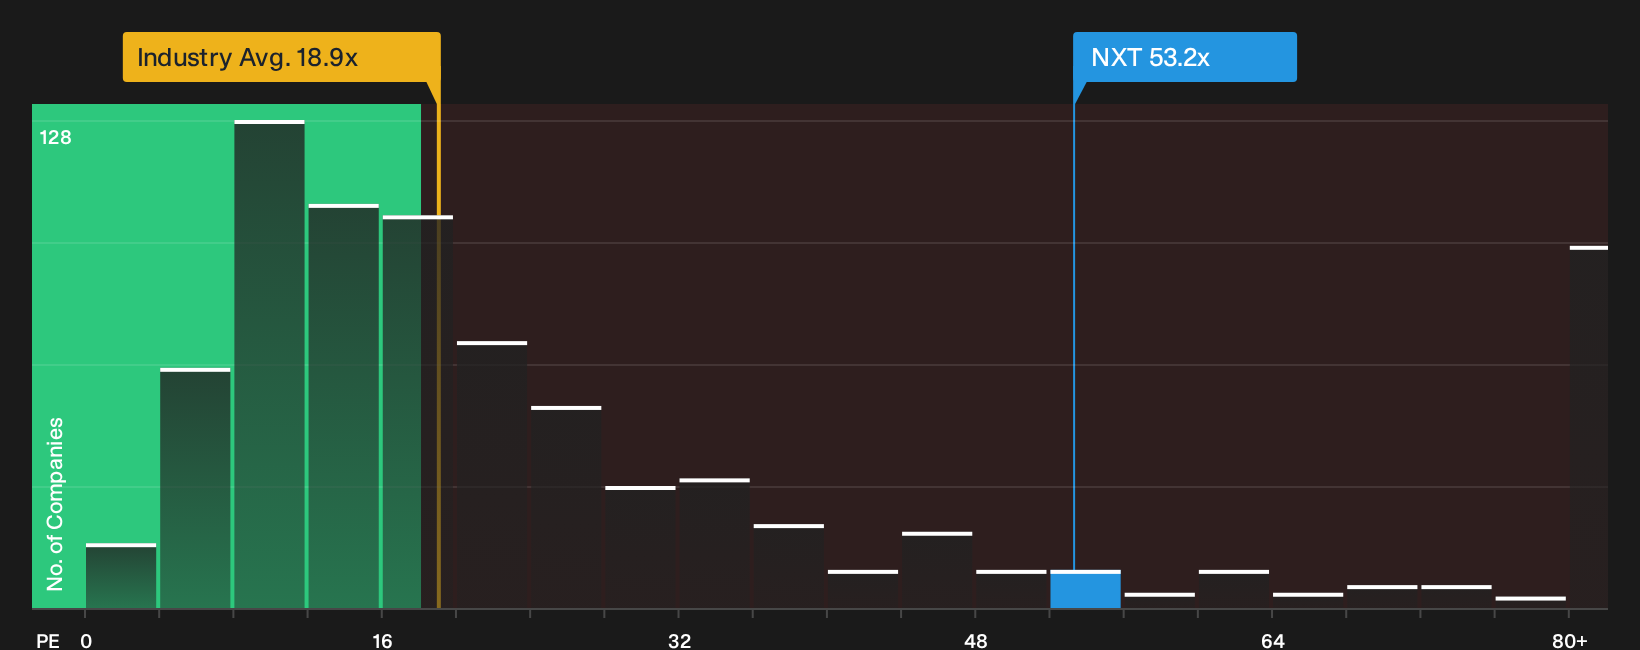
The fair value narrative presents NEXTDC as significantly undervalued. A straightforward P/E check suggests a different perspective. The stock trades on 53.2x earnings, compared with a fair ratio of 20.9x, the Australian IT peer average of 43.9x and a global IT reading of 18.9x. That kind of premium can matter for investors who focus on how much positive news may already be reflected in the price, especially with earnings forecast to decline over the next 3 years and revenue still heavily reliant on external borrowing for funding. The key question is whether this situation represents a potential reset opportunity or a rich multiple that may be vulnerable to compression.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on NEXTDC is clearly split, so if you want to move fast and build your own view from the ground up, start by weighing its 2 key rewards and 4 important warning signs
Looking for more NEXTDC sized investment ideas?
If NEXTDC has sharpened your focus, do not stop here. Broaden your watchlist now so you are not chasing opportunities after they are crowded.
- Target potential mispricings early by scanning a curated set of 15 high quality undiscovered gems before the broader market starts paying attention.
- Strengthen your downside protection by filtering for a list of solid balance sheet and fundamentals (12 results) that can better handle funding cycles and tougher credit conditions.
- Dial back portfolio stress by zeroing in on 6 resilient stocks with low risk scores that align with a more measured, capital preservation focused approach.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com