


Itron (ITRI) Stock Price Recasts Q3 Earnings On Margin Strength
Itron walked into its Q3 2026 report with a value label and a cautious growth reputation. The latest print forced investors to reassess that script fast. After the release, the stock jumped 7.8% to US$94.55, a sharp move for a utility technology supplier that usually trades on patience, not adrenaline.
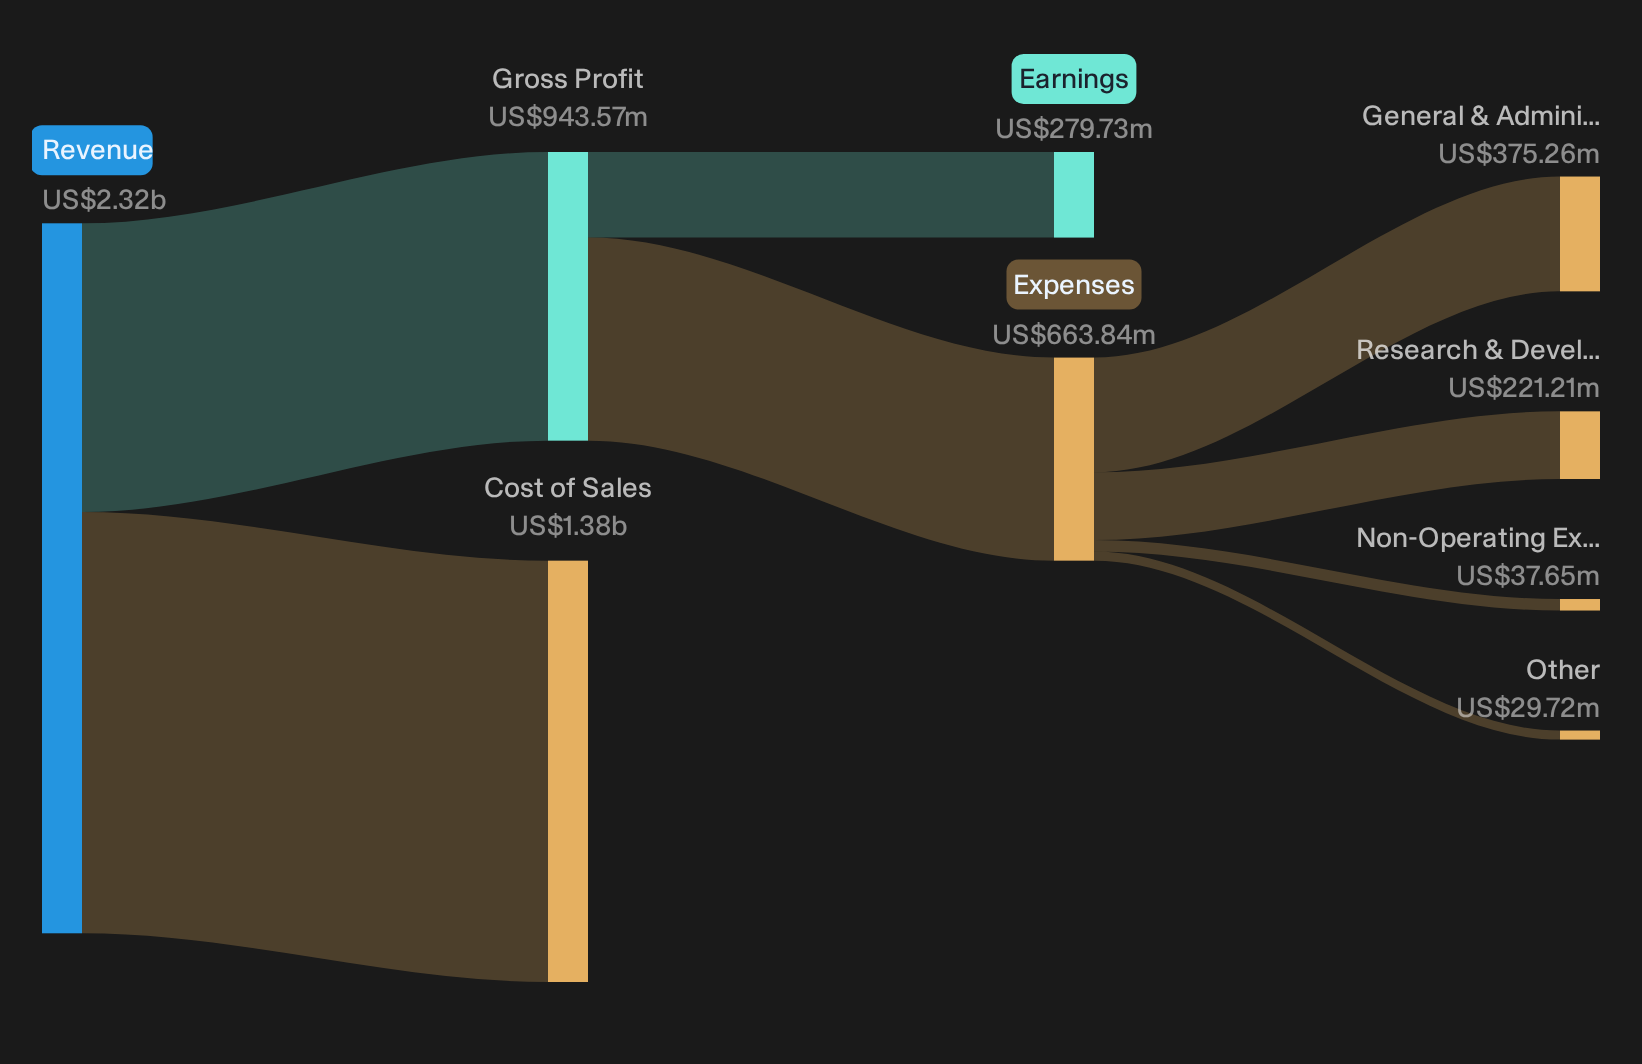
The catalyst was earnings power, not story telling. Quarterly revenue reached US$599.3 million while basic earnings per share hit US$1.63, both backed by record adjusted profitability. For a business built around long contracts and grid infrastructure, that kind of margin punch feels very real, which helps explain the abrupt reset in the share price.
Like that blend of record profitability and a still-cautious growth profile but want a wider set of grid and infrastructure players with strong balance sheets to compare it to? Check out the list of solid balance sheet and fundamentals stocks (24 results)
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs. Q3 2025): US$599.3 million vs. US$581.6 million (+3.0%)
- Net Income (Excl. Extra Items, Q3 2026 vs. Q3 2025): US$71.4 million vs. US$65.6 million (+8.8%)
- Basic EPS (Q3 2026 vs. Q3 2025): US$1.63 vs. US$1.43 (+13.6%)
- Adjusted EBITDA Margin (Q3 2026 vs. Q3 2025): 19.2% vs. 15.8% (+340 bps), based on adjusted EBITDA of US$115 million on Q3 2026 revenue and US$91.9 million on Q3 2025 revenue
Itron hit record margins while revenue growth stayed modest. Ask Charlie what makes Itron’s margin gains truly structural.
Itron backlog thesis clears an important hurdle
Bulls argue that Itron’s multi year project queue can actually turn into business on roughly planned schedules.
"The main thing that has to go right is that utilities continue to turn record pipelines and growing multi-year backlogs for grid modernization, gas refresh and digital water projects into deployments on roughly the schedules Itron and its customers are planning for."
Q3 showed real progress against that claim. Revenue landed at the top of the outlook, bookings reached US$482m and backlog held at about US$4.3b. Management tightened full year revenue guidance and lifted non GAAP EPS, which points to better conversion rather than slippage in current programs.
Deployment timing risk for Itron is not gone
The bear narrative focuses on whether delays in large programs will keep earnings tied to project timing.
"Customers and regulators are slowing project deployments and delaying decisions due to increased capital budget pressures, affordability concerns and regulatory scrutiny, and this is visible in Itron reporting that certain large Networked Solutions programs have been spread over longer time frames and that full year 2025 revenue fell 3% versus 2024 after the catch up period ended, which could continue to restrain revenue growth and keep earnings sensitive to deployment timing."
Q3 results counter parts of that worry, with solid Networked Solutions revenue, 27% booking growth and raised EPS guidance. Management still described bookings as lumpy and tied to regulatory calendars, so timing risk has eased but not disappeared.
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for.
Hunt For Mispriced Earnings Power
Itron shows how a single quarter can reset expectations for a steady grid supplier. The real opportunity sits with stocks that could be undervalued before stronger fundamentals get fully recognised.
- Company 1 - 34% below our estimate - uses an expanded senior bench and broader advisory toolkit to win higher fee, complex mandates from large corporate and private capital clients.
- Company 2 - 42% below our estimate - builds payment rails large online platforms use to ramp transaction volumes while automating settlement across more local methods and payout channels.
- Company 3 - 22% below our estimate - wires AI tools directly into workplace software, turning experimental pilots into paid subscriptions layered on top of existing cloud and productivity contracts.
That is three of the list. See every one of the 29 undervalued companies on it →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com