


Principal Financial Group (PFG) Stock Gains Ground As Q3 Earnings Strength Meets Flow Pressure
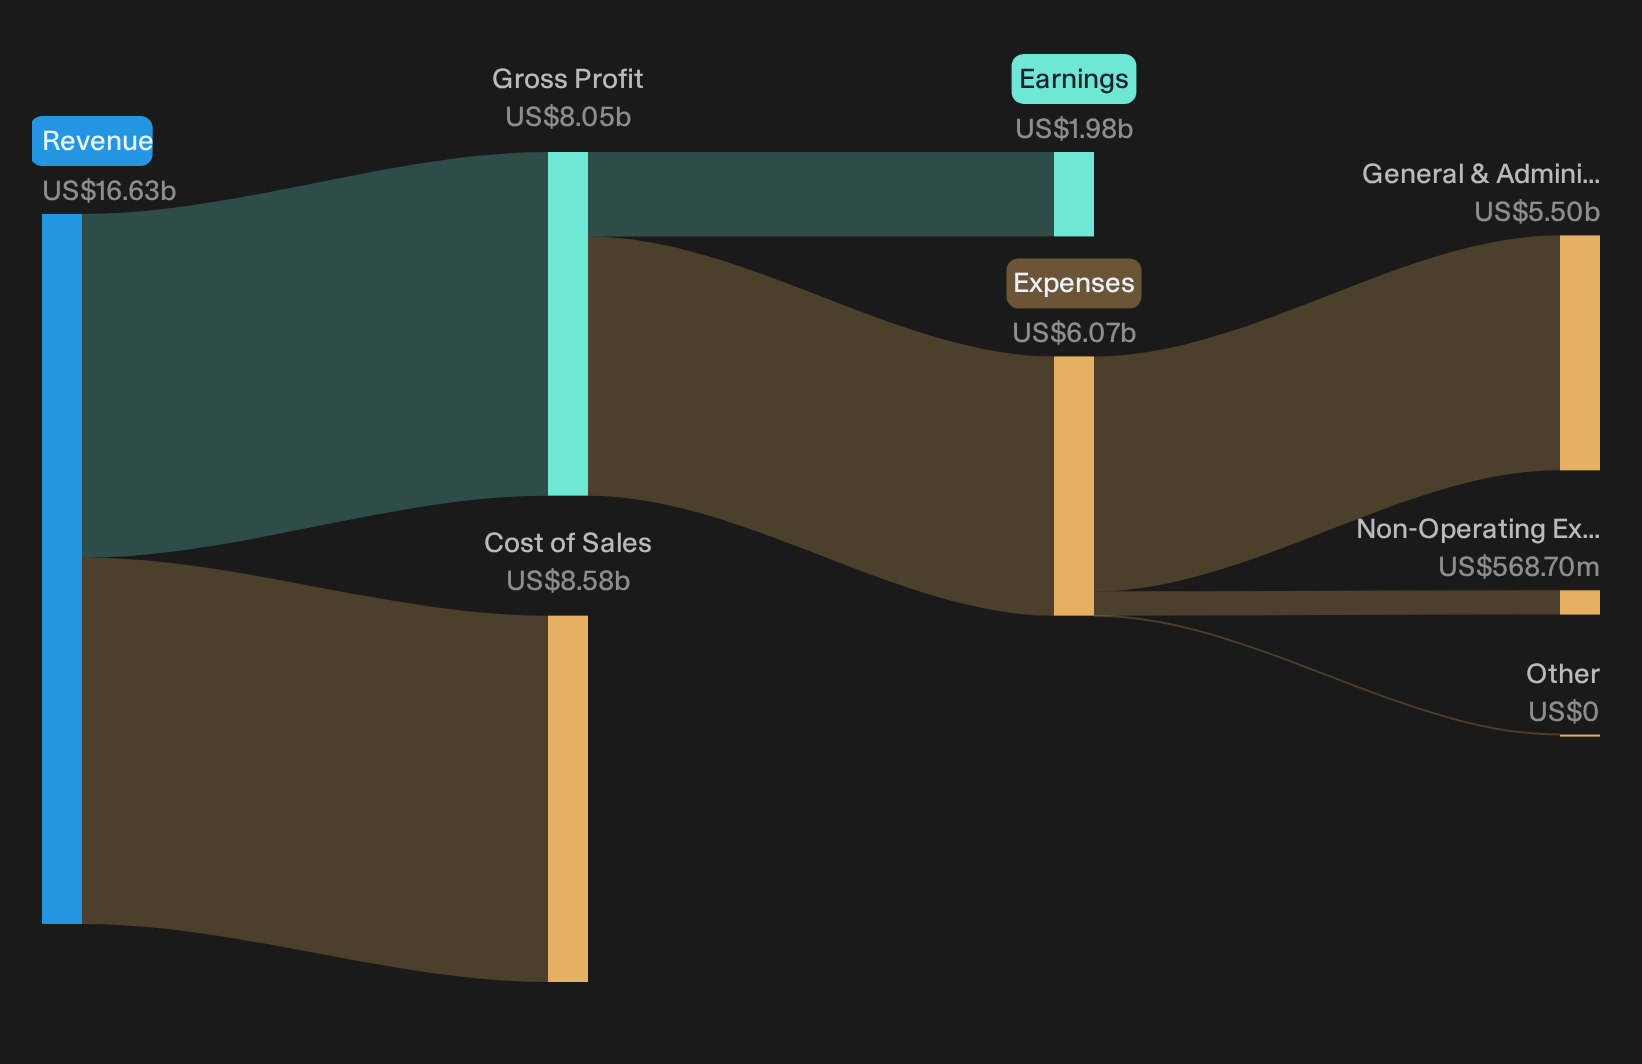
Principal Financial Group stock edged up 1.7% to about US$112 after the Q3 2026 release, a calm move for a life and retirement heavyweight that reported one of its strongest profit quarters in recent years. Basic earnings per share landed near US$2.95 on net income of about US$632m, placing profitability at the center of the story. Short-term traders saw a modest gain. Long-horizon investors are more likely watching how that earnings power compares with a trailing P/E of 12.1x and a discounted cash flow value that currently sits far above the market price.
Love the strong Q3 earnings power at Principal Financial Group but want a wider set of solid operators trading on similar or lower multiples? Compare it with our list of solid balance sheet and fundamentals stocks (24 results)
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs. Q3 2025): US$4,616.4m vs. US$3,681.6m (up about 25%)
- Net income, excluding extraordinary items (Q3 2026 vs. Q3 2025): US$631.9m vs. US$213.8m (up about 196%)
- Basic EPS (Q3 2026 vs. Q3 2025): US$2.95 vs. US$0.96 (up about 207%)
- Trailing 12-month net income, excluding extraordinary items (Q3 2026 vs. Q3 2025): US$1,976.9m vs. US$1,573.5m (up about 26%)
Evaluating Principal Financial Group’s Margin-Building Ambitions
The bullish pitch centers on Principal Financial Group turning ecosystem breadth into compounding earnings power.
"Bullish analysts expect Principal Financial Group to keep building on its integrated retirement and benefits ecosystem, with retirement transfer and recurring deposits, Specialty Benefits earnings, and international pension assets all supporting the view that the business can compound earnings power over time."
Q3 results show real progress toward that goal. Retirement and Income Solutions produced about 42% operating margin with recurring deposits near US$13b and roll ins at US$7.4b over 12 months. Specialty Benefits premiums and fees grew, with sales up 10% in Q3 and 15% on a trailing year. International pension assets reached roughly US$166b with positive net flows and strong margins, reinforcing that higher margin segments are carrying more weight in group earnings.
One Narrative has put a figure on that disagreement. → See the Narrative with its lower Fair Value, assumptions and all.
Principal Financial Group: Flows Still Undercut EPS Story
The bearish view on Principal Financial Group hinges on earnings quality rather than headline strength. The key worry is that fee pressure and soft flows could quietly cap progress.
"Although Principal Financial Group highlights strong recent EPS and margin expansion, the roughly $11b of net outflows concentrated in U.S. active equity strategies that account for just over 5% of assets suggest that if style headwinds persist, fee revenue from this part of asset management could decline further and weigh on total revenue growth."
Q3 confirms that concern. Management reported US$11b of negative net cash flow in asset management, driven by active equity outflows and a lower fee rate, even as private markets, ETFs and international pensions posted positive flows.
Hunt For Mispriced Earnings Power
Principal Financial Group just reported a quarter that reframed recent earnings without changing the long term narrative. The real opportunity sits with stocks that could be undervalued before the market closes the gap.
- Company 1 - 46% below our estimate - converts a record project backlog tied to data center and modular builds into higher utilization and pricing power.
- Company 2 - 26% below our estimate - sells injectable treatments for weight loss and diabetes already adopted at scale while awaiting new approvals.
- Company 3 - 31% below our estimate - wins complex manufacturing programs in regulated end markets as clients sign long term outsourcing contracts.
Three companies from the same screener. Open every one of the 29 undervalued companies on it →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com