


ASSA ABLOY (OM:ASSA B) Stock Price Faces Q3 Earnings Reality Check
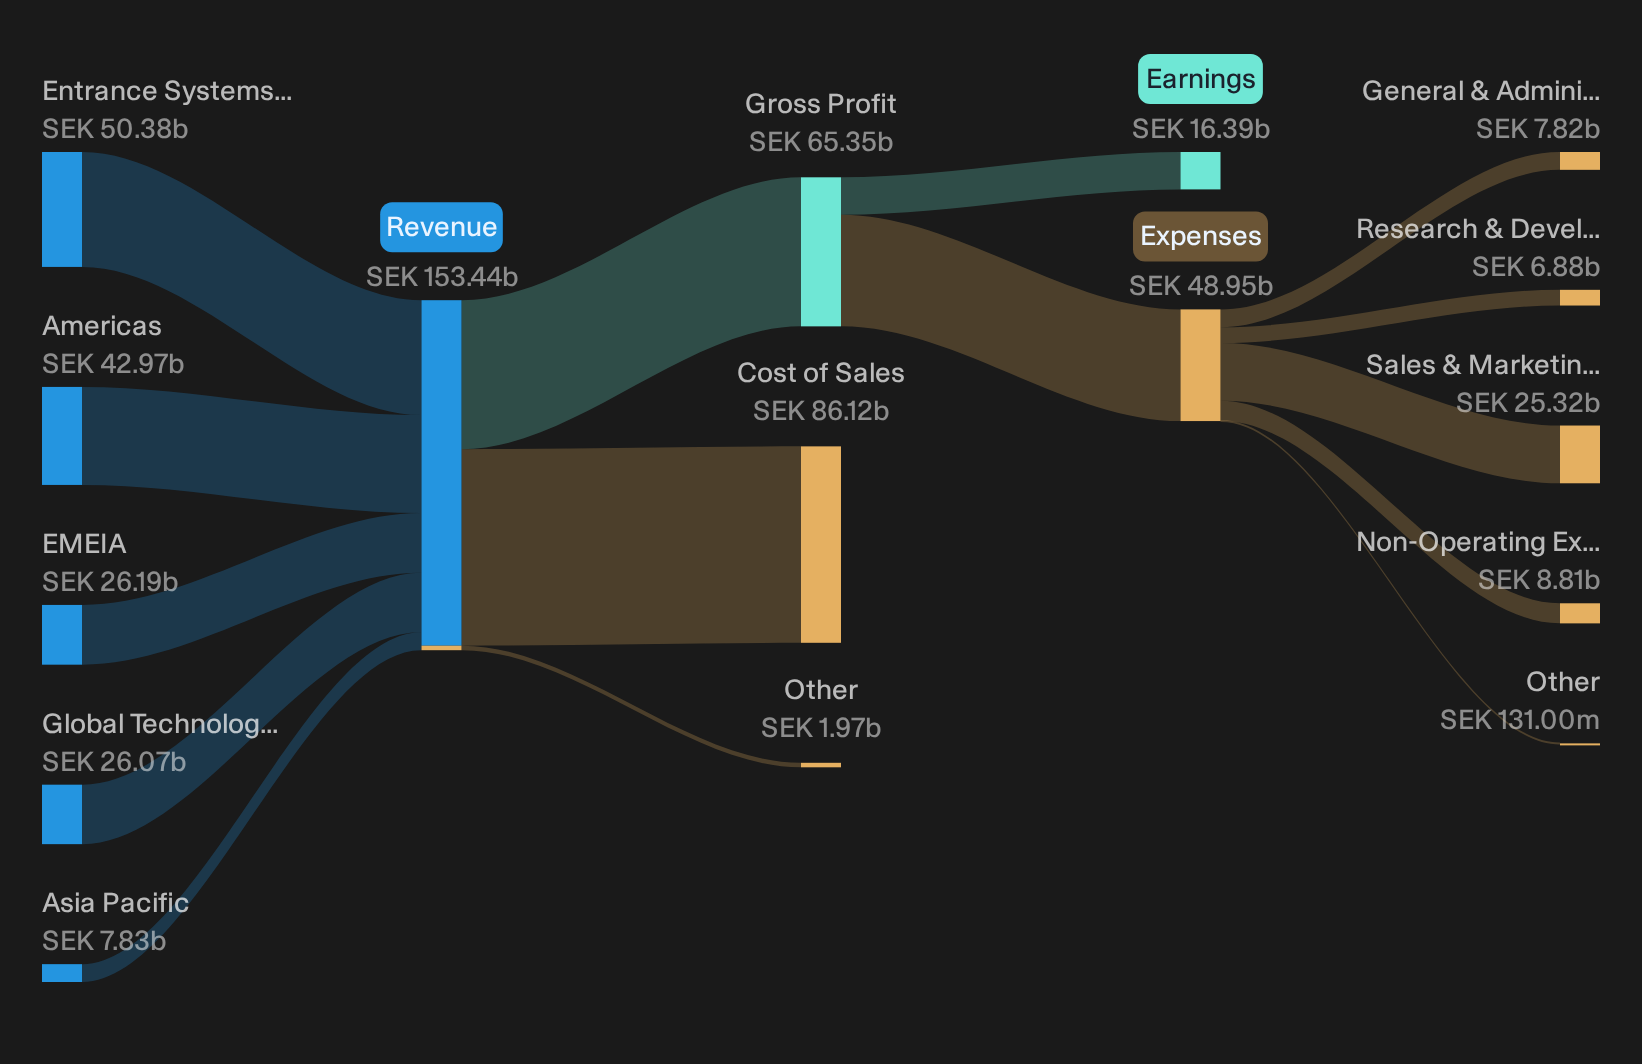
ASSA ABLOY just posted Q3 2026 numbers that set fresh records on almost every line, yet the stock closed today at SEK381.3, only modestly above where it traded in recent weeks. Revenue crossed SEK40b for the first time and EBIT margin reached 17.4%, a high watermark for this security hardware giant.
That combination of record profitability and a relatively muted share price response indicates that sentiment is cautious. The market appears more focused on valuation and debt concerns than on the earnings power now visible in the income statement.
Love ASSA ABLOY's record revenue and 17.4% EBIT margin but concerned that the muted share price hints at valuation and balance sheet worries? Compare it against companies screened for strong earnings power and more conservative leverage in our list of solid balance sheet and fundamentals stocks (207 results).
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs Q3 2025): SEK 40,771m vs. SEK 38,146m (up 6.9%)
- Net Income, excl. extra items (Q3 2026 vs Q3 2025): SEK 4,715m vs. SEK 4,149m (up 13.6%)
- Basic EPS (Q3 2026 vs Q3 2025): SEK 4.24 vs. SEK 3.74 (up 13.6%)
- EBIT Margin (Q3 2026 vs Q3 2025): 17.4%, compared with a prior-year level below this new record (margin at a fresh high)
ASSA ABLOY just hit record sales, margins and cash flow. Ask Charlie what ASSA ABLOY’s new MFP #11 could change.
Evaluating ASSA ABLOY’s Cash And Margin Upside Story
Optimistic views on ASSA ABLOY lean heavily on how mix, cash and M&A work together, not just on higher margins.
"Bullish analysts expect ASSA ABLOY to continue shifting its mix toward higher margin electromechanical, digital and recurring revenue solutions, while maintaining strong cash generation and disciplined acquisitions."
Q3 gives this claim some concrete checkpoints. Electromechanical products grew 9% organically, group EBIT margin reached 17.4% and cash conversion ran at 117% for the quarter and 109% over 12 months. Net debt to EBITDA is about 2.0x while management closed three bolt ons and lined up Gunnebo Entrance Control, which shows capacity to keep doing deals without stretching the balance sheet.
Not everyone reads the same price the same way. → See the higher figure this Narrative lands on, and how it gets there.
ASSA ABLOY: Testing Fears On China And Deals
Bearish views argue that ASSA ABLOY’s record quarter masks pressure points that could cap earnings progress if they persist.
"Although acquisition capacity is supported by net debt to EBITDA of around 2.1 to 2.2x and cash conversion above 100%, the margin dilution and underperformance from the Level Lock acquisition suggest that further deal making could drag on EBIT and earnings quality if integration issues recur."
Q3 results partly validate that worry. Group EBIT margin reached 17.4%, yet management again called out Entrance Systems M&A as margin dilutive and Greater China remained in double digit decline. Eleven deals year to date plus the Gunnebo signing show execution risk is still accumulating, not receding.
Hunt For Mispriced Earnings Power
ASSA ABLOY’s recent quarter and muted share reaction highlight how accounting strength may not quickly influence a stock. The real opportunity sits in finding companies that could be undervalued before expectations reset.
- Company 1 - 40% below our estimate - turns expanding AI tools and sovereign cloud capacity into higher value software subscriptions for small business clients.
- Company 2 - 28% below our estimate - grows a compact grocery format and online ordering that capture more spending in dense urban neighborhoods.
- Company 3 - 27% below our estimate - builds higher margin prosthetics and neuro orthotics usage as clinics refer more complex cases into its care network.
Those are three of them. See all 195 potentially undervalued companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com