


AST SpaceMobile Stock Gets Brazil Spectrum Approval
- AST SpaceMobile secured authorization from Brazil’s Anatel for 30 MHz of S-band spectrum and secondary access to up to 20 MHz in the 700 MHz band, signing deals with four regional mobile operators and planning four local gateways to support direct satellite connectivity to standard smartphones.
- This Brazilian build out provides AST SpaceMobile with a large addressable base of more than 200 million handset lines and a concrete test bed for scaling its direct to device model in a major emerging market.
- Attention now turns to how AST SpaceMobile’s new Brazilian spectrum footprint and gateways could influence the longer term investment narrative.
AST SpaceMobile Investment Narrative Recap
To own AST SpaceMobile, you have to believe a space based cellular network can move from proofs of concept to reliable, scaled service with mobile operators actually routing traffic over it. The Brazil spectrum win sits right in that execution story. It helps on regulatory and partner validation, but the key near term catalyst still sits in timely satellite launches, gateway buildouts and live service activation.
The biggest risk remains execution on a very capital intensive rollout. Management is committing over $21 million to $23 million per satellite and quarterly capex of $275 million to $325 million while the business is still loss making. If launches, manufacturing, or integration slip, that spending could weigh harder before meaningful usage materializes.
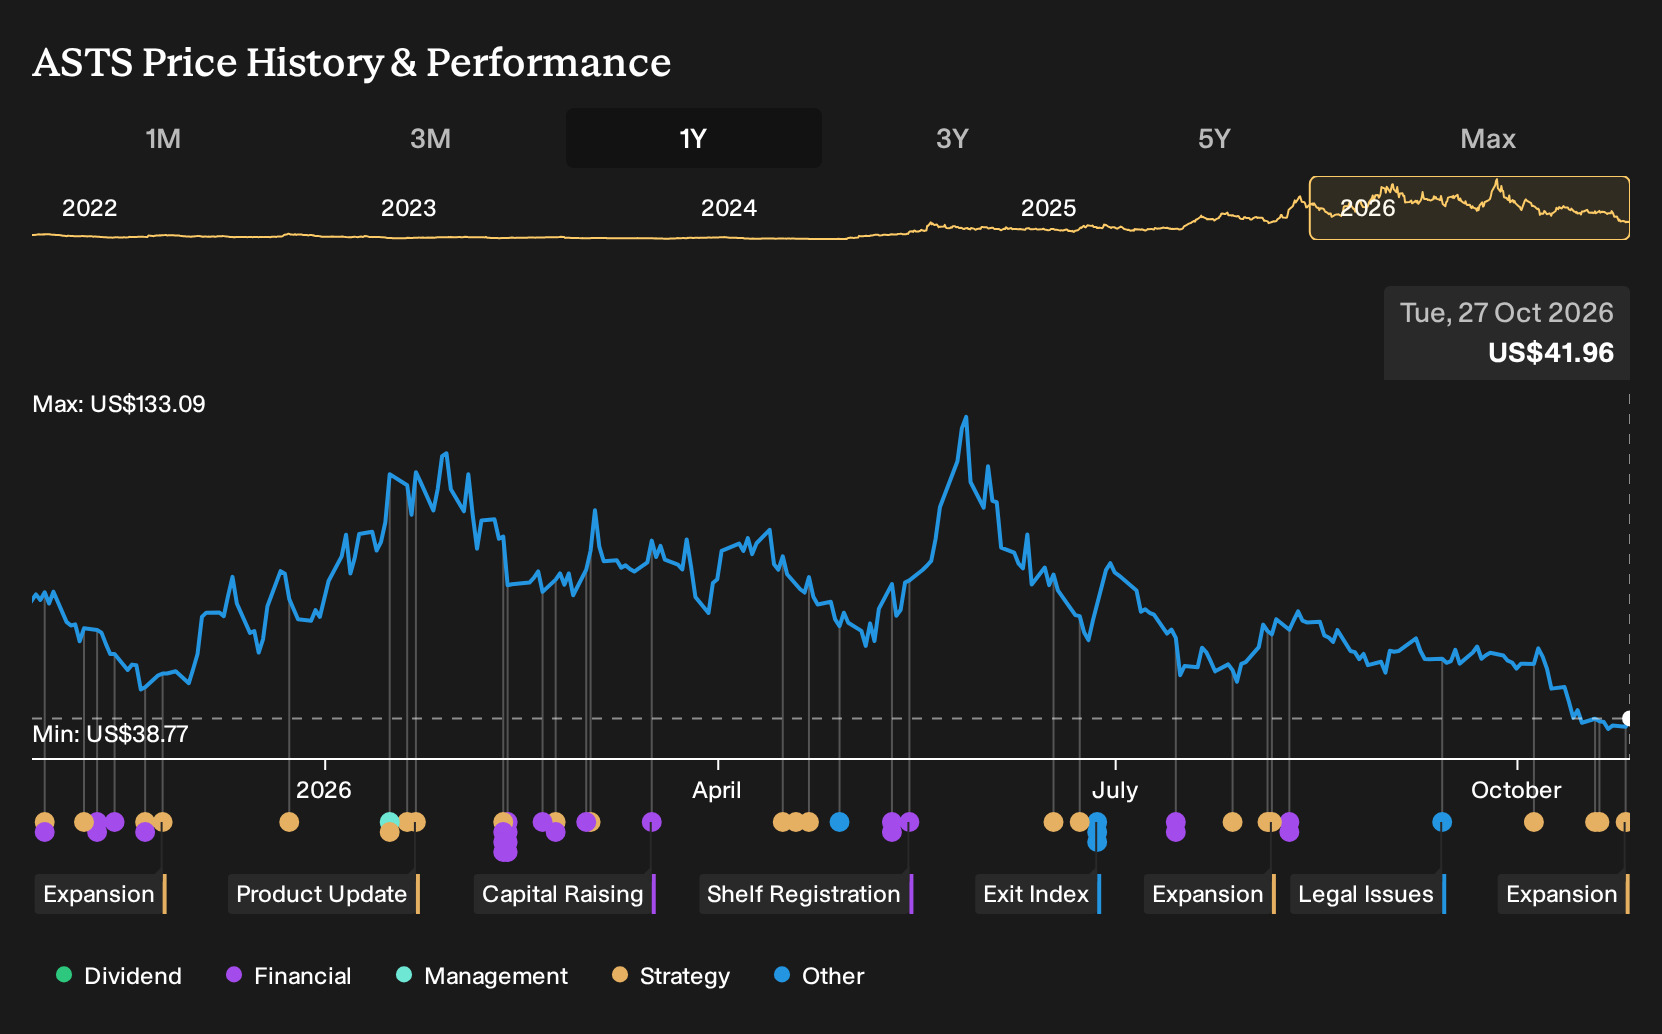
The October update on service readiness in the United States, Canada, Japan, the UK and Saudi Arabia ties directly into what is happening in Brazil. Management now has more than 60 gateways deployed, installed or in planning worldwide, and is already enabling thousands of coverage cells in the US, with a goal of roughly 5,600 digital cells across the contiguous market.
For you as an investor, this creates a clear operational scorecard. Watch whether AST SpaceMobile actually lights up intermittent service in those five priority markets and Brazil by the end of 2026, and whether partner traffic converts into real revenue against heavy capex and significant convertible debt. Any shortfall on utilization or pricing would quickly test the long term thesis.
AST SpaceMobile’s current analyst playbook assumes revenue climbs toward US$2.1b and earnings reach US$195.2m by 2029. This implies yearly revenue growth of 163.4% and an earnings swing of about US$814m from a loss of US$618.8m today to that forecast level.
Uncover why AST SpaceMobile's fair value indicates a 77% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One bullish twist on AST SpaceMobile hinges on government and partner contracts rather than just Brazil. The most optimistic analysts were already penciling in revenue of about US$2.6b and earnings near US$227.8m by 2029 before this spectrum win, so their case leans on aggressive execution and suggests opinions could shift further as Brazil gets priced in.
Explore 10 other AST SpaceMobile fair value estimates, including one that suggests potential upside of up to 347% from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and instincts.
- A great starting point for your AST SpaceMobile research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for AST SpaceMobile. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate AST SpaceMobile's overall financial health at a glance.
Looking For More AST SpaceMobile Investment Ideas?
If AST SpaceMobile has caught your attention but you want a wider field of options, the Simply Wall St Screener can help you line up other opportunities that fit different risk and quality profiles.
- If you care most about long term quality at a reasonable entry point, scan through 29 high quality undervalued stocks that pair fundamentals with pricing that may appeal to disciplined buyers.
- For readers who want sturdier balance sheets and fewer financial surprises, filter the market using our list of solid balance sheet and fundamentals (24 results) to surface companies with stronger financial footing.
- If you like the idea of spotting earlier stage opportunities with room to mature, cast a wider net across 21 high quality undiscovered gems that are not widely followed yet still show solid underlying metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com