


Is Aya Gold & Silver (TSX:AYA) Undervalued After Higher Silver Equivalent Production?
Aya Gold & Silver (TSX:AYA) just released operating results showing consolidated silver equivalent production of 2,034,628 ounces for the September quarter and 5,204,752 ounces year to date, both above the prior year’s reported levels.
The fresh production update landed alongside sharp share price swings. Aya Gold & Silver has a CA$35.0 share price after a 4.7% 1 day share price return. The stock is down 13.2% on a 30 day share price basis and up 80.1% year to date, while the 1 year total shareholder return of 144.1% and 3 year total shareholder return of about 4.7x suggest strong longer term momentum even as shorter term sentiment cools slightly.
Scan beyond Aya Gold & Silver and line up other precious metal producers showing strong output trends with the hand picked 35 elite gold producer stocks that fit this same production driven story.
After a sharp run this year and a recent pullback, Aya Gold & Silver now forces a timing question. Does the current CA$35.0 level already bake in the production story, or is patience on price worth more than jumping in today?
Most Popular Narrative: 31% Undervalued
Aya Gold & Silver's most followed narrative pegs fair value around CA$50.66, well above the recent CA$35.0 close. This puts the production update against a valuation gap that still looks wide on these assumptions.
The transition of Aya Gold & Silver from a single mine producer toward a multi asset operator through the build out of Boumadine, supported by a 2026 study that outlines a 14 year mine life and multi billion dollar project value, could lift future revenue and earnings from a higher production base.
See why 44 investors see Aya Gold & Silver as 31% undervalued.
Result: Fair Value of CA$50.66 (UNDERVALUED)
Still, the Aya Gold & Silver narrative leans on assumptions that could crack, including pressure from Morocco’s roughly 40% tax rate and analyst forecasts for lower earnings on a much higher P/E multiple.
Find out about the key risks to this Aya Gold & Silver narrative.
Another View: What Aya Gold & Silver's P/E Is Telling You
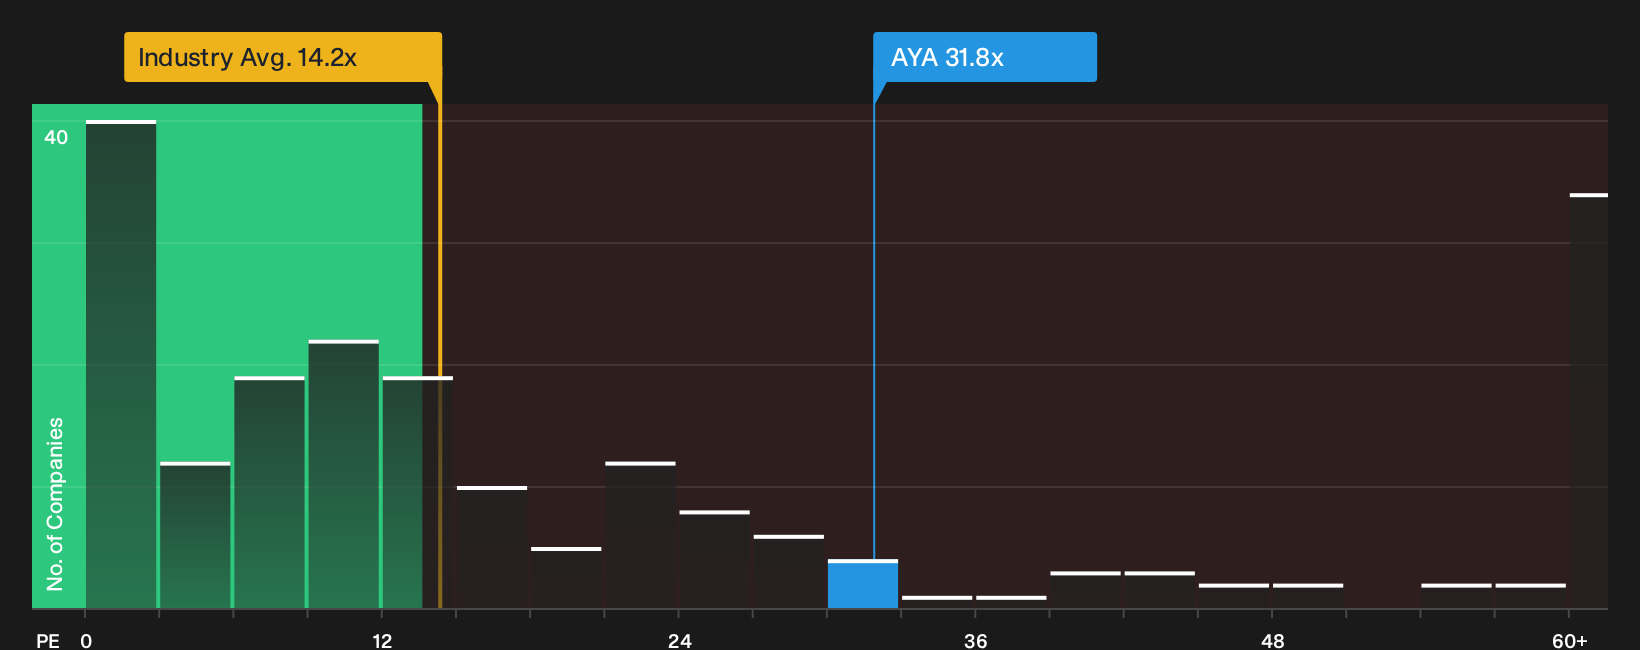
The first narrative frames Aya Gold & Silver as undervalued at CA$35.0 against a CA$50.66 fair value. A different lens tells a tougher story. The current P/E of 31.8x screens as expensive against a 9.4x fair ratio and the 14.2x Canadian Metals and Mining average, while peer stocks cluster nearer 35.9x.
That mix, where Aya Gold & Silver trades above its fair ratio yet a bit below peers, points to valuation risk if sentiment cools and the market moves closer to that 9.4x reference point. The open question is whether future operating updates support this richer multiple or push it back toward the pack.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals can feel confusing when Aya Gold & Silver shows both enthusiasm and hesitation in the data, so move fast, review the full picture for yourself, then weigh the 2 key rewards and 1 important warning sign.
Looking for more ideas beyond Aya Gold & Silver?
If Aya Gold & Silver has your attention, do not stop here. The right tools help you spot what others overlook and act with confidence.
- Target resilient value by scanning a curated set of 3 high quality undervalued stocks that pair quality fundamentals with more modest pricing.
- Prioritize staying power by working through a focused list of solid balance sheet and fundamentals (7 results) that can handle rougher market conditions.
- Hunt for under followed potential by checking the 9 high quality undiscovered gems before everyone else turns their attention there.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com