


Is Earnings Strength Altering The Investment Case For TriCo Bancshares (TCBK)?
- TriCo Bancshares reported third quarter 2026 results that included net interest income of US$96.55 million, net income of US$37.97 million and diluted EPS from continuing operations of US$1.18, alongside a quarterly dividend of US$0.36 per share and net charge offs of US$0.3 million.
- The combination of higher earnings per share year on year, maintained cash dividends and relatively small net charge offs points to a focus on earnings durability and credit discipline. This matters for how investors assess TriCo Bancshares as it manages capital and funds growth.
- We will now explore how TriCo Bancshares' higher quarterly earnings per share might reshape the investment narrative around its merger plans.
Compare TriCo Bancshares' earnings profile and credit discipline with a curated list of solid balance sheet and fundamentals (24 results) that could help you spot banks aiming for a similar mix of stability and income potential.
TriCo Bancshares Investment Narrative Recap
To own TriCo Bancshares, you need to be comfortable with a regional bank that is leaning on consistent earnings, disciplined credit and a merger-driven scale up. The latest quarter, with US$96.55 million in net interest income, US$37.97 million in net income and diluted EPS of US$1.18, supports that operating story in the near term.
The key short term catalyst remains execution around the planned all stock merger and the targeted cost savings that analysts have highlighted. The biggest risk is that integration and IT consolidation fall short of expectations. On the latest figures, the impact on that merger thesis looks more supportive than transformational.
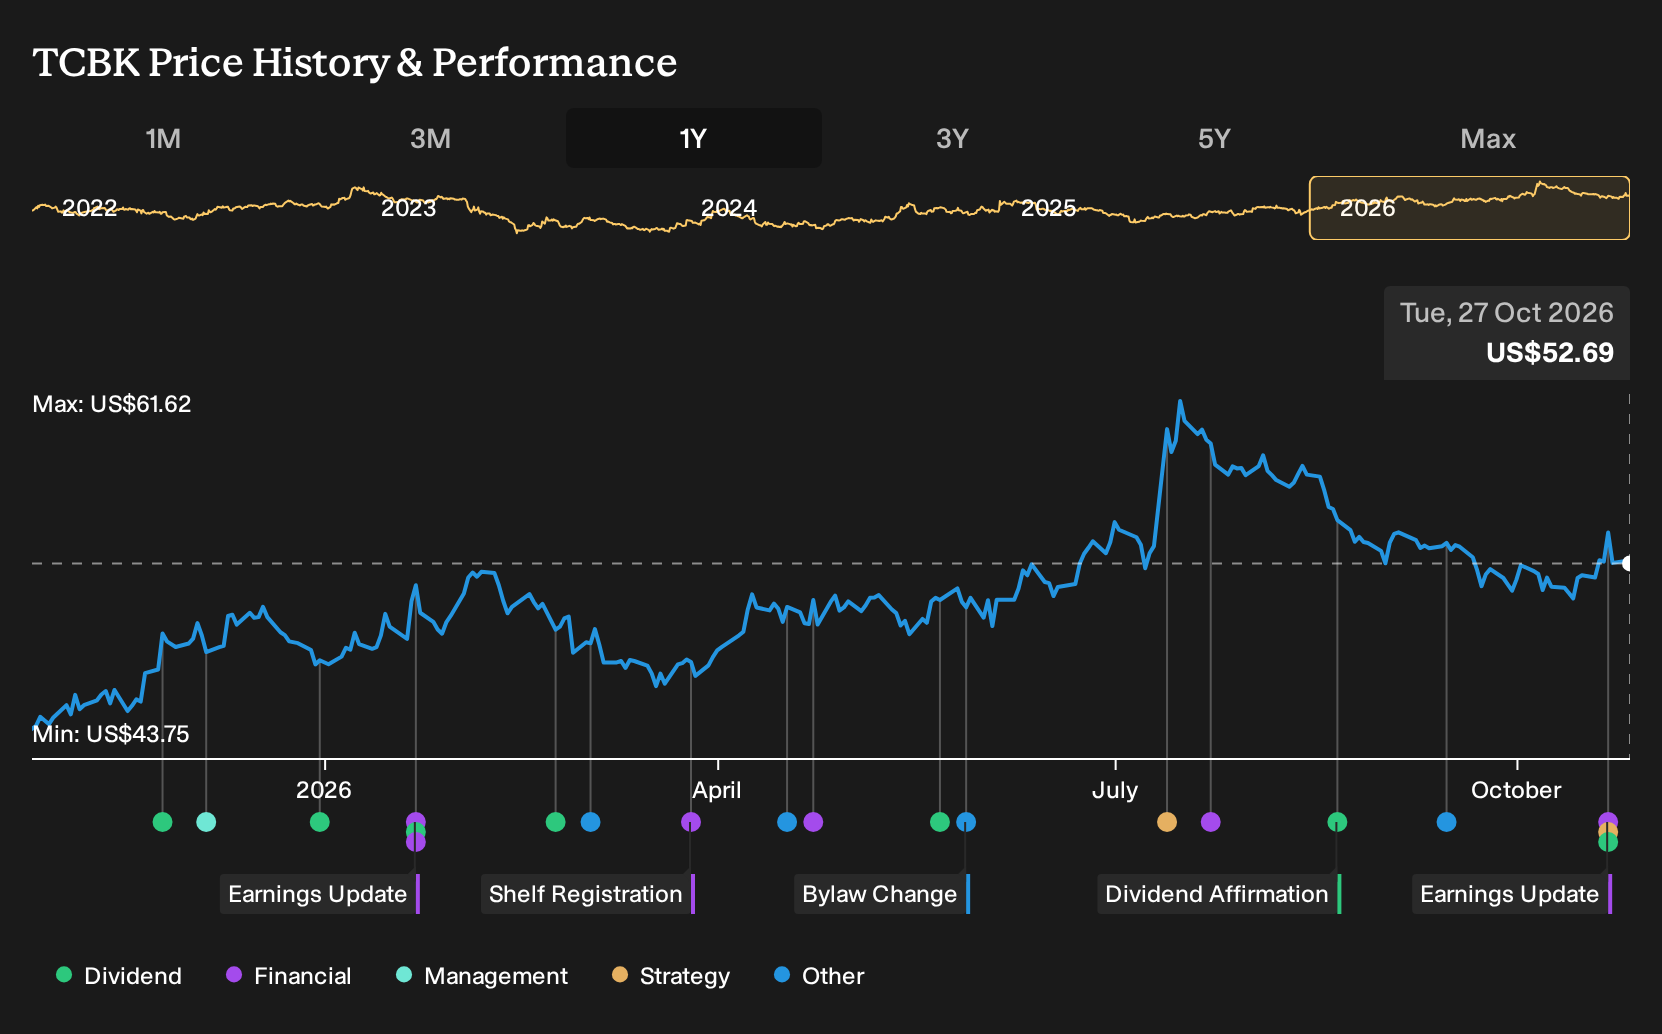
The most relevant update here is the third quarter earnings release on October 22, 2026. Higher quarterly EPS from continuing operations, at US$1.18 diluted and US$1.19 basic, together with US$3.29 diluted EPS across the first nine months, provides a clearer read on how TriCo Bancshares enters the merger phase operationally.
For catalysts, this earnings profile feeds directly into the projected EPS accretion analysts expect from the First Hawaiian combination. On the risk side, even with small net charge offs of US$0.3 million, the real test is whether similar credit discipline and margin performance can be maintained while pursuing the planned 25% cost savings from IT and vendor consolidation.
TriCo Bancshares' analyst narrative points to forecast revenue of US$515.4 million and projected earnings of US$145.0 million by 2029. These figures are described as being built on an assumed 6.5% yearly revenue growth rate and an earnings increase of US$9.5 million from current earnings of US$135.5 million.
Uncover how TriCo Bancshares' fair value indicates an 11% potential upside to its current price before the market narrows that discount.
Exploring Other Perspectives
Only two fair value estimates from the Simply Wall St Community cluster tightly between US$57.84 and US$58.67, so you are seeing a narrow band rather than wild disagreement. The merger with First Hawaiian, the 25% cost saving goal and the investigation into deal terms all give you reasons to test TriCo Bancshares against more varied opinions.
Explore another TriCo Bancshares fair value estimate, including one that suggests as much as 11% upside from the current price.
Form Your Own Verdict
Don't just follow the ticker, dig into the data and build a conviction that's truly your own.
- A great starting point for your TriCo Bancshares research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for TriCo Bancshares. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, which makes it easy to evaluate TriCo Bancshares' overall financial health at a glance.
Looking For More Investment Ideas Beyond TriCo Bancshares?
Once you have a view on TriCo Bancshares, it often helps to line it up against other banks and financials that share similar qualities in balance sheet strength, income focus or perceived mispricing. The Simply Wall St Screener lets you scan for those types of stocks in a structured way instead of relying on headlines or chance ideas.
- If you want income that does more of the heavy lifting, review a set of yield focused opportunities through 5 dividend fortresses that balance payout size with underlying fundamentals.
- For readers who care about paying less than they think a business is worth, compare TriCo Bancshares with a curated pool of 29 high quality undervalued stocks where quality metrics and valuation signals line up more tightly.
- If capital preservation sits higher on your priority list, start with a 30 resilient stocks with low risk scores and filter for companies where balance sheet strength and risk scores are front and center.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com