


Seagate (NASDAQ:STX) surprises with Q3 sales but stock drops
Data storage manufacturer Seagate (NASDAQ:STX) reported revenue ahead of Wall Street’s expectations in calendar Q3 2026 (fiscal Q1 2027), with revenue up 61% year on year to $4.23 billion. Next quarter’s revenue guidance ($4.8 billion at the midpoint) was stronger than expected, coming in 6.7% above analysts’ consensus estimates. Its non-GAAP profit of $7.68 per share was 3.4% above analysts’ consensus estimates.
For more on Seagate, read our free full research report.
Seagate (STX) Q3 CY2026 highlights:
- Revenue $4.23 billion vs S&P analysts’ consensus estimates of $4.14 billion (61% year-on-year growth, 2.2% beat)
- Adjusted EPS $7.68 vs S&P analysts’ consensus estimates of $7.43 (3.4% beat)
- Adjusted EBITDA $2.22 billion vs analysts’ consensus estimates of $2.10 billion (52.4% margin, 5.5% beat)
- Revenue guidance $4.8 billion at the midpoint for Q4 CY2026, above analysts’ consensus estimates of $4.5 billion
- Adjusted EPS guidance $9.20 at the midpoint for Q4 CY2026, above analysts’ consensus estimates of $8.61
- Operating margin 48.8%, up from 26.4% in the same quarter last year
- Free cash flow margin 34.9%, up from 16.2% in the same quarter last year
- Inventory days outstanding 86, up from 83 in the previous quarter
- Market capitalization $146.5 billion
“Data creation, retention and reuse continue to compound storage demand with long term customer demand visibility reinforcing our view of a multi-year growth phase. Our HAMR-based technology roadmap enables us to address growing exabyte demand through areal density gains while maintaining supply discipline. Combined with our value-based pricing strategy and strengthened balance sheet, we believe Seagate can deliver profitable growth, strong cash generation and increased shareholder returns over the long term,” Mosley concluded.
Revenue growth
Reviewing a company’s long-term revenue performance reveals insights into its quality. Any business can have short-term success, but a top-tier one grows for years. Seagate’s revenue grew at a mediocre 3.7% compounded annual growth rate over the last five years, falling short of the semiconductor sector’s performance. Still, there are things to like about Seagate. Semiconductors are a cyclical industry, and long-term investors should be prepared for periods of high growth followed by periods of revenue contraction (which can sometimes present buying opportunities).
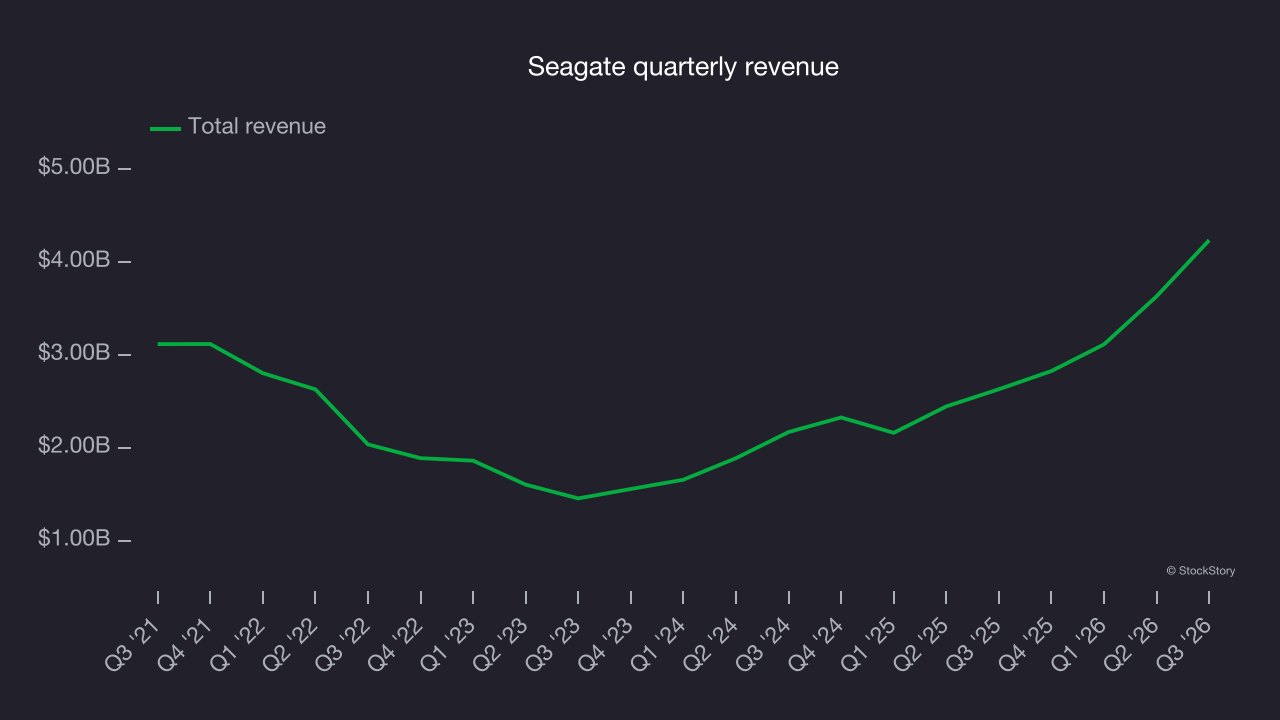
Long-term growth is the most important, but short-term results matter for semiconductors because the rapid pace of technological innovation (Moore’s Law) could make yesterday’s hit product obsolete today. Seagate’s annualized revenue growth of 37.8% over the last two years is above its five-year trend, suggesting its demand recently accelerated. 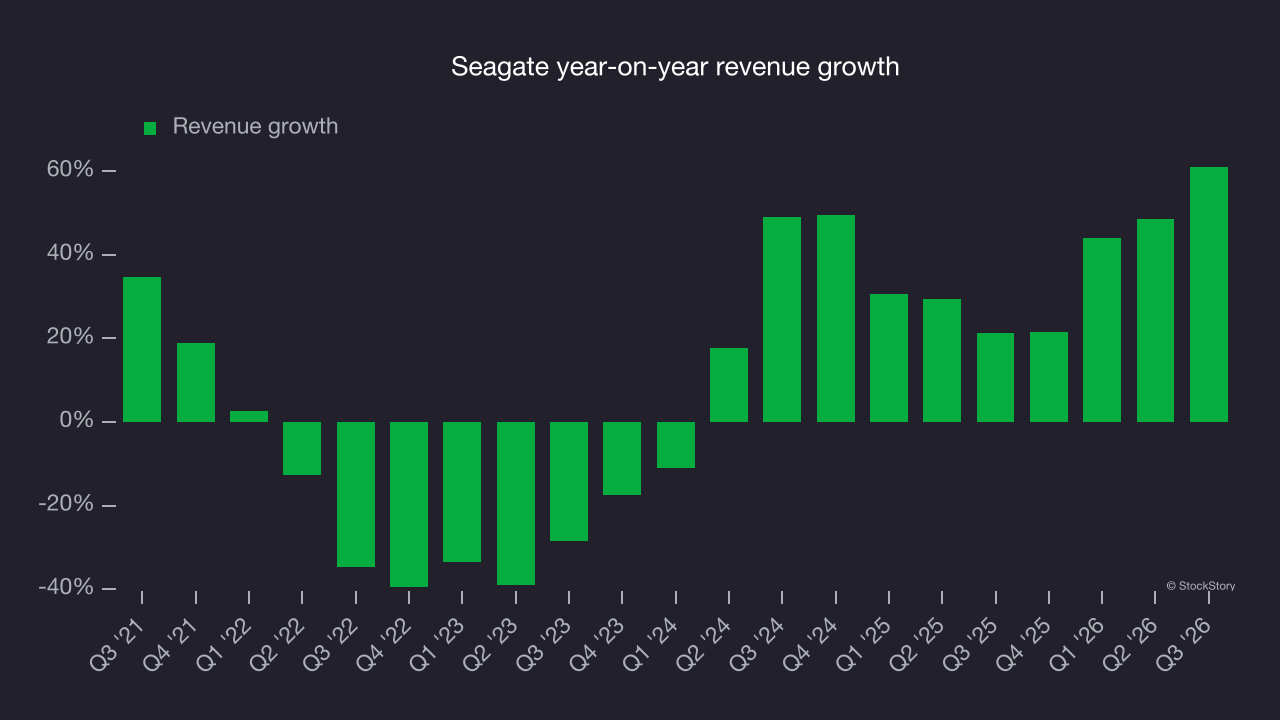
This quarter, Seagate reported year-on-year revenue growth of 61%, and its $4.23 billion of revenue beat Wall Street’s consensus estimates by 2.2%. Beyond the beat, this marks 10 straight quarters of growth, showing that the current upcycle has been sustained – a typical upcycle usually lasts 8-10 quarters. Company management is currently guiding for a 69.9% year-on-year increase in revenue next quarter.
Looking further ahead, sell-side analysts expect revenue to grow 49% over the next 12 months, according to S&P, an improvement versus the last two years. This projection is particularly noteworthy for a company of its scale and implies its newer products and services will spur better top-line performance.
Product demand & outstanding inventory
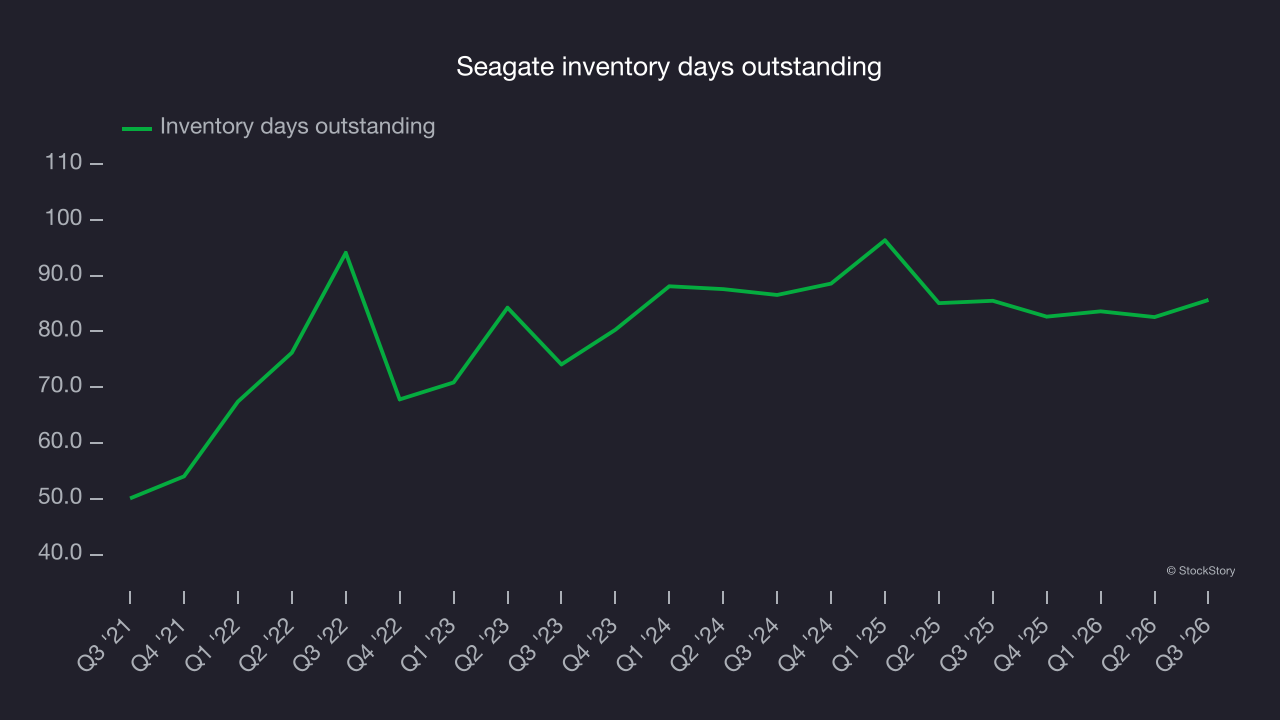
Days Inventory Outstanding (DIO) is an important metric for chipmakers, as it reflects a business’s capital intensity and the cyclical nature of semiconductor supply and demand. In a tight supply environment, inventories tend to be stable, allowing chipmakers to exert pricing power. Steadily increasing DIO can be a warning sign that demand is weak, and if inventories continue to rise, the company may have to downsize production.
This quarter, Seagate’s DIO came in at 86, which is 5 days above its five-year average, suggesting that the company’s inventory has risen above historical levels.
Key takeaways from Seagate’s Q3 results
Seagate delivered a solid quarter, with EPS beating Wall Street’s consensus estimates and next-quarter revenue guidance also coming in above consensus. Higher inventory levels were a negative. The market appeared to be hoping for more, and shares tumbled 7.5% to $619.50 immediately after the results.
Is Seagate an attractive investment right now? When making that decision, consider its valuation, business quality and latest quarterly results. Read our full research report here for more on Seagate (it’s free).