


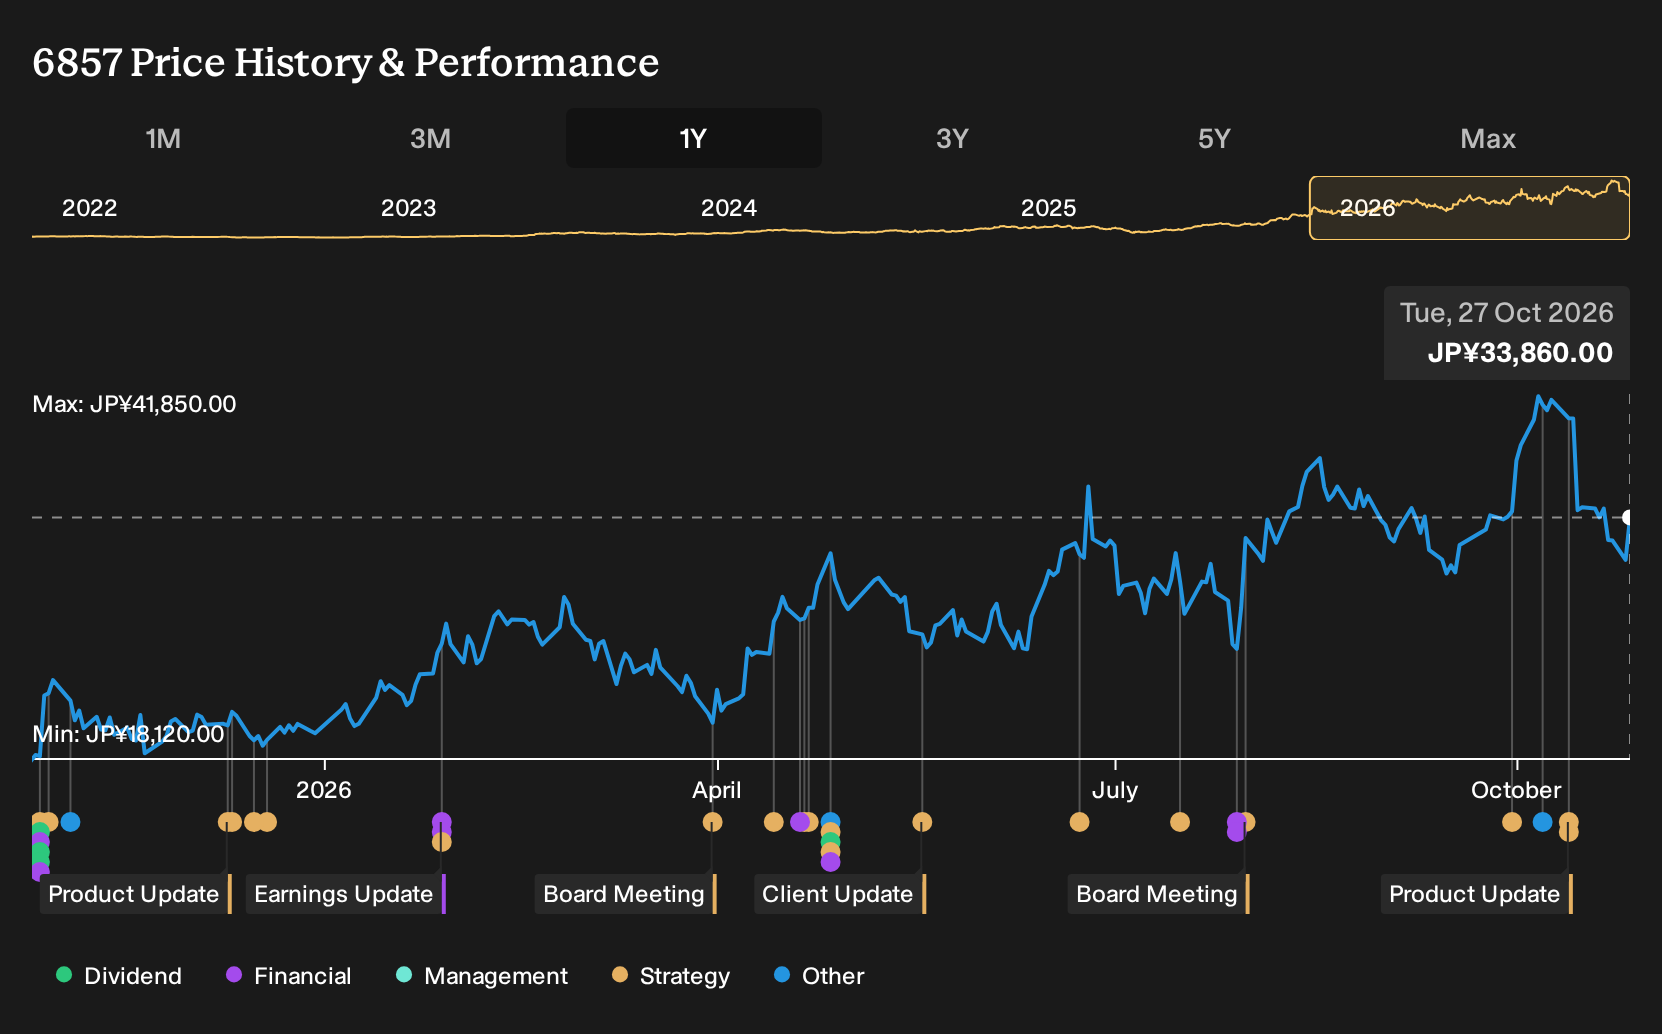
Advantest Stock Is Up 9.6% What's Changed With New AI Test Systems
- Advantest recently showcased its latest IC and semiconductor test platforms at the 2026 International Test Conference and SEMICON West, emphasizing coverage for AI, HPC, silicon photonics and advanced memory devices across its V93000 EXA Scale, system level test and DRAM solutions.
- The push to extend V93000 capabilities into silicon photonics, expand system level test coverage and integrate these offerings with AI enabled software suggests that Advantest is aiming to deepen test content per chip and increase stickiness with large compute and memory customers.
- We will now consider how Advantest's investment narrative could be influenced by its expanded V93000 EXA Scale AI testing focus.
Advantest Investment Narrative Recap
For you to stay interested in Advantest, the core belief is simple. The business needs to keep filling its expanded SoC and memory tester capacity with AI and high performance compute related demand while holding margins near recent levels despite higher bill of materials and DRAM costs. The latest AI focused test announcements mostly reinforce that operational story rather than change it.
The bigger swing factor in the near term still looks like utilization of that enlarged tester footprint. Any pause in AI related orders or a choppy rollout of new DRAM testers could pressure gross margin and earnings. Recent product news does not remove that risk, but it does broaden the toolset Advantest can take to customers.
The most relevant fresh development is the push around the V93000 EXA Scale SoC Test System and its AI focused software suite, including SmarTest 8 and Velocity for design to test automation. This cluster of tools is aimed at dealing with complex AI, HPC, PMIC, RF and ADAS devices, plus emerging areas such as silicon photonics and co packaged optics.
For catalysts, that breadth matters because it can support higher test content per chip and more software rich engagements, which ties directly into utilization and mix. Operationally, it also raises execution demands. Advantest has to qualify new silicon photonics and advanced memory test flows at scale, manage any lumpiness around memory platform transitions, and avoid letting aggressive capacity expansion turn into underused equipment and pressure on margins.
Advantest Forecasts Behind the AI Test Story
Advantest's narrative projects ¥2,709.1b revenue and ¥1,049.7b earnings by 2029. Analysts are incorporating assumptions of 30.0% yearly revenue growth and an earnings increase of about ¥589.7b from ¥460.0b today to reach that 2029 earnings mark.
Uncover why Advantest's fair value indicates a 25% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate angle on Advantest focuses less on margin risk and more on a potential upside catalyst around silicon photonics orders. Bullish analysts were already pencilling in ¥4,081.9b revenue and ¥1,619.8b earnings by 2029, before this ITC and SEMICON West news. That is a more optimistic story. Use it as a prompt to compare different scenarios and decide which assumptions feel realistic to you.
Explore 2 other Advantest fair value estimates, including one that suggests as much as 28% upside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Advantest research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Advantest. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Advantest's overall financial health at a glance.
Looking for more investment ideas beyond Advantest?
If the Advantest story has sharpened your interest in AI, testing and broader semiconductor exposure, it can help to compare it with other companies that fit clear financial profiles. The Simply Wall St Screener lets you filter the market by balance sheet strength, valuation and risk profile so you can build a watchlist that suits your own goals.
- For investors who care most about financial resilience, focus on businesses with strong cash positions and low leverage by scanning our list of solid balance sheet and fundamentals (23 results).
- If you are hunting for potential mispriced opportunities, narrow the field to stocks that combine quality fundamentals with attractive valuations through the 16 high quality undervalued stocks.
- For a calmer ride through market swings, concentrate on steadier companies by filtering the market with the 22 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com