


Sumitomo Pharma Stock In Focus After FDA Breakthrough Therapy Tag For Leukemia Drug
- Sumitomo Pharma America reported that the FDA granted Breakthrough Therapy designation to enzomenib, an oral small molecule, for treating relapsed or refractory acute leukemia with KMT2A rearrangement, based on ongoing trials as monotherapy and in combination with standard regimens.
- This regulatory status can compress development timelines and concentrate resources around enzomenib, which matters for Sumitomo Pharma as it rebalances earnings pressure from expiring products and higher planned R&D outlays.
- We will examine how Sumitomo Pharma's investment narrative may shift as enzomenib secures FDA Breakthrough Therapy designation for acute leukemia.
Compare how the Sumitomo Pharma story fits alongside other potential healthcare breakouts by scanning our hand-picked 10 healthcare AI stocks poised around similar high-impact treatment themes.
Sumitomo Pharma Investment Narrative Recap
To own Sumitomo Pharma, you need to believe the business can shift from leaning on ORGOVYX, GEMTESA and one off gains toward a more durable mix of oncology and regenerative assets. The Breakthrough Therapy designation for enzomenib sharpens that story as a near term proof point, but it does not change the fact that earnings are currently forecast to decline.
The key short term swing factor remains how North America performs as older drugs lose exclusivity and U.S. pricing pressure builds. The biggest risk is that higher R&D and restructuring costs arrive just as milestone income and the China Asia windfall fade, leaving margins exposed if new products like enzomenib take longer to contribute.
The recent FDA decision on enzomenib sits alongside Sumitomo Pharma's broader push in oncology, which also features nuvisertib and cell based programs. This new designation aligns with management's plan to share development through joint partnerships while trying to keep more of the future upside, which matters when R&D is expected to run higher.
For you, the question is how this accelerates or de-risks the existing catalyst map. If enzomenib progresses efficiently through trials, it could help counterbalance pressure from generic entry, one off items and potential U.S. pricing headwinds. If timelines stretch or data disappoints, the group is left more exposed to the expected earnings decline and funding entirely via higher risk borrowing.
Sumitomo Pharma's current analyst narrative points to revenues of ¥632.7b and earnings of ¥84.8b by 2029, built on an assumed 10.0% yearly revenue growth rate and an earnings decline of ¥27.9b from ¥112.7b today.
Uncover why Sumitomo Pharma's fair value indicates a 15% potential upside to its current price, which could narrow quickly.
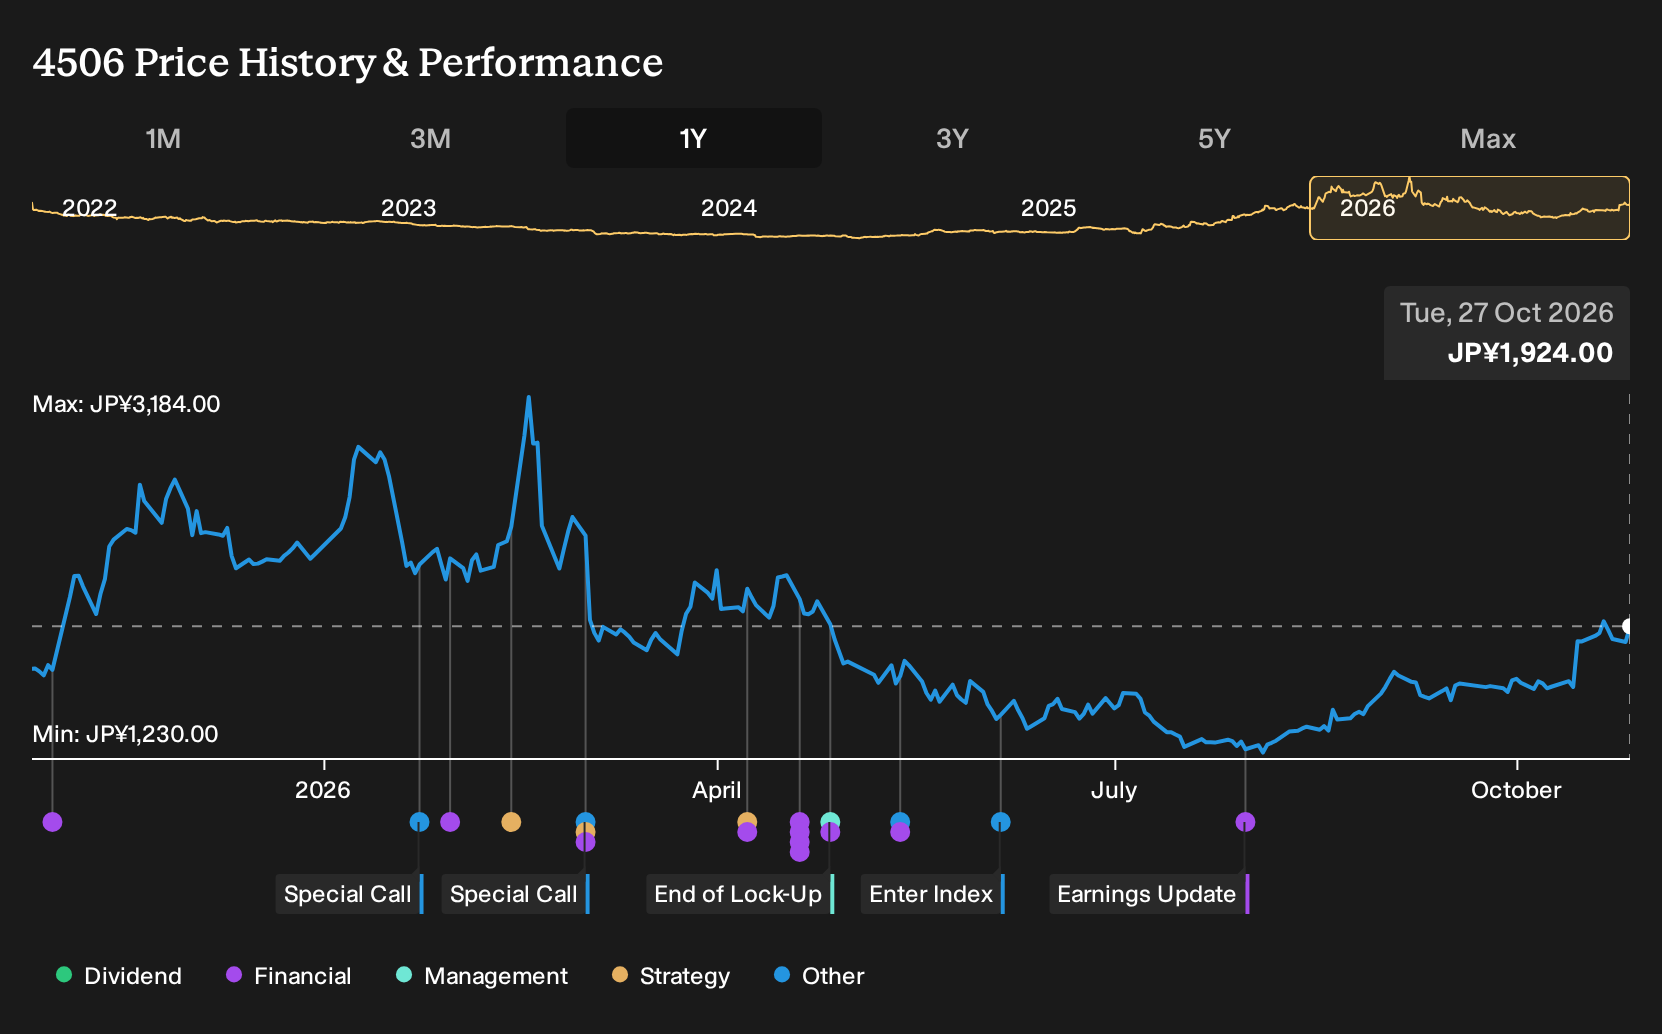
Exploring Other Perspectives
One alternate storyline around Sumitomo Pharma leans hard into enzomenib as a future oncology pillar. The most optimistic analysts were already pencilling in ¥758.5b of revenue and ¥159.5b of earnings by 2029, well above consensus. Those forecasts came before this Breakthrough Therapy news, so views may now shift in several directions.
Explore 2 other Sumitomo Pharma fair value estimates, including one that suggests as much as 147% upside from the current price!
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Sumitomo Pharma research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Sumitomo Pharma. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Sumitomo Pharma's overall financial health at a glance.
Looking for more investment ideas beyond Sumitomo Pharma?
Once you have a view on Sumitomo Pharma, it can help to widen the lens and compare it with other businesses that fit different risk and income profiles using the Simply Wall St Screener.
- For potential mispriced opportunities with stronger quality markers, scan our hand picked 16 high quality undervalued stocks that might suit a patient, fundamentals first approach.
- If capital preservation and steadier profiles matter more to you, focus on companies in the 22 resilient stocks with low risk scores that carry lower overall risk scores.
- For investors who want resilient finances as a starting filter, begin with the list of solid balance sheet and fundamentals (23 results) and see which businesses clear that hurdle before you go deeper.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com