


Brightstar Lottery (BRSL) After Cash Pop Launches Is The Undervalued Case Back On Track
Brightstar Lottery (NYSE:BRSL) is back in focus after its patented Cash Pop draw-based game went live with both the Illinois Lottery and the Ontario Lottery and Gaming Corporation in late October 2026.
Despite the Cash Pop launches in Illinois and Ontario and the recent Pan Am licensing deal, Brightstar Lottery’s 1-year total shareholder return is down 39.69%, and the 5-year total shareholder return has declined 55.39%, while the share price has weakened 37.91% year to date. This suggests longer term momentum has been fading even as new contracts draw fresh attention to the story.
Contrast Brightstar Lottery’s mixed share-price record with other potential turnaround stories by scanning our hand picked list of 21 high quality undiscovered gems, which also sit at the crossroads of contracts and momentum.
Brightstar Lottery now trades well below analyst targets, even as new deals roll in. Does that set up a better entry today, or is patience on price still the smarter call once the numbers are laid out?
Most Popular Narrative: 43% Undervalued
Brightstar Lottery closed at $9.50, while the most widely followed narrative pegs fair value closer to $16.71 using a 13.56% discount rate. That gap highlights a clear tension between a weak share price track record and a model that still points to upside.
Regulatory liberalization and successful contract renewals (notably Italy Lotto secured through 2034 and new or extended deals in Missouri, Portugal, and France) are expanding the addressable market and extending Brightstar's average revenue weighted contract life to 7 years, providing long term revenue stability and enhanced cash flow visibility.
See why 2 investors see Brightstar Lottery as 43% undervalued.
Result: Fair Value of $16.71 (UNDERVALUED)
Still, heavier Italy renewal costs and any tightening of gambling rules in key markets could quickly challenge the perception that Brightstar Lottery is undervalued.
Find out about the key risks to this Brightstar Lottery narrative.
Another View: Brightstar Lottery Through The DCF Lens
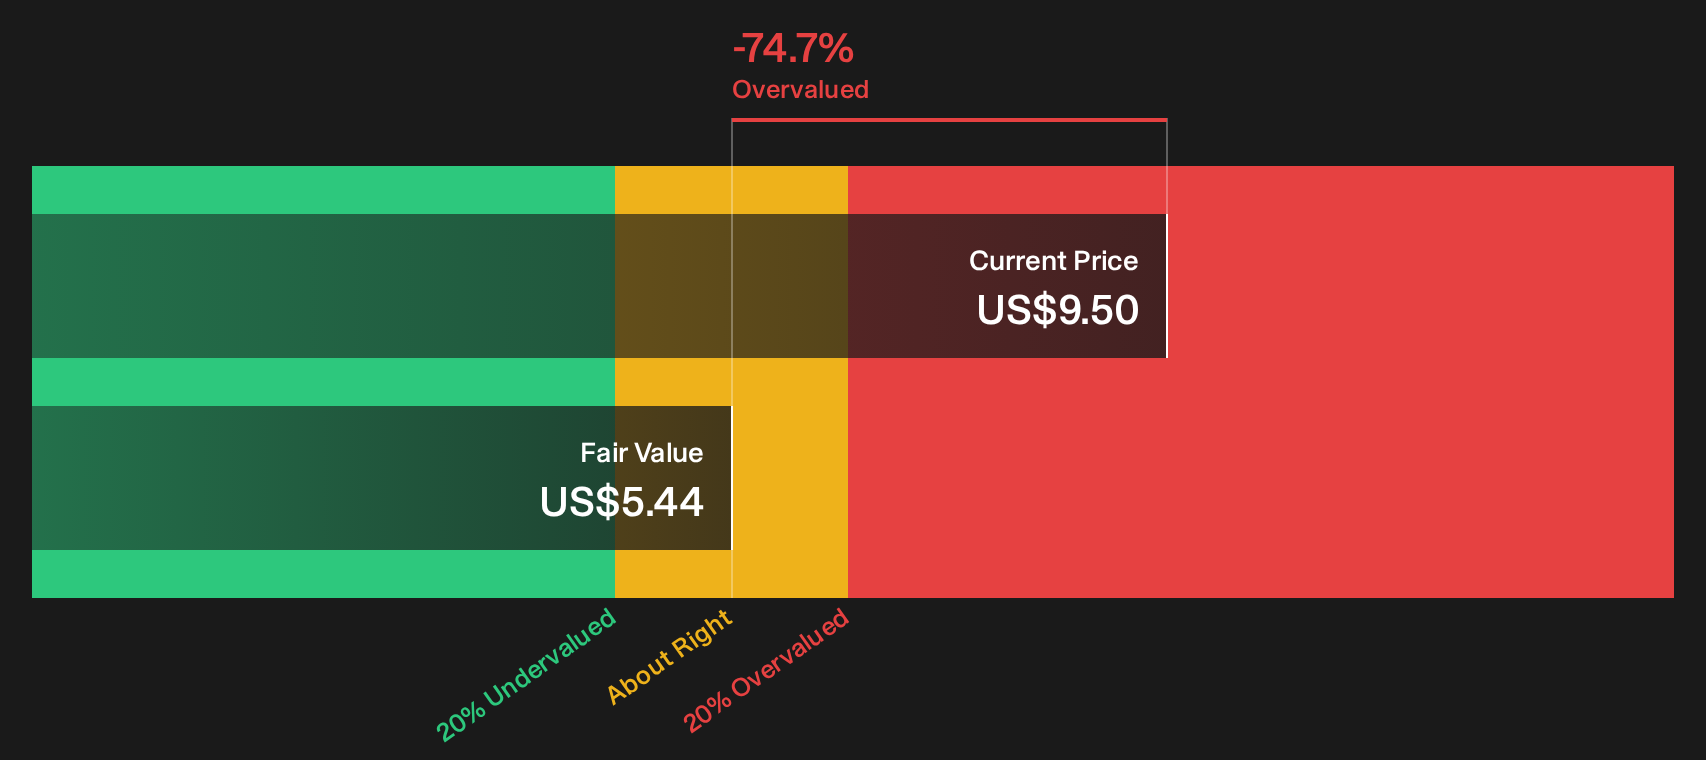
The popular fair value narrative leans on analyst targets, yet the SWS DCF model points in a different direction. On that cash flow view, Brightstar Lottery at $9.50 trades above an estimated value of $5.44, which screens as overvalued on future cash generation rather than cheap.
The split is stark. One framework highlights upside to $16.71, while the DCF output flags downside risk from here. That gap raises a simple question for any holder: which story about future cash flows feels more realistic?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Brightstar Lottery for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals or a clear setup? If Brightstar Lottery’s story feels pulled between risk and recovery, move quickly to test the numbers yourself and weigh the balance of 3 key rewards and 4 important warning signs.
Looking for more Brightstar Lottery sized ideas?
If Brightstar Lottery has you rethinking your watchlist, do not stop here. Use the Simply Wall Street screener to quickly surface fresh, data driven ideas before others move.
- Target potential value plays that pair quality fundamentals with discounted prices by running the 29 high quality undervalued stocks.
- Strengthen your downside protection by focusing on companies that show resilient balance sheets through the list of solid balance sheet and fundamentals (24 results).
- Zero in on opportunities the market may be overlooking by scanning the 21 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com