


Zoetis' Q3 2026 Earnings: What to Expect
Parsippany, New Jersey-based Zoetis Inc. (ZTS) discovers, develops, manufactures, and commercializes medicines, vaccines, diagnostic products and services, biodevices, genetic tests, and precision animal health solutions for the animal health industry. Valued at $33.5 billion by market cap, the company also offers parasiticides, vaccines, dermatology, anti-infectives, pain and sedation, other pharmaceutical, and animal health diagnostics. The world’s leading animal health company is expected to announce its fiscal third-quarter earnings for 2026 before the market opens on Thursday, Nov. 5.
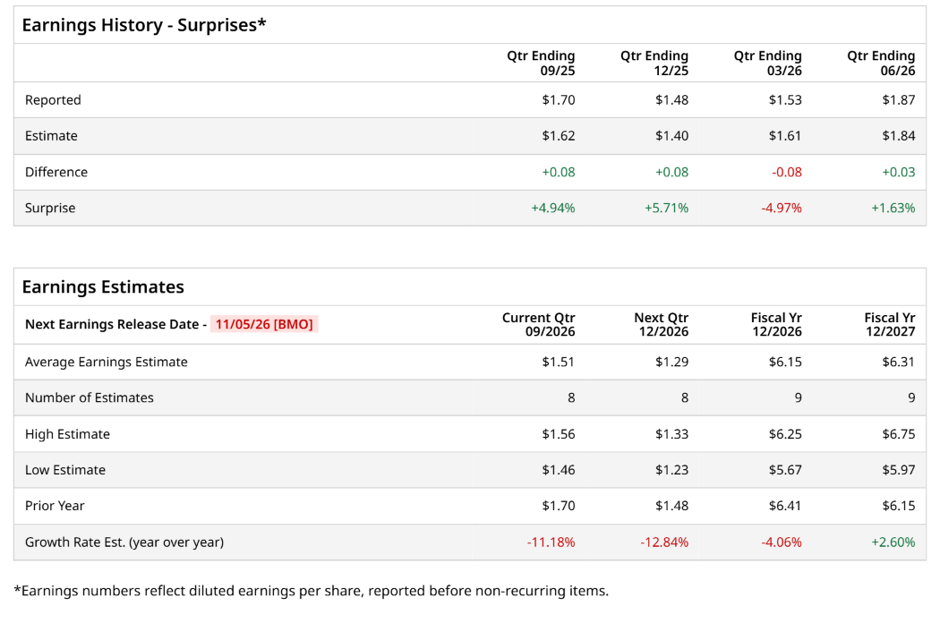
Ahead of the event, analysts expect Zoetis to report a profit of $1.51 per share on a diluted basis, down 11.2% from $1.70 per share in the year-ago quarter. The company beat the consensus estimates in three of the last four quarters while missing the forecast on another occasion.
For the full year, analysts expect Zoetis to report EPS of $6.15, down 4.1% from $6.41 in fiscal 2025. However, its EPS is expected to rise 2.6% year over year to $6.31 in fiscal 2027.
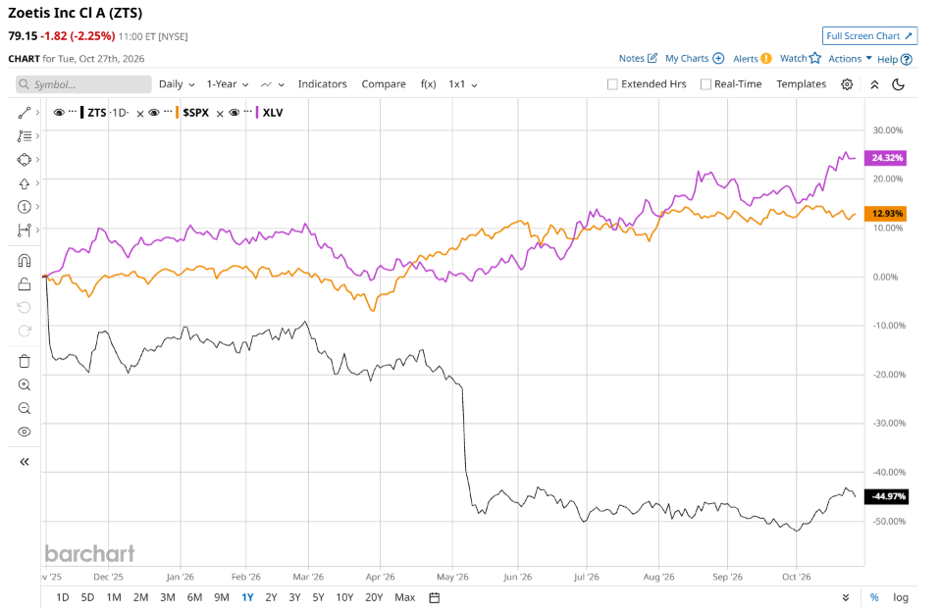
ZTS stock has considerably underperformed the S&P 500 Index’s ($SPX) 13% gains over the past 52 weeks, with shares down 46% during this period. Similarly, it notably underperformed the State Street Health Care Select Sector SPDR ETF’s (XLV) 22.8% returns over the same time frame.
Zoetis underperformed as intensifying competition and declining U.S. veterinary clinic visits weighed on its Companion Animal business. CEO Kristin Peck noted visits fell again amid pet owners becoming more price-sensitive, pressuring key franchises like Apoquel and Simparica Trio. Zoetis cut full-year revenue and profit guidance and is responding with sharper commercial execution, cost discipline, and accelerated innovation. Moreover, management expects U.S. Companion Animal headwinds to persist into the second half.
On Aug. 6, ZTS shares closed up by 3.9% after reporting its Q2 results. Its adjusted EPS of $1.87 beat Wall Street expectations of $1.84. The company’s revenue was $2.47 billion, falling short of Wall Street forecasts of $2.49 billion. ZTS expects full-year adjusted EPS in the range of $6.15 to $6.25, and revenue in the range of $9.1 billion to $9.3 billion.
Analysts’ consensus opinion on ZTS stock is reasonably bullish, with a “Moderate Buy” rating overall. Out of 17 analysts covering the stock, five advise a “Strong Buy” rating, one suggests a “Moderate Buy,” 10 give a “Hold,” and one recommends a “Strong Sell.” ZTS’ average analyst price target is $95.93, indicating a potential upside of 20.3% from the current levels.
On the date of publication, Neha Panjwani did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.