


Does New COO Appointment Change The Bull Case For Newell Brands Stock (NWL)?
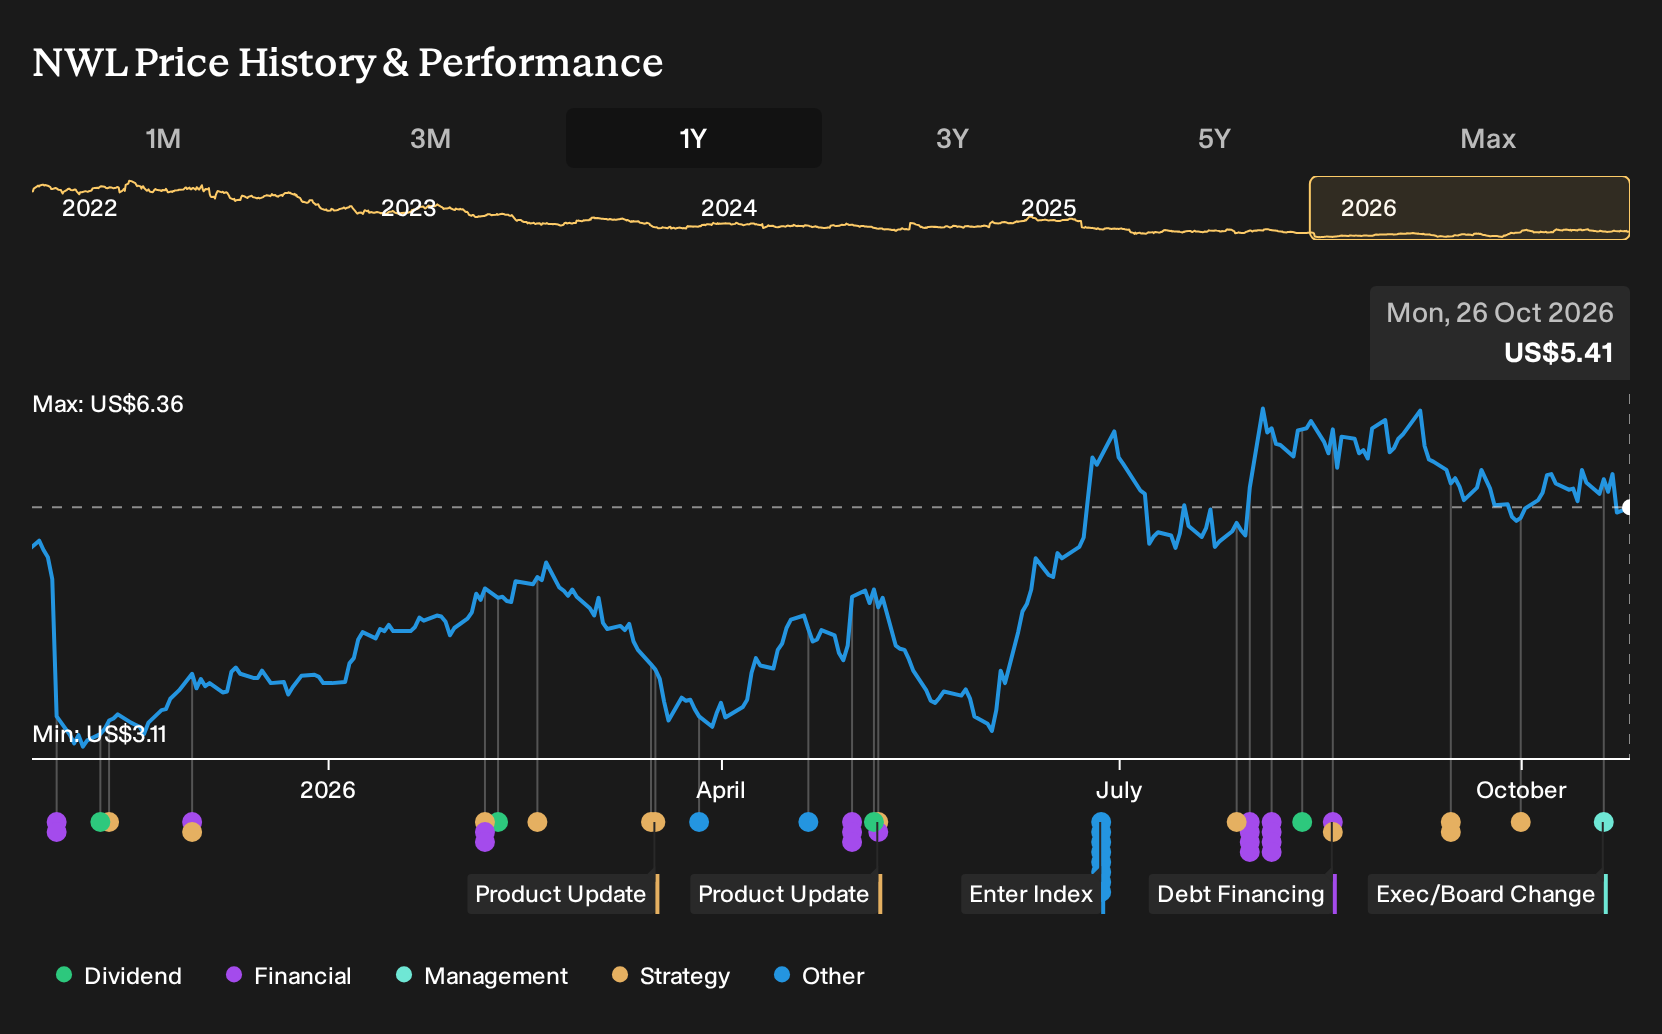
- Newell Brands appointed Guillermo Beade as Chief Operating Officer, effective October 26, 2026, giving him global responsibility for marketing, sales, and supply chain after three decades in senior roles at SC Johnson, PepsiCo, and Unilever.
- The move puts an experienced consumer packaged goods operator over Newell Brands' core commercial engine at the same time management signals year-over-year revenue and earnings improvement for the third quarter of 2026.
- Investors will now be able to observe how Newell Brands' investment narrative may be influenced by Beade's appointment as COO and his operational remit.
Newell Brands Investment Narrative Recap
To own Newell Brands, you need to believe management can translate product refresh, marketing and channel work into steadier sales and a path back to sustainable profitability. The key near term catalyst is execution on that plan, as the company targets year over year improvement in third quarter revenue and earnings. The new COO appointment shapes who runs that playbook, not the overall thesis.
The biggest immediate risk is that weak category demand, pricing pressure or retailer pushback keep core sales under strain, while leverage and interest costs limit room for error. If Beade’s integration of marketing, sales and supply chain stalls or disrupts operations, the impact on margins and cash generation could weigh on that recovery story.
The most relevant announcement alongside Beade’s appointment is management’s expectation for year over year gains in revenue and earnings in the third quarter of 2026, with operating margin and EPS aligned to that improvement. That guidance sets a clear execution bar for Newell Brands, while investors watch how a seasoned operator settles into the COO role.
Your focus now is whether the new leadership structure can support better product sell through, cleaner supply chain performance and more disciplined spending at the same time. If those pieces move together, the existing catalysts around cost savings, ERP harmonization and portfolio focus have more room to show up in reported numbers. If not, the long list of risks, from macro sensitivity to tariff exposure and dividend coverage, stays front and center.
Newell Brands' narrative projects US$7.7b revenue and US$557.1m earnings by 2029. This implies 1.9% yearly revenue growth and an earnings swing of about US$778m from a loss of US$221.0m today to the forecast consensus earnings level.
Uncover why Newell Brands' fair value indicates a 23% potential upside to its current price before that discount narrows.
Exploring Other Perspectives
Not every analyst buys the idea that Newell Brands can keep squeezing more efficiency from automation and AI programs. The most cautious forecasts, set before this COO news, pointed to revenue near US$7.5b and earnings around US$390.0m by 2029. That more skeptical camp may rethink its story once Beade’s influence becomes clearer, and you can compare those views directly.
Explore 3 other Newell Brands fair value estimates, including one that suggests it could be worth just $6.66!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A great starting point for your Newell Brands research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Newell Brands. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Newell Brands' overall financial health at a glance.
Looking For More Investment Ideas Beyond Newell Brands?
If Newell Brands has sharpened your interest in how different businesses are priced and financed, it can be useful to compare it with a wider watchlist built around clear traits you care about.
- If you want potential mispricing to work in your favor, start with a curated pool of companies that screen as attractively valued through 29 high quality undervalued stocks.
- For those who care most about balance sheet strength and durability through different cycles, build a shortlist from the list of solid balance sheet and fundamentals (24 results).
- When capital preservation and lower volatility sit higher on your checklist, anchor your research around the 30 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com