


Data#3 (ASX:DTL) Shares Climbed, What Is Driving Attention Now?
Data#3 (ASX:DTL) is in focus after pushing deeper into AI services built around Microsoft 365 Copilot, AI analytics and AI security, while shifting more customers onto multiyear subscription and as-a-service contracts.
Recent momentum around Data#3’s AI push has coincided with a rising share price, with the stock delivering a 30 day share price return of 25.14% and a year to date share price return of 53.65%. The 5 year total shareholder return of 178.69% points to a longer track record that investors are weighing against today’s higher A$13.89 entry price.
Scan beyond Data#3 and size up other AI-focused technology stocks using our curated list of 10 AI small caps that are also leaning into Copilot-style services and recurring revenue models.
Data#3 now appears to be a solid AI services platform supported by recurring contracts, yet the share price has surged ahead of that narrative. Is the quality of the business matched by the price on offer today?
Most Popular Narrative: 16% Overvalued
Analysts currently see fair value for Data#3 at A$11.99, which sits below the last close of A$13.89, so the key question is whether the business can live up to the richer expectations baked into that higher trading price.
The accelerating shift by customers to multiyear subscription and as-a-service models (evidenced by recurring revenue increasing to 69% and rapid expansion in Device-as-a-Service) positions Data#3 for higher, more stable, and predictable revenue and margin growth over time as the mix continues to improve. Enterprise and government digital transformation is driving robust demand for IT infrastructure upgrades, devices, cloud integration, and AI deployment in areas where Data#3 consistently grows ahead of the market, supported by record device refresh cycles and increasing public and education sector spend, boosting topline revenue and gross profit.
See why 44 investors see Data#3 as 16% overvalued.
Result: Fair Value of A$11.99 (OVERVALUED)
Still, concentrated reliance on major vendors and rising wage pressure could squeeze margins at Data#3 and challenge the rich expectations now embedded in the share price.
Find out about the key risks to this Data#3 narrative.
Another View: Data#3 Through The SWS DCF Lens
Analysts see Data#3 as 16% overvalued at A$13.89 versus their A$11.99 target, yet the SWS DCF model points the other way, with a fair value estimate of A$14.48 and the stock at a 4.1% discount. Which set of assumptions do you trust more?
To understand how this cash flow approach arrives at its estimate, and what would need to change for that figure to move meaningfully, Look into how the SWS DCF model arrives at its fair value.
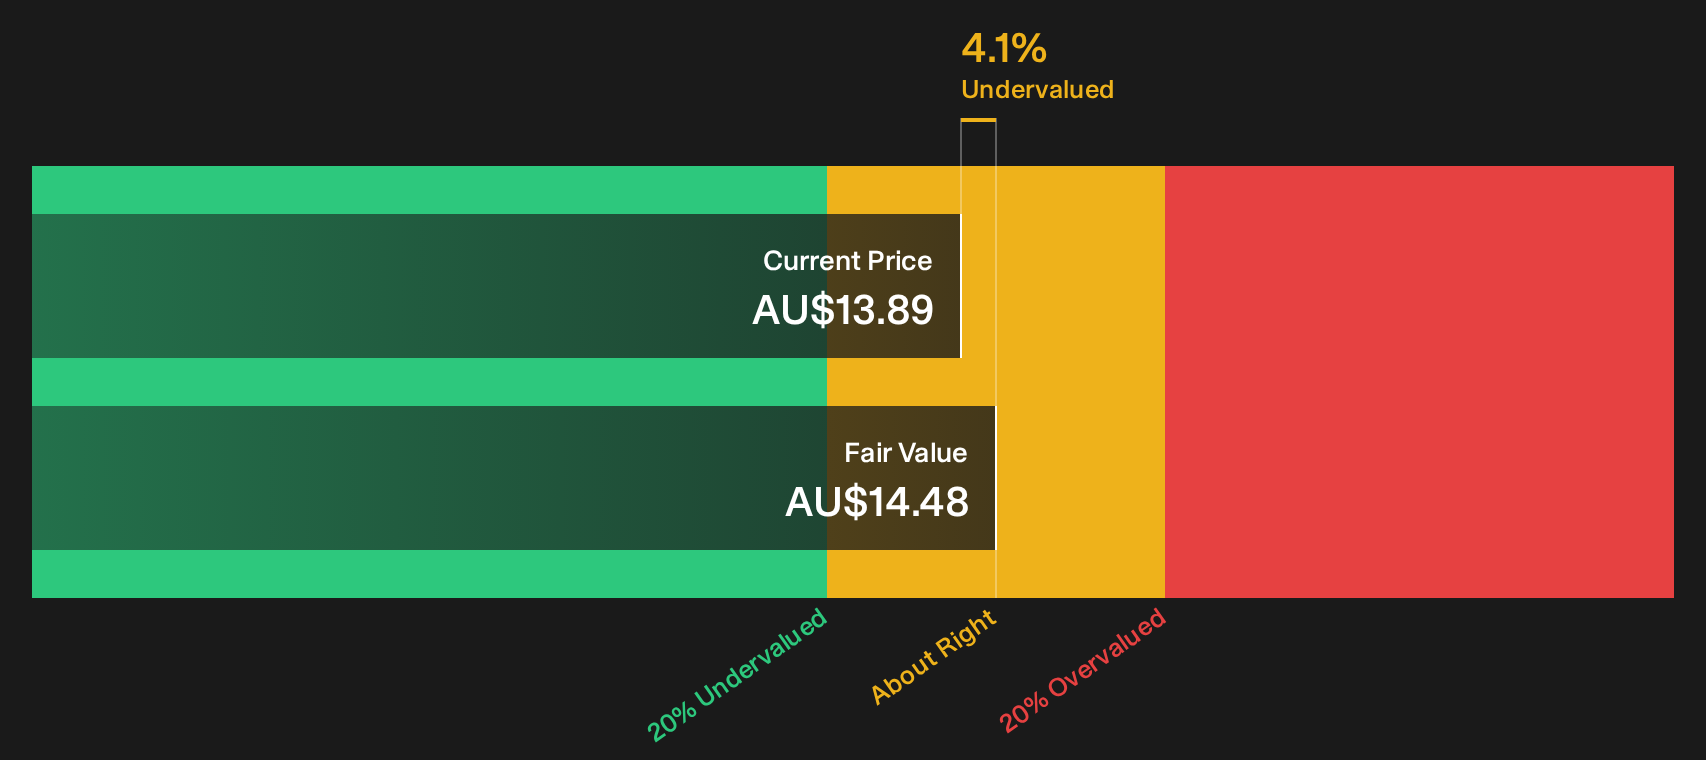
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Data#3 for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 2 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Data#3’s value and risk make this a moment to move quickly and review the underlying numbers yourself. To consider the concerns alongside the potential upsides in one place, review the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Data#3?
If Data#3 has sharpened your focus on quality opportunities, do not stop here. Use the screener to widen your watchlist and pressure test your next moves.
- Target resilient balance sheets by scanning a list of solid balance sheet and fundamentals (12 results) that can help you stress test ideas before committing capital.
- Hunt for potential value opportunities by reviewing a 2 high quality undervalued stocks that pairs cash flow strength with disciplined financial profiles.
- Stack your income shortlist by filtering for a 4 dividend fortresses that aims for higher yields backed by sturdier fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com