


Entergy (ETR) Could Be 12% Undervalued Before Q3 2026 Earnings
Entergy (ETR) heads into its third quarter 2026 report with expectations of higher earnings and revenue, as traders watch whether the utility’s results align with the more optimistic analyst projections.
That optimism is showing up in the tape. Entergy’s recent 30-day share price return of 9.06% and year-to-date share price gain of 14.53% point to building momentum into the results, while the 3-year total shareholder return of 150.08% anchors the story in a much stronger longer-term record.
Scan for other utilities showing similar pre earnings momentum and financial profiles as Entergy by reviewing our curated list of 42 power grid technology and infrastructure stocks.
That recent jump in Entergy’s share price could be pointing to improving fundamentals, or it could reflect investors crowding into a bullish earnings story. To see which it looks more like, start with the valuation.
Most Popular Narrative: 10.4% Undervalued
Entergy’s most followed valuation narrative pegs fair value at $119.93 using a 7.24% discount rate, compared with the last close at $107.50. This frames the recent share price strength as still short of that implied level.
Capital investment that was previously framed at US$40b over four years has been expanded into a larger plan that now includes about 30 GW of new and repowered resources and over 1,000 miles of transmission using standardized designs. This could drive a higher regulated rate base and support earnings growth if projects are placed into service as planned.
See why 27 investors see Entergy as 10% undervalued.
Result: Fair Value of $119.93 (UNDERVALUED)
Still, the Entergy story can change quickly if regulators push back on large projects or if the bigger capital plan leads to heavier financing and dilution than analysts expect.
Find out about the key risks to this Entergy narrative.
Another View: Entergy looks expensive on earnings multiples
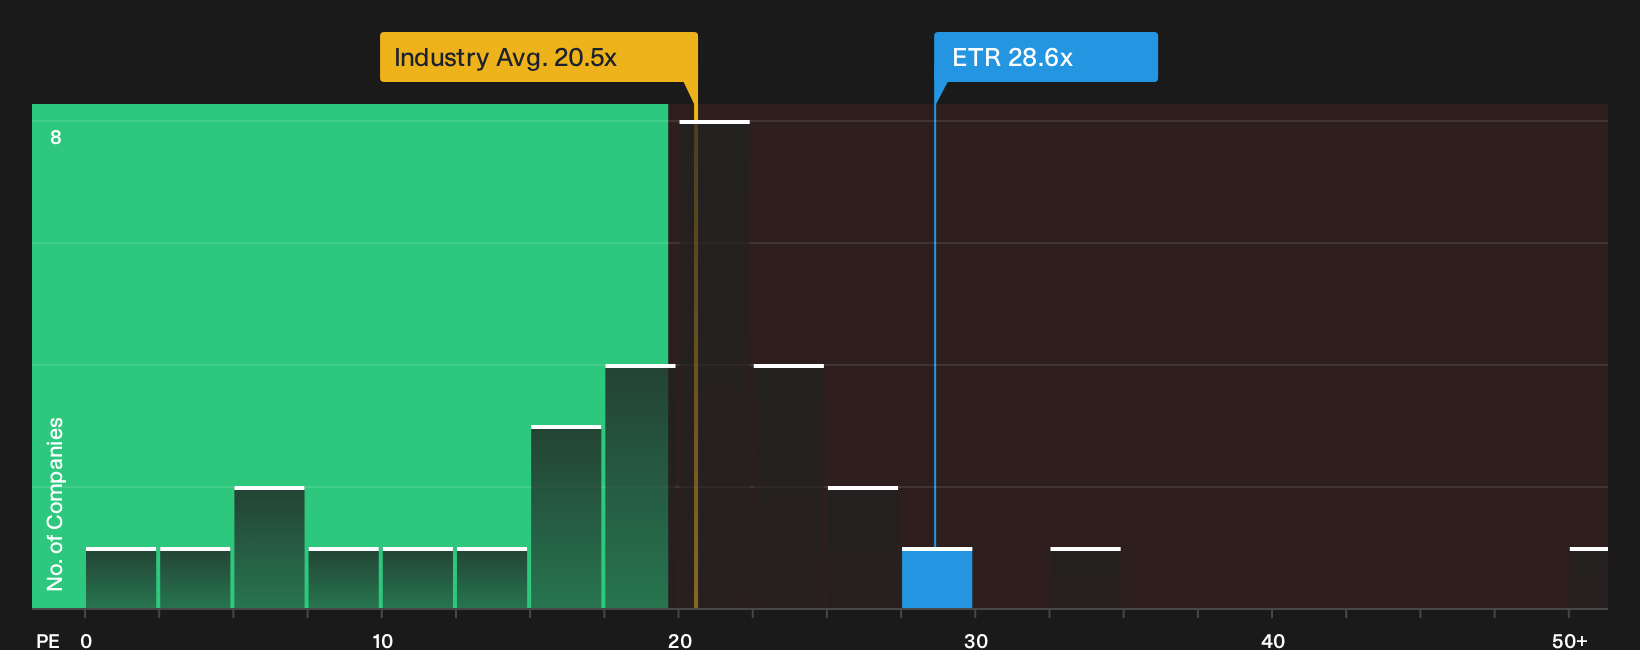
While the popular fair value narrative suggests Entergy is undervalued, the current P/E of 28.6x tells a tougher story. That figure sits above the US Electric Utilities industry at 20.6x and ahead of an estimated fair ratio of 23.6x, which points to less room for error if sentiment cools.
To see what the numbers say about this pricing gap, review the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Entergy’s valuation story so far. If you want to move quickly and make your own call, start by weighing its 2 key rewards and 2 important warning signs
Looking for more investment ideas beyond Entergy?
If Entergy has you thinking about what else might be lining up strong potential, broaden your watchlist now and do not let fresh opportunities pass by.
- Target dependable cash machines by scanning companies with generous yields and robust payouts through our 5 dividend fortresses.
- Spot potential bargains early by running a quick pass over companies flagged as quality prospects in the 21 high quality undiscovered gems.
- Protect your capital first by filtering for companies with healthier finances using the list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com