


PayPal (NASDAQ:PYPL) reports sales below analyst estimates in Q3 2026 earnings
Digital payments platform PayPal (NASDAQ:PYPL) fell short of the market’s revenue expectations in Q3 2026 as revenue rose only 2% year on year to $8.58 billion. Its non-GAAP profit of $1.45 per share was 10.7% above analysts’ consensus estimates.
For more on PayPal, read our free full research report.
PayPal (PYPL) Q3 2026 highlights:
- Volume $487.1 billion vs analysts’ consensus estimates of $491.3 billion (6.3% year-on-year growth, 0.9% miss)
- Revenue $8.58 billion vs S&P analysts’ consensus estimates of $8.71 billion (2% year-on-year growth, 1.4% miss)
- Pre-tax profit $1.37 billion (16% margin)
- Adjusted EPS $1.45 vs S&P analysts’ consensus estimates of $1.31 (10.7% beat)
- Adjusted EPS guidance Management raised its full-year adjusted EPS guidance to $5.60 at the midpoint, a 4.1% increase
- Market capitalization $47.04 billion
Revenue growth
A company’s long-term performance is an indicator of its overall quality. Any business can deliver a good quarter or two, but the best consistently grow over the long term. Over the last five years, PayPal grew its revenue at a mediocre 6.9% compounded annual growth rate. This fell short of the benchmark for the financials sector.
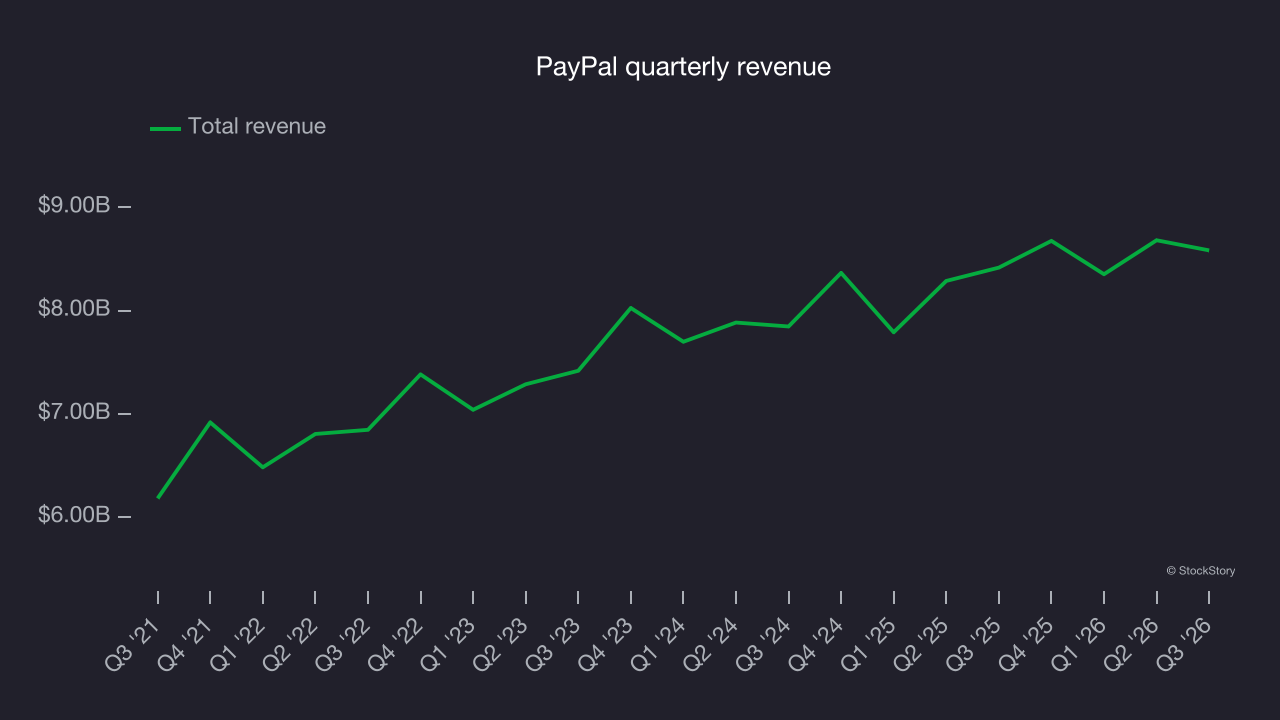
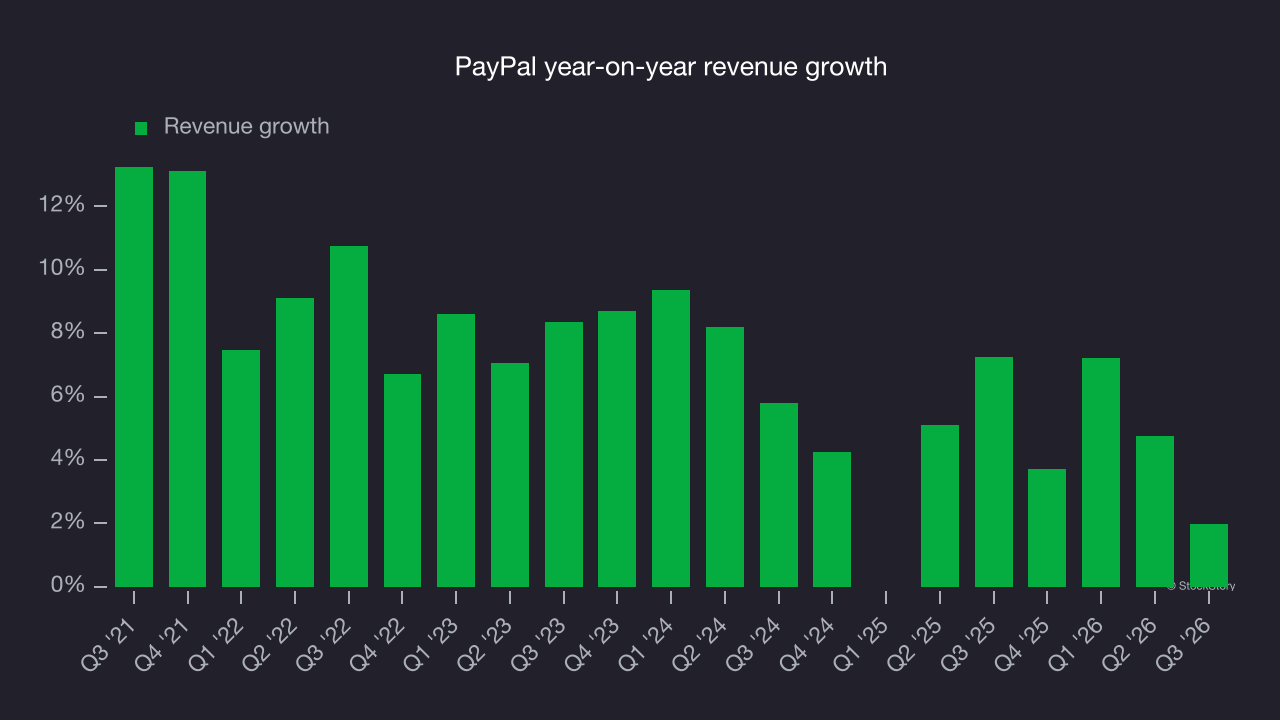
This quarter, PayPal’s revenue grew by 2% year on year to $8.58 billion, falling short of Wall Street’s consensus estimates.
Volume
Financial services companies rely heavily on the total number of transactions and loan originations to drive revenue growth. Understanding these volumes is essential for assessing companies in the sector.
PayPal’s volumes have grown at an annual rate of 10.1% over the last five years, slightly better than the broader financials industry and faster than its total revenue. Over the last two years, volume growth decelerated to 7.6% annually. Its recent performance could limit any potential valuation multiple expansion.
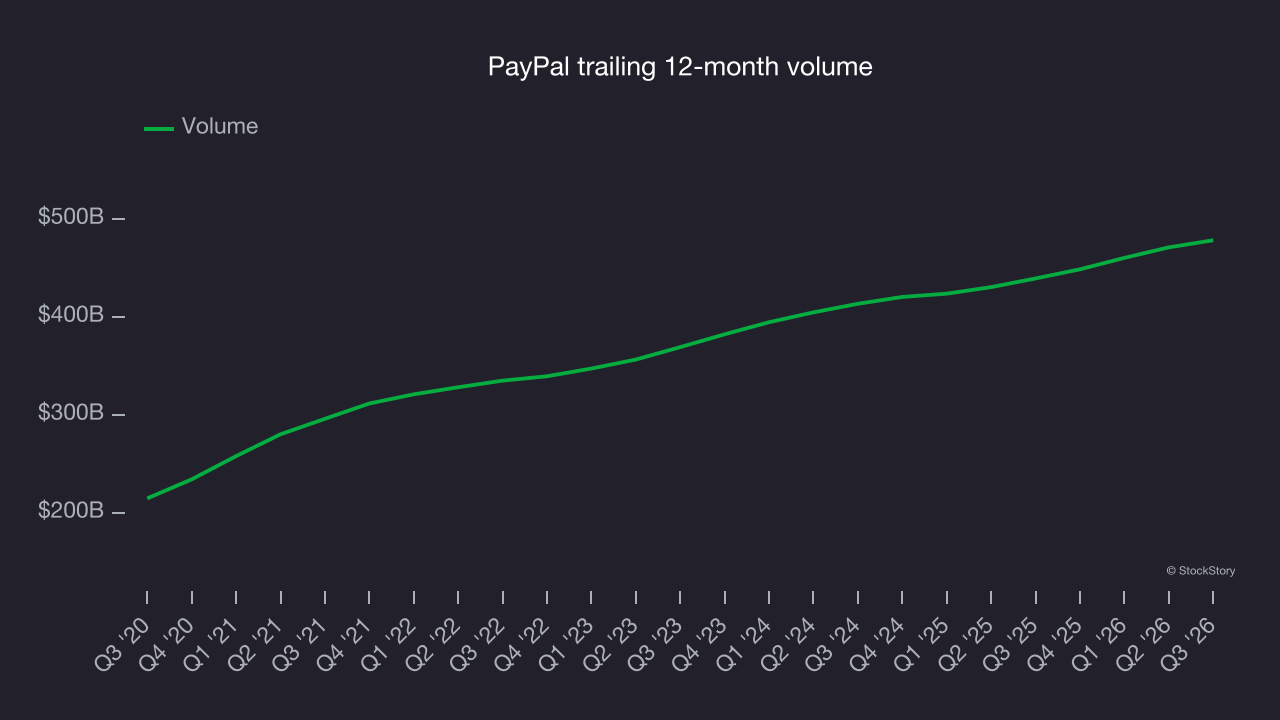
PayPal’s volumes totaled $487.1 billion this quarter, falling 0.9% short of analysts’ consensus estimates. Volumes rose 6.3% from the same quarter last year.
Key takeaways from PayPal’s Q3 results
PayPal’s quarter had clear positives: EBITDA beat analysts’ consensus estimates by a wide margin, and full-year EPS guidance topped Wall Street’s consensus. But transaction volumes and revenue both fell slightly short of expectations. Overall, it was mixed quarter. The market seemed to be hoping for more, with shares edging lower 1.3% to $54.21 immediately after the results.
To assess whether PayPal is an attractive buy at the current price, consider the bigger picture of valuation, business quality and the latest earnings. For more on PayPal, read the full research report here (it’s free).