


Catalyst Conference Could Be A Game Changer For Sinopec Stock
- China Petroleum & Chemical recently hosted its second international catalyst customer conference in Tianjin, bringing together representatives from 69 customers and partners across 24 countries to discuss more efficient catalysts for refining and chemical production and plans to expand its global service network.
- This catalyst focused gathering highlights how China Petroleum & Chemical is trying to deepen technology collaboration around cleaner, higher efficiency production processes that can influence its long term chemicals and refining mix.
- Next is a look at how China Petroleum & Chemical's investment narrative might shift as its catalyst program moves further into the spotlight.
China Petroleum & Chemical Investment Narrative Recap
To hold China Petroleum & Chemical, you need to believe it can steadily shift earnings away from gasoline and diesel toward chemicals, advanced materials and lower carbon aviation fuels, while keeping refining runs economic. In the short term the focus is still on throughput discipline, crude flexibility and export policy, not on boardroom headlines.
The new company secretary and authorised representative appears more procedural than transformational for the business. The nearer term share driver remains how quickly higher value products such as specialty chemicals and sustainable aviation fuel scale against any ongoing drag from weaker road fuel demand. The key risk remains a prolonged downturn in domestic oil consumption.
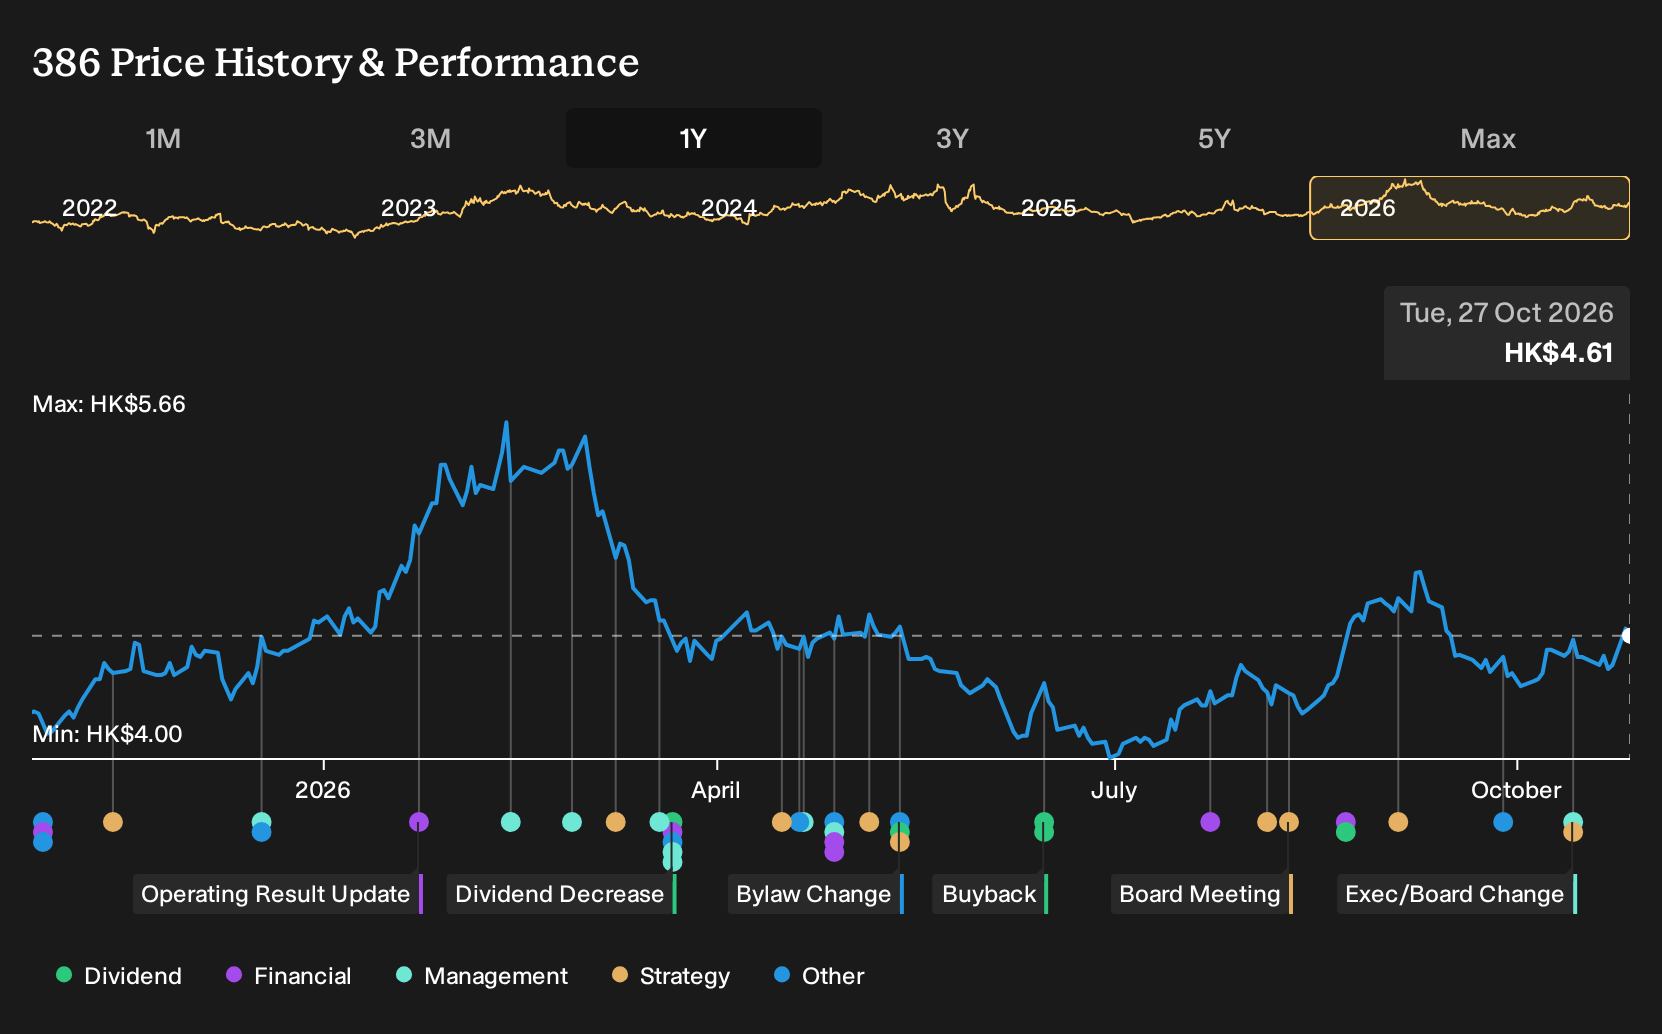
The executive change on 14 October 2026 is the announcement that matters most for this update. Moving company secretary duties to Zhang Zheng, who has run the Board Secretariat and securities matters since 2020, concentrates market attention on governance, disclosure quality and how clearly China Petroleum & Chemical communicates its transition story.
For catalysts, investors are still likely to focus more on integration of the aviation fuel supply chain, new low carbon projects and specialty chemical capacity than on this appointment. The governance change can support execution if it results in clearer reporting and quicker responses to listing rule requirements, but operational delivery on refining, chemicals and new energy remains the main swing factor.
China Petroleum & Chemical is currently expected to keep revenue broadly level and reach forecast earnings of CN¥53.5b by 2029, compared with earnings today of CN¥35.3b. This implies an earnings increase of about CN¥18.2b over that period.
Uncover how China Petroleum & Chemical's fair value indicates a 10% potential upside to its current price before other investors fully price in China Petroleum & Chemical's transition story.
Exploring Other Perspectives
You might read the China Petroleum & Chemical catalyst conference as a positive sign for higher value chemicals, yet the lowest analysts still frame refinery pressure as the bigger story. They were pencilling in CN¥2,381.4b of revenue and CN¥48.9b of earnings by 2029, a more cautious path that could shift if this catalyst push changes expectations.
Explore 4 other China Petroleum & Chemical fair value estimates, including one that suggests as much as 26% downside from the current price.
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your China Petroleum & Chemical research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for China Petroleum & Chemical. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate China Petroleum & Chemical's overall financial health at a glance.
Looking For More Investment Ideas Beyond China Petroleum & Chemical?
If the China Petroleum & Chemical story has you thinking about where else earnings quality, balance sheet strength or income potential might be mispriced, the Simply Wall St Screener can help you cast a wider net without losing focus on fundamentals.
- For investors who want quality and value working together, start with a curated group of 195 high quality undervalued stocks that combine strong fundamentals with prices that may not fully reflect their earning power.
- If capital preservation and stability sit higher on your priority list, consider a basket of 223 resilient stocks with low risk scores that screen well on resilience and lower risk scores.
- When the goal is to put cash flow to work, income seekers can scan a set of 224 dividend fortresses that pair 5%+ yields with more robust business profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com