


GreenOak Rebrand Altering The Investment Case For Sun Life Stock?
- SLC Management, which is majority owned by Sun Life Financial, has combined its US$326b platform under a single global GreenOak brand. The platform now covers alternative and investment grade credit, real estate and infrastructure strategies with unified distribution.
- This consolidation brings BGO, Crescent Capital, InfraRed Capital Partners, SLC Fixed Income and Advisors Asset Management into one platform. The unified structure gives Sun Life Financial a clearer foundation for scaling fee based investment management alongside its traditional insurance activities.
- The next section explores how Sun Life Financial's investment narrative could evolve as SLC Management centralizes its global platform under GreenOak.
Scan how Sun Life Financial's GreenOak platform compares with other asset managers by running through our curated list of list of solid balance sheet and fundamentals (7 results).
Sun Life Financial Investment Narrative Recap
To own Sun Life Financial, you need to be comfortable with a mix of traditional insurance earnings and fee based income from asset management. The GreenOak consolidation fits that story but does not change the near term swing factors on its own. The most important short term catalyst still sits in execution across Asia, group benefits and capital deployment.
The biggest near term risk remains pressure in U.S. Dental and any fee or margin strain in asset management, which could offset progress elsewhere. GreenOak integration helps simplify the alternatives platform, but the impact on overall earnings and valuation will depend on how well those segments absorb pricing, regulatory and volume headwinds.
The GreenOak announcement directly links to an earlier focus on expanding SLC Management into a roughly US$400b alternatives platform. Pulling BGO, Crescent Capital, InfraRed Capital Partners, SLC Fixed Income and Advisors Asset Management into one umbrella gives Sun Life Financial a cleaner way to present that fee based business to clients and shareholders.
For catalysts, this integration can matter if it supports cross selling, steadier fundraising and tighter cost control, which are all operational levers rather than branding alone. The flip side is execution risk. Any misstep that leads to weaker investment flows, softer fees or slower synergy delivery could amplify existing concerns about asset management margins and blunt the benefits of the GreenOak rebrand.
Sun Life Financial Consensus Assumptions In Focus
Analysts tracking Sun Life Financial are working with relatively specific building blocks. They are modelling revenue growth of 3.9% a year over the next three years, a lift in profit margin from 9.3% today to 12.0% by 2029, and a move in earnings from CA$3.3b now to CA$4.8b in that same period. The forecast year that anchors these assumptions is 2029, which is also where the analyst P/E framework and price targets converge.
That jump in earnings from CA$3.3b to CA$4.8b implies an increase of roughly CA$1.5b, which is a sizeable step up for an insurer and asset manager of this scale. Analysts are also building in a very small 0.1% annual decline in the share count over the next three years, so much of the earnings trend they are using is about underlying profit rather than heavy reliance on buybacks. For readers watching the GreenOak platform, this context matters because the fee based business will sit alongside these group level profit and margin targets rather than replacing them.
On top of the earnings profile, the analyst framework assumes the market is willing to value Sun Life Financial at a P/E of 16.1x on those 2029 earnings, down from 18.4x today and slightly below the current 16.2x P/E cited for the broader Canadian insurance peer group. That shift means the valuation case in the consensus work does not depend on a richer multiple. It leans on the combination of modest revenue expansion, better profitability and a cleaner capital structure.
Sun Life Financial's narrative projects CA$39.9b revenue and CA$4.8b earnings by 2029. This assumes 3.9% yearly revenue growth and an earnings increase of about CA$1.5b from CA$3.3b today.
For an investor thinking through GreenOak, the key takeaway is that these numbers already bake in both the insurance and asset management ambitions that management has laid out. The margin increase from 9.3% to 12.0% and the move to CA$4.8b in earnings are not tied to one product or geography. They rest on steady progress across Asia insurance, U.S. group benefits, SLC Management and cost control, with the GreenOak umbrella acting as one support for the fee based side of that mix.
Uncover why Sun Life Financial's fair value indicates a 3% potential upside to its current price, which could narrow quickly.
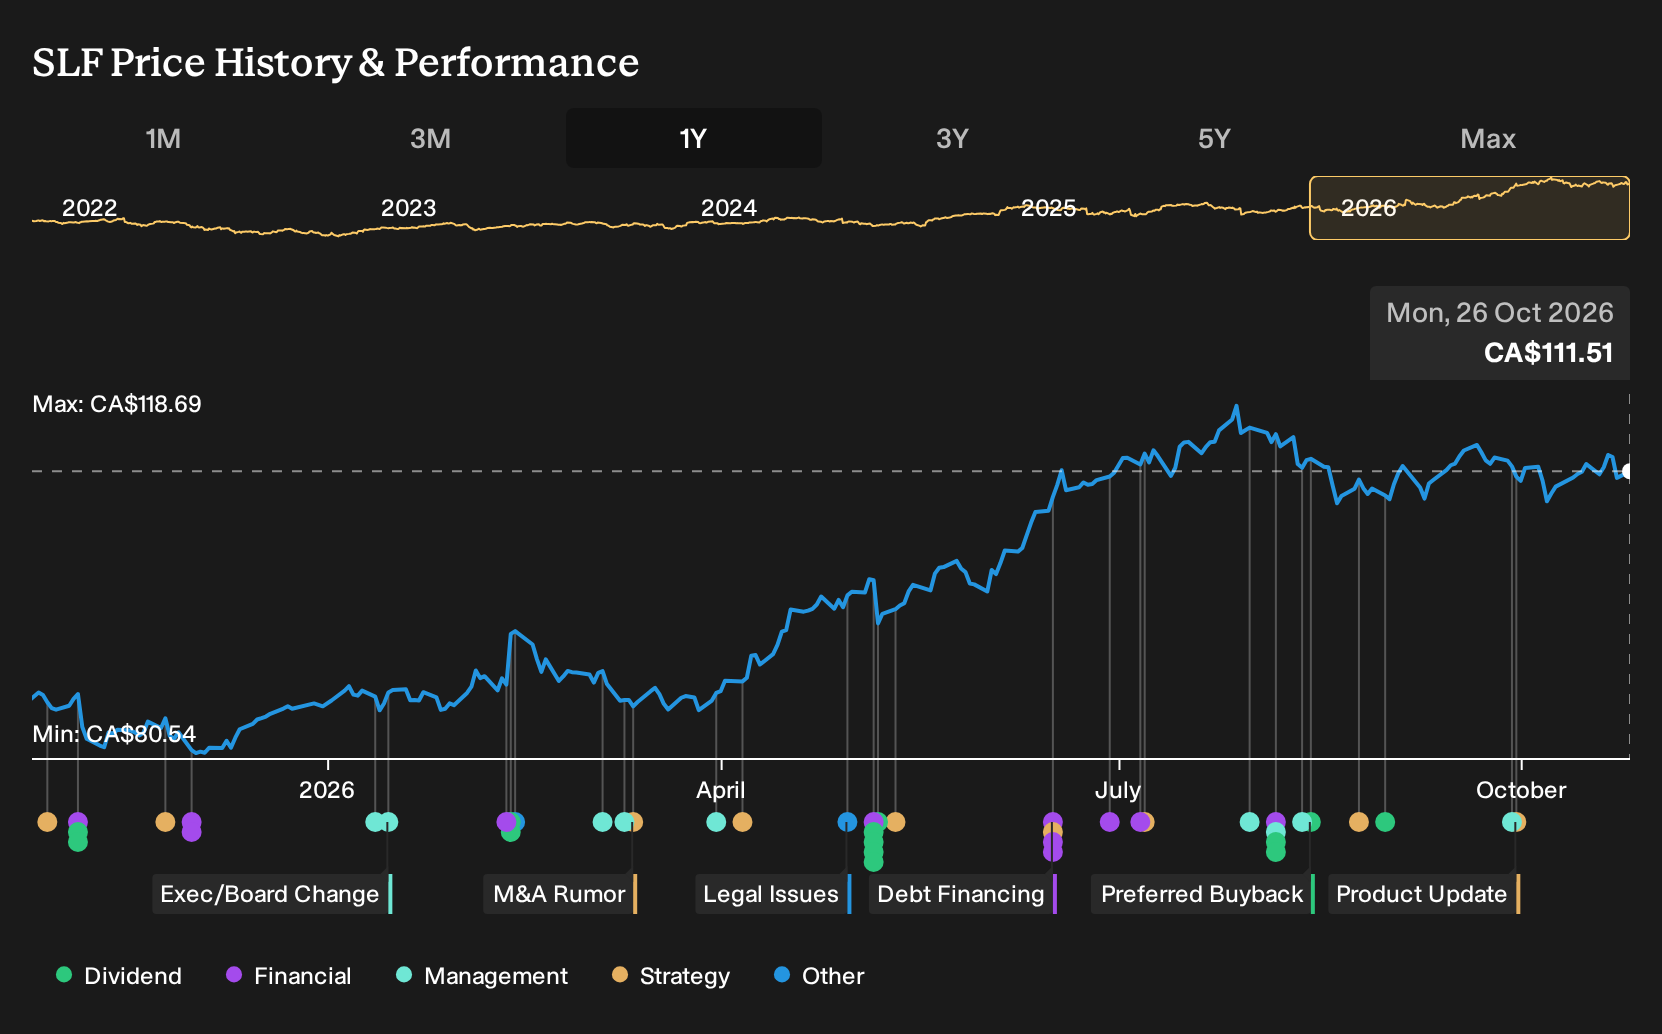
Exploring Other Perspectives
You might read the GreenOak news as a clear win for Sun Life Financial, yet the lowest analysts focus on a different angle. They worry about heavier use of private credit inside SLC Management. Before this update, that group was pencilling in CA$48.6b revenue and CA$4.7b earnings by 2029, but still attached a lower 13.4x P/E. Opinions clearly span a wide range. Treat this rebrand as a fresh reason to compare those more cautious views with your own expectations.
Explore another Sun Life Financial fair value estimate, including one that suggests it could be worth just CA$114.69.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Sun Life Financial research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Sun Life Financial. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Sun Life Financial's overall financial health at a glance.
Looking for more Sun Life Financial sized ideas?
Once you have formed a view on Sun Life Financial, it can help to line it up against other opportunities that match your risk tolerance, income needs and return goals.
- For investors who want quality at a reasonable entry point, compare Sun Life Financial with a curated group of 3 high quality undervalued stocks that pair solid fundamentals with more modest pricing.
- If capital preservation and steadier profiles matter most to you, scan a 8 resilient stocks with low risk scores that screens for resilient balance sheets and fewer red flags.
- To broaden your watchlist beyond the usual large caps, look across a 9 high quality undiscovered gems where strong financials have not yet attracted widespread attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com