


US Stock Market Today: S&P 500 Futures Ease As Oil Supply Concerns Build
The Morning Bull - US Market Morning Update Tuesday, Oct, 27 2026
US stocks are set for a cautious, slightly softer open, with sentiment centering on energy supply risk. The big swing factor this morning is the fresh US strategic petroleum reserve data, which has pushed crude and volatility expectations higher.
The SPR has dropped to 282.6 million barrels, the lowest level since 1982, alongside an emergency exchange of up to 400,000 barrels tied to a refinery issue. That combination raises questions about the cushion against future supply shocks and colors today’s risk appetite across equity indices.
Tighter perceived oil availability tends to feed into higher expected fuel costs, which can pressure margins for energy intensive industries and complicate inflation views. When investors reassess that cost backdrop, it often feeds directly into implied paths for policy rates and earnings multiples.
The unresolved question is whether upcoming weekly API and EIA crude stock data confirm a sustained draw on US supplies or show some rebuilding. That verdict will help determine whether energy remains a short lived scare or the key driver of market psychology into the Fed decision.
Stocks to Watch Before the Opening Bell
CoreWeave (CRWV)
CoreWeave is in focus after announcing fresh AI cloud capacity in Denmark and the build out of what it calls a global AI backbone network spanning North America, Europe, the Middle East, and Asia Pacific. Anthropic’s IPO filing has also pulled CoreWeave into the conversation as investors reassess funding, debt exposure, and demand tied to large AI contracts.
Visa (V)
Visa faces a proposed £5b collective lawsuit in the UK over multilateral interchange fees. Law firms have asked the UK Competition Appeal Tribunal to let roughly 1 million businesses join on an opt out basis. Readers should watch for any decision on whether the case proceeds as a class style action and for signals around potential financial exposure.
Mastercard (MA)
Mastercard is named alongside Visa in the same UK claim targeting card payment fees over a six year stretch. The filing argues that alleged anti competitive practices raised costs for merchants. The next key step is whether the tribunal approves a collective proceedings order, which would clarify how broad the legal risk could be for Mastercard.
Top Movers
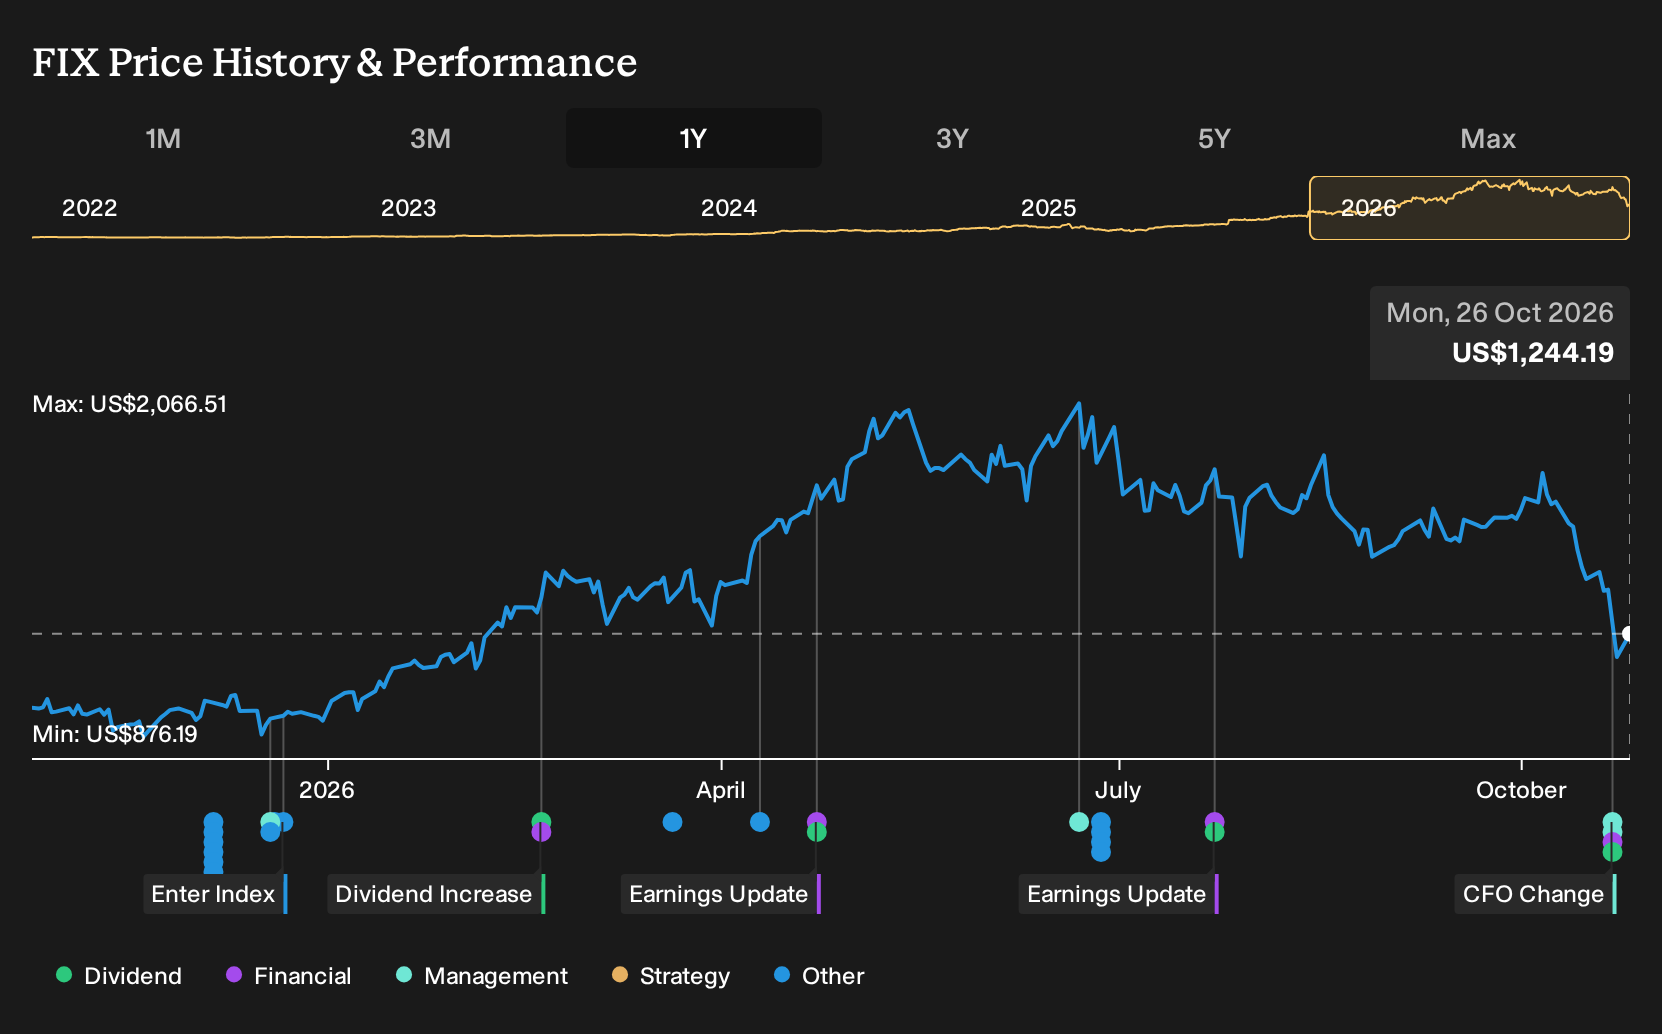
- Comfort Systems USA (FIX) jumped 7.18% after strong Q3 results, a record backlog, and a higher quarterly dividend.
- Coherent (COHR) climbed 5.83% after StoneX initiated coverage with a Buy rating and a US$425 price target.
- Bloom Energy (BE) rose 5.49% after earnings beat expectations and management raised full year 2026 revenue guidance.
Top Losers
- Nu Holdings (NU) fell 16.95% after Brazil's surprise Lula election win sparked a broad selloff in local financial stocks.
- MercadoLibre (MELI) declined 7.81% as Lula's reelection raised concern over Brazil's fiscal outlook and higher domestic borrowing costs.
- DoorDash (DASH) dropped 6.10% following reports it is in advanced talks to acquire Instacart at a multi billion valuation.

On The Radar
The next few sessions pivot around the Fed and a dense run of US data, capped by Apple earnings. Together, these shape how you think about rates, housing, manufacturing, and mega-cap tech.
- Fed Interest Rate Decision, Wed 28 Oct. The target rate previously sat at 4% and consensus points to 4.0%, so any shift in the policy rate or guidance affects funding costs across US equities, especially rate sensitive banks, REITs, and growth stocks.
- US Q3 GDP Growth Rate QoQ Adv, Thu 29 Oct. Economists look for 3.2% versus a prior 2.2%. A weaker print would pressure consumer cyclicals, while a firmer reading supports earnings assumptions embedded in broad US indices.
- US Core PCE Price Index MoM, Thu 29 Oct. Forecast sits at 0.3% after a previous 0.2%. A higher run rate tightens the screws on future Fed decisions and typically weighs on long duration tech and high P/E growth stocks.
- US Employment Cost Index QoQ, Fri 30 Oct. Markets expect 0.8% after 0.9%. A hotter wage and benefits mix would add pressure to corporate margins while reinforcing concerns about sticky inflation and higher for longer borrowing costs.
- Apple, Mon 2 Nov. Q4 2026 results spotlight guidance and revenue mix across iPhone, services, and wearables. These often set the tone for mega-cap tech sentiment and influence where investors position within the broader US market.
Sector & Industry Watch
Energy: Oil rally backed by deal flow
Energy has climbed over the past week and month, with 1 year and year to date returns running clearly ahead of the US Market. M&A in Oil and Gas, including EQT’s planned purchase of Range Resources and Ovintiv’s Logan deal, reinforces the focus on scale at a time when US strategic petroleum reserve levels are at multi decade lows.
If you hold broad energy ETFs or producers, the single data point to watch now is this week’s EIA crude inventory release, since a fresh draw would keep supply worries and sector momentum alive into the Fed meeting.
Real Estate: REITs lean on steady demand stories
Real Estate is higher over the last 7 days and over the past month, while 1 year performance sits close to flat. Activity around grocery anchored and industrial property, from Brixmor’s Slate Grocery REIT acquisition plan to LXP Industrial Trust’s sale, shows investors still paying for predictable rent streams even with higher financing costs.
If you own US REITs, Wednesday’s Fed interest rate decision is the key swing factor because any hint the policy rate could stay at 4% for longer keeps refinancing and cap rate pressures in focus.
Tech & Semiconductors: AI buildout meets funding reality
Tech is only slightly positive over the past week after a softer 30 day stretch, while Semiconductors show a similar pattern with strong year to date gains but recent pullback. Headlines around Meta’s plan to raise up to US$95b for AI and SpaceX’s US$40b GPU lease underline how capital hungry this theme is, just as some AI focused cloud operators face tighter lending conditions.
If your portfolio leans heavily into AI chips or cloud platforms, Anthropic’s IPO roadshow and commentary from banks financing Broadcom hardware are the catalyst to watch, since signals on demand visibility and credit terms help explain whether the recent 7 day softness turns into a longer pause.
Consumer Staples: Defensive spending holds the line
Consumer Staples are up over the past week and month with 1 year and year to date returns ahead of the broad US Market. Company news from PriceSmart’s warehouse expansion to Walmart’s holiday campaign and Albertsons’ delivery subscription shows retailers still investing where they see steady everyday demand, even as some discount chains such as Dollar General deal with pricing lawsuits.
If you use Staples as a buffer in your portfolio, Thursday’s US Core PCE inflation release is the main macro input, since a firmer reading keeps the case for resilient, needs based spending in focus.
Healthcare & Pharmaceuticals & Biotech: Trial wins support steady growth story
Healthcare and Pharmaceuticals & Biotech have gained over the past week and month and sit comfortably ahead on a 1 year view. A run of positive cancer and rare disease updates from Merck, Pfizer, Mirum, Oruka and others keeps attention on drug pipelines rather than discretionary spending swings, and M&A such as Surgery Partners’ buyout underlines ongoing interest in healthcare services.
If you hold healthcare ETFs for balance, Friday’s US Employment Cost Index is the one macro release to watch, since hotter wage growth can squeeze many sectors but often lands more gently on businesses where demand is less tied to day to day consumer budgets.
Identify The Next Market Leaders
With US energy supply concerns back in focus after the SPR slipped to 282.6 million barrels, you can tilt toward sturdier balance sheets by starting with this list of list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com